

Every business owner faces the reality that their company's success often depends on specific people. Whether you're a sole proprietor in Greensboro, a partner in High Point, or managing a team in Winston Salem, the unexpected loss of a key person can create immediate financial strain. Business life insurance provides a financial safety net that keeps your company stable when tragedy strikes, protecting everything you've built from sudden disruption.
What Business Life Insurance Really Means
Business life insurance is a specialized form of coverage where a company purchases a policy on the life of an owner, partner, or key employee. Unlike personal coverage that protects families, business life insurance protects the company itself. The business pays the premiums, owns the policy, and receives the death benefit if the insured person passes away.
This arrangement creates a financial cushion during what would otherwise be a catastrophic period. The death benefit can cover immediate expenses, replace lost revenue, recruit and train replacements, or facilitate ownership transitions. For many companies across the Triad Area, this protection represents the difference between continuity and closure.
Why Companies Need This Protection
Revenue Replacement: Key employees often generate significant income for businesses. Their absence can reduce revenue by 30% or more in some industries.
Debt Coverage: Business loans frequently require personal guarantees. If a guarantor dies, lenders may call the loan immediately without adequate protection in place.
Recruitment Costs: Finding and training qualified replacements takes time and money, often requiring six months or more for executive-level positions.
Ownership Transitions: Partners or co-owners need funds to buy out a deceased owner's share from their family, preventing forced liquidation.
Types of Business Life Insurance Coverage
Understanding the different applications helps you choose the right protection for your situation. Each serves distinct purposes within comprehensive business planning.
Key Person Insurance
This coverage protects companies from the financial impact of losing someone critical to operations. The business purchases a policy on individuals whose skills, relationships, or knowledge drive success. When that person dies, the company receives funds to:
- Maintain operations during the transition period
- Cover lost profits until a replacement gets up to speed
- Pay off business debts or obligations
- Reassure clients, vendors, and lenders about stability
| Coverage Amount | Typical Use Case | Monthly Premium Range |
|---|---|---|
| $250,000 | Small business owner | $75 – $150 |
| $500,000 | Mid-level executive | $125 – $300 |
| $1,000,000+ | Senior leadership/founders | $250 – $600+ |
Buy-Sell Agreement Funding
Partners and co-owners use business life insurance to fund buy-sell agreements. These legal contracts specify what happens to ownership interests when an owner dies. The insurance provides immediate cash for surviving owners to purchase the deceased owner's shares from their estate.
Without this funding mechanism, families of deceased owners might demand payment the business cannot afford, or worse, they might want to become active owners despite lacking experience. Buy-sell agreements backed by life insurance prevent these scenarios entirely.
Executive Bonus Plans
Companies can offer life insurance as an executive benefit. The business pays premiums on policies owned by key employees, who name their own beneficiaries. The premium payments count as taxable compensation to the employee but provide valuable protection their families need.
Split-Dollar Arrangements
These sophisticated plans split policy costs and benefits between employer and employee. The business typically pays premiums while both parties share in the policy's value. This arrangement works well for retaining top talent in competitive markets like Greensboro and Kernersville.
Determining How Much Coverage You Need
Calculating appropriate coverage requires honest assessment of what losing specific people would cost your business. Unlike life insurance for personal needs, business coverage focuses on financial impact rather than income replacement for families.
Revenue Contribution Method: Multiply the person's annual revenue contribution by 5-10 years. A salesperson generating $500,000 annually might warrant $2.5 to $5 million in coverage.
Cost of Replacement Method: Add recruiting fees, training costs, lost productivity, and temporary staffing expenses. Executive replacements often cost 150-200% of annual salary.
Outstanding Debt Method: Calculate total business debts requiring the person's guarantee or participation. Many lenders require coverage equal to the loan balance.
Ownership Percentage Method: For buy-sell funding, multiply the business valuation by the owner's percentage. A 40% owner in a $1 million business needs $400,000 in coverage.
Choosing the Right Policy Type
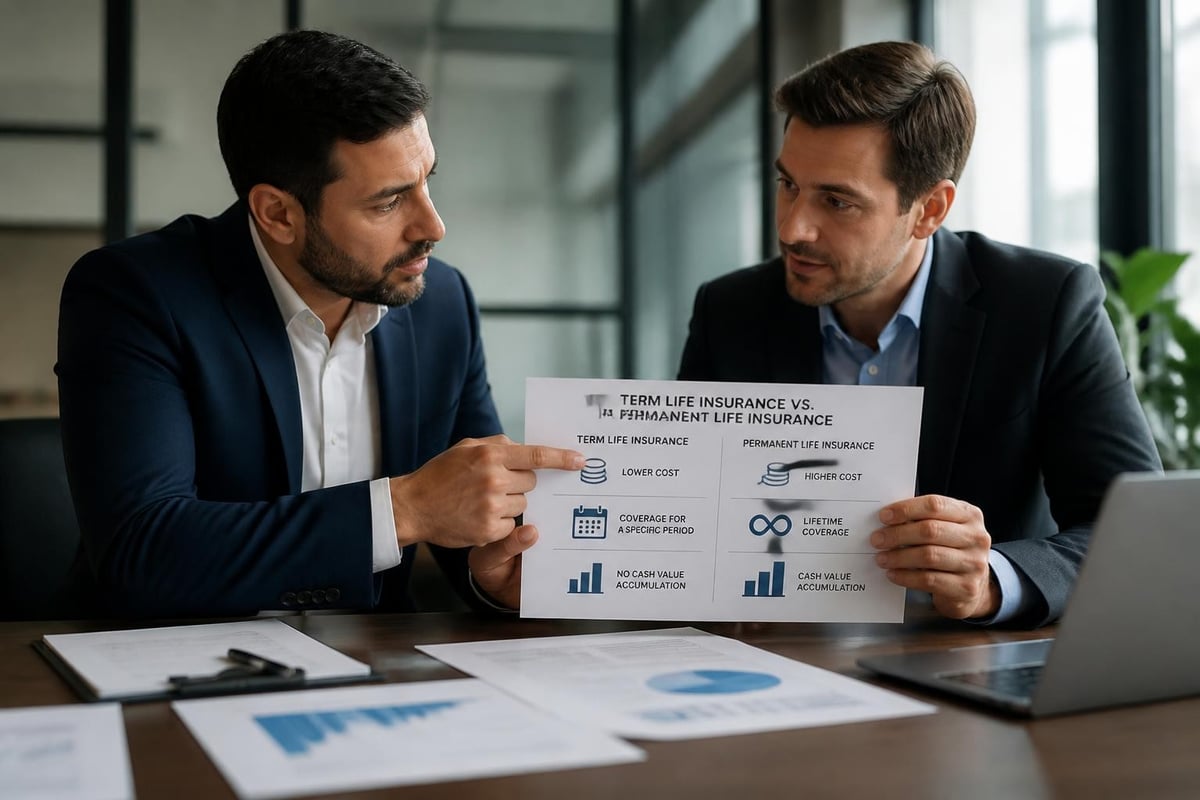
Business life insurance typically uses either term or permanent coverage, each offering distinct advantages depending on your goals and budget.
Term Life Insurance for Business
Term coverage provides protection for specific periods, usually 10, 20, or 30 years. This option costs significantly less than permanent insurance and works well for:
- Covering business loans with defined payoff dates
- Protecting against loss during a key employee's working years
- Temporary partnership situations
Advantages: Low premiums, predictable costs, straightforward structure
Drawbacks: No cash value accumulation, coverage expires, premiums increase significantly at renewal
Permanent Life Insurance Options
Permanent policies remain in force for the insured's lifetime and build cash value the business can access. These policies cost more but offer additional flexibility.
Whole Life Insurance: Fixed premiums, guaranteed cash value growth, predictable death benefit. Best for long-term succession planning.
Universal Life Insurance: Flexible premiums, adjustable death benefits, cash value tied to interest rates. Suitable when business cash flow varies.
Variable Universal Life: Investment options for cash value growth, maximum flexibility, higher risk potential. Appropriate for businesses comfortable managing investment risk.
Tax Implications and Benefits
Business life insurance creates specific tax consequences owners must understand before purchasing coverage. The tax treatment depends on policy structure and ownership.
Premium Deductibility
Generally, businesses cannot deduct premium payments as business expenses when the company is the beneficiary. The IRS views these payments as capital expenditures rather than ordinary business costs. However, premiums for executive bonus plans where employees own the policies may qualify as deductible compensation.
Death Benefit Taxation
Death benefits received by businesses are typically tax-free income. This represents a significant advantage, as a $500,000 death benefit provides the full amount without tax erosion. However, the alternative minimum tax (AMT) may affect larger C-corporations receiving substantial death benefits.
Cash Value Access
When businesses borrow against cash value or take withdrawals, they access these funds tax-free up to the total premiums paid. Loans never require repayment during the insured's lifetime, though outstanding balances reduce the death benefit.
Common Mistakes Business Owners Make
Inadequate Coverage Amounts
Many companies purchase minimal coverage to save on premiums, only to discover it barely covers immediate expenses when needed. Proper coverage should address the full financial impact, not just symbolic protection. Working with experienced advisors in the Triad Area helps ensure appropriate coverage levels.
Missing Policy Reviews
Business values change, key employees come and go, and debt levels fluctuate. Annual policy reviews ensure coverage keeps pace with evolving needs. A policy purchased five years ago may no longer reflect current circumstances.
Poor Beneficiary Designations
Incorrectly naming beneficiaries can undermine the entire purpose of business life insurance. Buy-sell agreements require precise coordination between legal documents and insurance beneficiaries. Similarly, key person policies must name the business entity correctly.
Ignoring Policy Ownership Rules
Who owns the policy matters tremendously for tax purposes and contractual obligations. Cross-purchase arrangements require different ownership structures than entity-purchase plans. Professional guidance prevents costly ownership mistakes.
The Application and Underwriting Process
Obtaining business life insurance follows a structured process requiring documentation and medical evaluation. Understanding these steps helps set realistic expectations.
- Initial Assessment: Determine coverage needs, policy type, and budget parameters
- Application Completion: Provide detailed personal and business information
- Medical Examination: Schedule paramedical exam including blood work and health history
- Financial Underwriting: Submit business financial statements, tax returns, and documentation
- Underwriting Review: Insurance company evaluates health and financial information
- Policy Offer: Receive premium quote based on underwriting results
- Policy Delivery: Review and sign final documents
The entire process typically takes 4-8 weeks for standard cases. Simplified issue policies offering faster approval with limited underwriting may work for smaller coverage amounts.
Cost Factors and Premium Considerations
Business life insurance premiums vary based on multiple factors affecting risk assessment. Understanding these variables helps you anticipate costs and potentially reduce premiums.
| Factor | Impact on Premiums | Potential Savings Strategy |
|---|---|---|
| Age | Increases 8-12% annually after age 40 | Purchase coverage early |
| Health Status | Poor health can double or triple rates | Improve health before applying |
| Coverage Amount | Higher death benefits cost more | Right-size coverage needs |
| Policy Type | Permanent costs 5-15x more than term | Use term for temporary needs |
| Tobacco Use | Adds 100-300% to premiums | Quit for 12+ months before applying |
| Occupation | Hazardous work increases costs | Highlight office duties |
For a healthy 45-year-old business owner in Winston Salem, a $500,000 20-year term policy might cost $100-200 monthly. The same person purchasing $500,000 in whole life coverage could pay $500-800 monthly. Comparing multiple quotes ensures competitive pricing.
Integrating Business Life Insurance Into Your Overall Strategy
Effective business planning incorporates life insurance alongside other protective measures. This coverage works best as part of a comprehensive approach addressing multiple risks.
Succession Planning
Business life insurance facilitates smooth ownership transitions by providing immediate liquidity. Combined with detailed succession plans, it ensures leadership continuity and maintains company value during transitions.
Estate Planning Coordination
Business owners need coordination between business policies and personal estate plans. The same person might have personal coverage protecting their family and business coverage protecting the company. These policies must work together without conflicts or gaps.
Disability Insurance Complement
While life insurance addresses death, disability coverage protects against the more common scenario of serious illness or injury. Many businesses need both coverages on key people to ensure complete protection.
Emergency Fund Alternative
The cash value in permanent policies can serve as an emergency fund for businesses, offering accessible capital during challenging periods. This dual purpose justifies higher premiums for some companies.
Real-World Applications Across Industries
Business life insurance serves different purposes depending on industry and business structure. These examples illustrate practical applications across various sectors.
Medical Practices: A three-physician practice in High Point carries $1 million on each doctor. If one passes away, the death benefit covers patient notification, temporary staffing, and recruiting a replacement physician while maintaining practice operations.
Family Businesses: A second-generation manufacturing company uses $2 million in coverage on the founder to fund buyout agreements with adult children who don't work in the business, ensuring fair treatment while preserving company control for active family members.
Professional Partnerships: A law firm structures cross-purchase agreements where each partner owns policies on the others. When one partner dies, survivors use the insurance proceeds to purchase the deceased partner's interest from their estate.
Startups: A technology company secures key person insurance on its developer and sales leader, reassuring investors that the company can survive the loss of essential talent during critical growth phases.
Selecting the Right Insurance Provider
Choosing a financially stable insurance carrier protects your business from the risk of insurer insolvency. Several factors distinguish quality carriers from mediocre ones.
Financial Strength Ratings: Look for carriers rated A+ or better by A.M. Best, AA or higher by S&P. These ratings indicate the company's ability to pay claims decades into the future.
Claims Paying History: Research how quickly and fairly the carrier processes death claims. Some companies have reputations for contested claims or slow payments.
Business Insurance Expertise: Carriers specializing in business life insurance understand complex arrangements like buy-sell funding and offer specialized underwriting for business owners.
Service Quality: Evaluate the carrier's customer service, online tools, and support for policy management over time.
If you're exploring coverage options in Kernersville or throughout the Triad Area, connecting with knowledgeable local advisors helps you navigate carrier selection while understanding how policies might integrate with your existing health insurance and Medicare planning.
Maintaining and Updating Your Coverage
Business life insurance requires ongoing attention to remain effective. Regular maintenance ensures coverage aligns with current business realities.
Annual Policy Reviews
Schedule yearly reviews examining coverage amounts, beneficiaries, and premium payment methods. Business growth, new debt, or changed partnerships may necessitate adjustments.
Ownership Transfer Considerations
If business ownership changes, policy ownership and beneficiaries must change accordingly. Selling your business interest without updating insurance creates complications for all parties.
Premium Payment Strategies
Businesses can pay premiums annually, quarterly, or monthly. Annual payments often save 3-5% compared to monthly installments, providing meaningful savings on large policies.
Cash Value Management
For permanent policies, decide whether to let cash value accumulate, take loans, or make withdrawals. Each choice affects the death benefit and long-term policy performance.
Coordinating With Professional Advisors
Implementing business life insurance effectively requires coordination among multiple professionals. Your team should include:
- Insurance Advisor: Structures appropriate coverage and manages the underwriting process
- Attorney: Drafts buy-sell agreements and ensures legal compliance
- Accountant: Advises on tax implications and financial reporting
- Financial Planner: Integrates insurance into overall business financial strategy
This collaborative approach prevents gaps and conflicts while maximizing the value of your coverage investment.
Special Considerations for Small Businesses
Smaller companies face unique challenges when implementing business life insurance. Limited cash flow, informal management structures, and concentrated ownership create specific planning needs.
Affordability Concerns: Small businesses often struggle with premium costs. Starting with term coverage provides essential protection at manageable costs, with conversion to permanent policies possible as the business grows.
Simplified Structures: Elaborate arrangements may overcomplicate planning for businesses with just two or three owners. Straightforward key person coverage and basic buy-sell funding often suffice.
Personal Guarantee Protection: Small business loans almost always require owner guarantees. Coverage protecting the business from these obligations should take priority over more sophisticated planning.
Succession Complexity: Without clear successors, small businesses need thoughtful planning beyond just insurance. Coverage provides funds, but comprehensive succession plans direct how to use those funds effectively.
For businesses throughout Greensboro and the surrounding areas, understanding these considerations helps create realistic protection strategies that balance comprehensive coverage with budget constraints.
Business life insurance represents essential protection for companies depending on key individuals for success, providing financial stability during the most challenging transitions. Whether you need key person coverage, buy-sell agreement funding, or executive benefits, the right insurance strategy protects everything you've built. At Moser Insurance Group Inc, we help business owners in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area understand their protection options with clear guidance and personalized support. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to explore how business life insurance can safeguard your company's future.
Recent Comments