

Term life insurance provides essential financial protection for your family, but many people hesitate because they view premiums as money that disappears if nothing happens. That's where term insurance with return of premium comes in-a hybrid product that combines the affordability of term coverage with the peace of mind that you'll get your money back if you outlive the policy. For families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understanding this option can help you make a more confident insurance decision.
Understanding Term Insurance with Return of Premium
The best term insurance plan with return of premium offers comprehensive death benefit protection while guaranteeing a full refund of all premiums paid if you survive the policy term. Unlike traditional term life insurance that expires worthless, these plans function as both protection and a forced savings mechanism.
How These Plans Actually Work
When you purchase a return of premium policy, you're essentially paying a higher premium than you would for standard term coverage. This additional cost funds the return feature, which ensures that every dollar you've paid gets returned to you at maturity.
Key operational features include:
- Higher monthly premiums compared to traditional term policies
- Full premium refund if you survive the entire term
- Death benefit payout if you pass away during the coverage period
- No cash value accumulation during the policy term
- Tax-free return of premiums at maturity
The policy structure differs significantly from term life insurance options that expire without value. You're paying extra for the certainty that your investment won't vanish, which appeals to risk-averse individuals who want comprehensive protection without feeling like they're wasting money.
Evaluating the Best Return of Premium Features
When searching for the best term insurance plan with return of premium, specific features distinguish superior products from mediocre ones. Understanding these elements helps you identify policies that deliver genuine value rather than just marketing promises.
Coverage Amount Flexibility
Top-tier plans offer coverage ranging from $100,000 to $5 million or more, allowing you to match protection to your actual financial obligations. Your coverage should account for:
- Outstanding mortgage balance
- Future education costs for children
- Income replacement needs for dependents
- Final expense obligations
- Outstanding debts and loans
Term Length Options
| Term Duration | Best For | Premium Return Timeline |
|---|---|---|
| 10 Years | Short-term debts, young children | Fastest return |
| 20 Years | Primary working years, mortgage protection | Balanced approach |
| 30 Years | Long-term obligations, comprehensive coverage | Maximum protection period |
The term insurance with return of premium structure you select should align with your specific financial timeline. A 30-year policy makes sense if you're protecting young children through college, while a 10-year term might suffice for covering a specific loan.
Premium Payment Structures
Different insurers offer varied payment schedules that affect your cash flow and total cost. You can typically choose between:
- Level premium payments: Fixed amounts throughout the term
- Limited payment options: Pay up in 10-15 years, coverage continues
- Annual vs. monthly: Frequency options to match your budget
Comparing Costs and Value Propositions
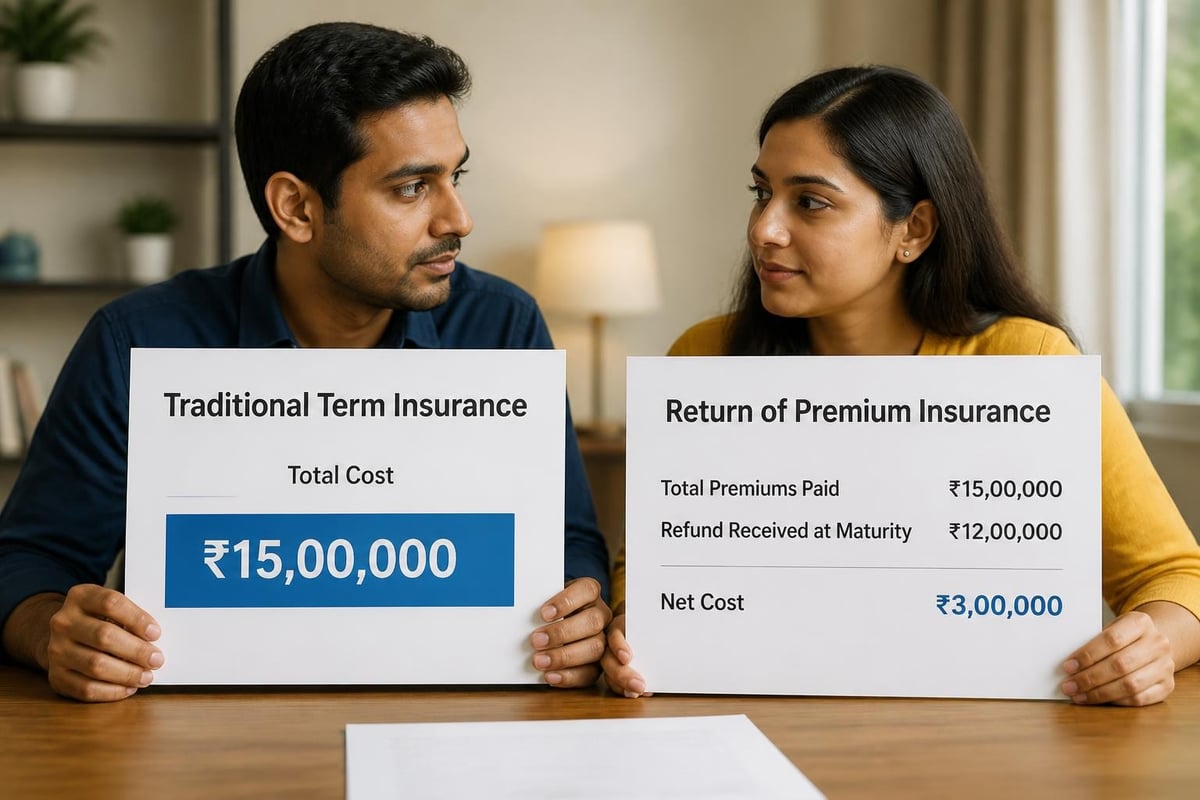
The best term insurance plan with return of premium costs significantly more than standard term coverage-typically 30-50% higher premiums. However, this premium difference represents the cost of the return feature, not wasted money.
Breaking Down the True Cost
Consider a 40-year-old non-smoking male seeking $500,000 in coverage for 20 years. A standard term policy might cost $40 monthly ($9,600 total over 20 years), while a return of premium version could run $65 monthly ($15,600 total). The $6,000 difference represents what you're paying for the guarantee of getting your money back.
Cost analysis factors include:
- Your current age and health status
- Tobacco use and medical history
- Coverage amount selected
- Term length chosen
- Insurance company underwriting standards
For residents throughout Greensboro, Kernersville, High Point, and Winston Salem, working with knowledgeable advisors helps you understand whether the premium difference makes financial sense for your situation. You can reach out at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific needs.
When Return of Premium Makes Financial Sense
This coverage type works best for specific situations where the return feature provides real value. You're likely a good candidate if you:
- Have a disciplined savings approach but want forced accountability
- View premium payments as lost money with traditional term insurance
- Can afford the higher premiums without financial strain
- Plan to maintain the policy through the full term
- Want life insurance but also value asset accumulation
According to detailed analyses of return of premium benefits, the math works favorably when you actually keep the policy in force. Early termination eliminates the return benefit, leaving you with nothing-just like standard term insurance.
Key Benefits Beyond Premium Return
While getting your money back represents the primary advantage, the best term insurance plan with return of premium offers additional benefits that increase overall value. These secondary features often justify the higher premium cost for the right buyer.
Financial Discipline and Forced Savings
The policy creates automatic savings through required premium payments. You can't easily skip payments without losing coverage, which enforces financial discipline that many people struggle to maintain independently. This structured approach helps families build financial security even when other savings efforts fail.
Inflation Protection Through Death Benefits
Your death benefit remains constant regardless of inflation, but having any protection beats having none. Some policies offer riders that increase the death benefit annually to maintain purchasing power, though this adds to your premium cost.
Tax Advantages at Multiple Levels
Return of premium policies deliver tax benefits in several ways:
- Death benefits paid tax-free to beneficiaries
- Premium returns received tax-free as return of principal
- No taxation on the "savings" component during accumulation
Conversion Options for Changing Needs
Many top policies include conversion privileges allowing you to exchange your term coverage for permanent insurance without new medical underwriting. This flexibility proves valuable if your health deteriorates or your financial goals shift toward permanent coverage.
Evaluating Top Insurance Providers
The best term insurance plan with return of premium comes from financially stable insurers with proven claims-paying records. Not all insurance companies offer this product type, and quality varies significantly among those that do.
Essential Provider Criteria
| Evaluation Factor | Why It Matters | What to Look For |
|---|---|---|
| Financial Ratings | Company stability and claims-paying ability | A.M. Best rating of A or higher |
| Premium Competitiveness | Overall affordability | Quotes from multiple carriers |
| Underwriting Flexibility | Approval likelihood for your health profile | Experience with your specific conditions |
| Customer Service | Support during claims and questions | Reviews and complaint ratios |
| Policy Options | Customization to your needs | Rider availability and term choices |
When exploring options through resources at moserinsurancegroup.com, you gain access to multiple carriers without the hassle of contacting each individually. This streamlined approach saves time while ensuring comprehensive comparison.
Understanding Policy Riders and Add-Ons
The best policies offer riders that enhance basic coverage for specific needs. Common valuable additions include:
- Waiver of premium: Continues coverage if you become disabled
- Accelerated death benefit: Advances payment for terminal illness
- Accidental death benefit: Doubles payout for accidental death
- Child term rider: Adds coverage for dependent children
Each rider increases your premium but provides targeted protection for specific concerns. Evaluate whether each addition addresses a real risk in your life rather than purchasing coverage you don't need.
Application Process and Underwriting Considerations
Securing the best term insurance plan with return of premium requires navigating the application and underwriting process. Understanding what insurers evaluate helps you prepare and potentially secure better rates.
Medical Underwriting Requirements
Most return of premium policies require full medical underwriting, including:
- Comprehensive health questionnaire
- Medical exam with blood and urine samples
- Review of prescription history
- Analysis of medical records for significant conditions
- Height, weight, and blood pressure measurements
Your health classification determines your premium rate. Understanding how insurers assess risk helps you anticipate your likely rate class and budget accordingly.
Improving Your Underwriting Outcome
Actions that can lower your premiums include:
- Losing excess weight before applying
- Managing chronic conditions with consistent treatment
- Stopping tobacco use for at least 12 months
- Correcting identified health issues before application
- Being completely honest about your medical history
Attempting to hide medical conditions never works. Insurers discover undisclosed issues through prescription databases and medical records, which can result in coverage denial or future claim rejection.
Return of Premium vs. Other Life Insurance Options
Comparing the best term insurance plan with return of premium against alternative products helps you determine the optimal solution for your specific situation. Each insurance type serves different purposes and priorities.
Return of Premium vs. Standard Term Insurance
Standard term provides the same death benefit at significantly lower cost but offers no return if you survive the term. The math strongly favors standard term if you're disciplined enough to invest the premium difference yourself.
Consider standard term when you:
- Have strong investment discipline
- Want maximum coverage for minimum premium
- Understand insurance as protection, not investment
- Can accept "wasted" premiums as the cost of peace of mind
Return of Premium vs. Whole Life Insurance
Whole life policies cost substantially more than return of premium term but provide lifetime coverage and actual cash value accumulation. The policy never expires, and the cash value grows tax-deferred.
Comparison of permanent coverage options:
| Feature | Return of Premium Term | Whole Life |
|---|---|---|
| Duration | Fixed term (10-30 years) | Lifetime coverage |
| Premium | Moderate | Highest |
| Cash Value | None during term | Grows throughout life |
| Return Feature | 100% premium refund | Cash value + death benefit |
| Flexibility | Conversion options | Loan and withdrawal privileges |
For many families in the Triad Area, combining affordable term coverage with separate investment vehicles provides better overall value than purchasing expensive permanent policies. However, individual circumstances vary significantly.
Hybrid Approaches for Comprehensive Protection
Some financial advisors recommend combining standard term insurance for high coverage amounts with a small whole life policy for permanent protection. This approach delivers maximum death benefit during high-need years while maintaining lifetime baseline coverage.
Making Your Final Decision
Selecting the best term insurance plan with return of premium requires balancing multiple factors specific to your financial situation, family obligations, and personal preferences. No single "best" policy exists-only the best policy for your unique circumstances.
Critical Questions to Answer
Before purchasing, honestly evaluate:
- Can you afford the higher premiums without financial stress?
- Will you realistically maintain the policy through the full term?
- Do you have the discipline to invest premium savings elsewhere?
- Does the forced savings aspect provide genuine value for your situation?
- Are you comfortable with money "disappearing" if you choose standard term?
Working with Professional Guidance
Navigating life insurance options becomes significantly easier with expert guidance. Independent agents access multiple carriers and can provide objective comparisons without pushing specific products.
Professional advisors help you:
- Accurately calculate coverage needs based on your obligations
- Compare quotes from top-rated insurers simultaneously
- Understand policy language and contractual obligations
- Identify riders that add value versus unnecessary add-ons
- Navigate the application process efficiently
For personalized guidance throughout Greensboro, High Point, Winston Salem, and Kernersville, reaching out to experienced professionals ensures you make informed decisions. Contact 336-862-1763 or email moserinsurancegroup@gmail.com to discuss your specific needs.
Policy Management and Maximizing Your Investment
Once you've secured the best term insurance plan with return of premium, proper policy management ensures you actually receive the promised benefits. Many policyholders forfeit their return by letting coverage lapse before maturity.
Maintaining Coverage Through the Full Term
Essential management practices include:
- Setting up automatic premium payments to prevent accidental lapses
- Maintaining adequate bank balances to cover scheduled payments
- Reviewing beneficiary designations after major life changes
- Keeping contact information current with your insurer
- Understanding your grace period and reinstatement options
Missing even a single payment can trigger a grace period, and failing to pay within that window terminates your coverage. Reinstating a lapsed policy often requires new medical underwriting, potentially at higher rates if your health has declined.
When to Consider Converting or Adjusting Coverage
Life circumstances change over the policy term, sometimes making your original coverage amount insufficient or excessive. Quality return of premium policies include conversion options allowing you to exchange for permanent coverage without new medical exams.
Consider conversion when:
- You develop health conditions making new coverage difficult to obtain
- Your financial goals shift toward permanent insurance benefits
- You want to lock in insurability before the conversion period expires
- Your need for coverage extends beyond the original term
Maximizing the Return Benefit
To ensure you actually receive your premium refund at maturity, maintain meticulous records of all premium payments. While insurers track payments, having your own documentation prevents disputes and simplifies the claim process when the term ends.
Alternative Strategies for Financial Protection
While the best term insurance plan with return of premium serves specific needs well, alternative approaches might better suit your overall financial strategy. Consider these options alongside or instead of return of premium coverage.
Buy Term and Invest the Difference
This classic strategy involves purchasing less expensive standard term insurance and investing the premium savings in diversified portfolios. If you maintain investment discipline, you'll potentially accumulate more wealth than you'd receive from premium return.
This approach works best when you:
- Have strong financial self-discipline
- Understand basic investment principles
- Can maintain consistent contributions regardless of market conditions
- Accept market risk in exchange for higher potential returns
Ladder Multiple Term Policies
Rather than purchasing one large return of premium policy, consider "laddering" several standard term policies with staggered maturity dates. This strategy provides high coverage when needed while reducing premiums as obligations decrease.
For example, a 35-year-old parent might purchase:
- $500,000 for 30 years (through college graduation)
- $300,000 for 20 years (through high school)
- $200,000 for 10 years (near-term obligations)
Total coverage starts at $1 million but decreases as children become independent, reducing your long-term premium commitment.
Combining Coverage Types for Comprehensive Protection
Strategic families often combine multiple insurance products to address different needs. You might maintain affordable term coverage for income replacement while building cash value through a smaller whole life policy for permanent needs.
This hybrid approach delivers:
- Maximum death benefit during high-obligation years
- Guaranteed lifetime baseline coverage
- Tax-advantaged cash value growth
- Flexibility to adjust coverage as circumstances change
Choosing the right life insurance protection involves understanding your specific needs, available options, and long-term financial goals. Whether you select a return of premium policy, standard term coverage, or a combination approach depends on your unique situation and priorities. Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate insurance decisions with clear guidance and personalized support, ensuring you understand your options without pressure or confusion. Contact us at Moser Insurance Group Inc or call 336-862-1763 to discuss which coverage strategy makes the most sense for protecting your family's financial future.
Recent Comments