

Understanding the age to qualify for Medicare is essential for anyone approaching retirement or planning their healthcare future. While most people know Medicare is a federal health insurance program, the specific eligibility requirements and enrollment rules can be confusing. Whether you live in Greensboro, Winston Salem, High Point, Kernersville, or elsewhere in the Triad Area, knowing when you can enroll and what steps to take will help you avoid penalties and ensure continuous coverage. This comprehensive guide explains everything you need to know about Medicare eligibility ages, special circumstances, and how to navigate the enrollment process successfully.
Standard Age Requirements for Medicare Eligibility
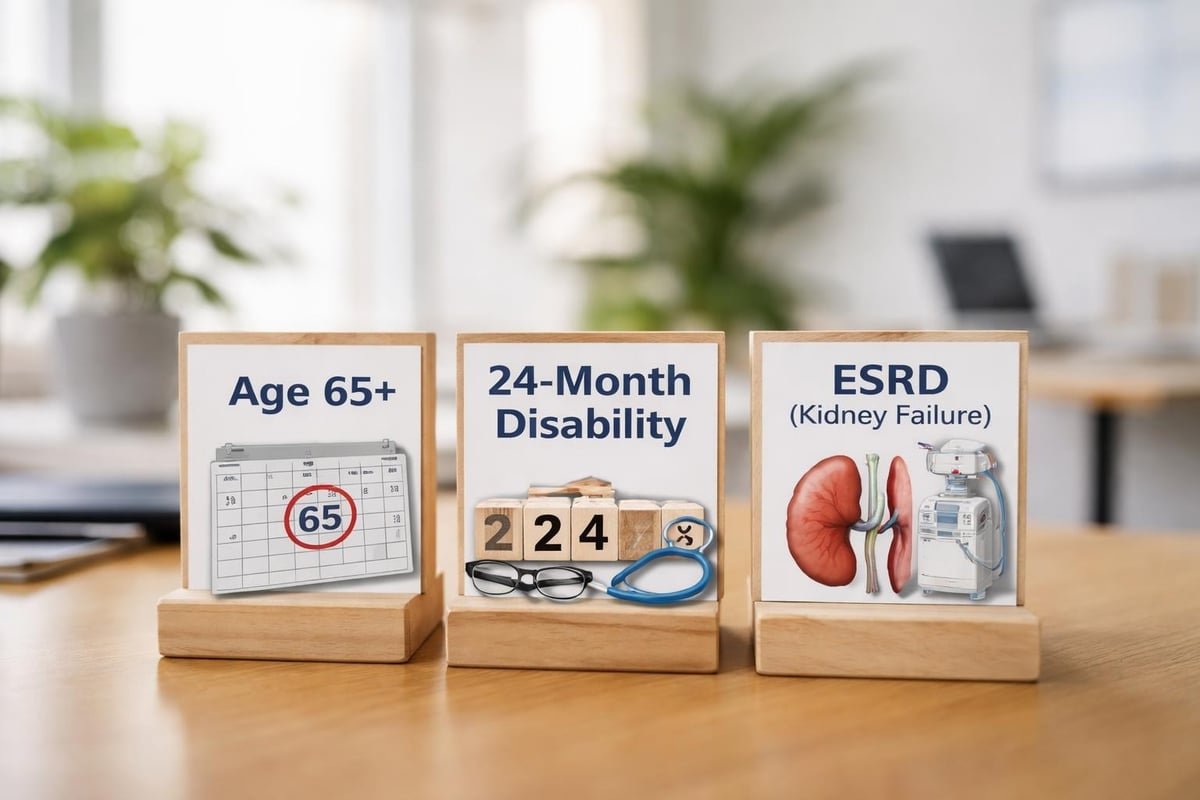
The standard age to qualify for Medicare is 65 years old. This has been the benchmark since the program's creation in 1965, and it remains consistent regardless of whether you're still working or already retired. Most Americans become eligible for Medicare on the first day of the month they turn 65, with one exception: if your birthday falls on the first of the month, your eligibility begins on the first day of the preceding month.
Understanding the enrollment periods and deadlines outlined by the Centers for Medicare & Medicaid Services is crucial for avoiding coverage gaps. The Initial Enrollment Period (IEP) begins three months before your 65th birthday month, includes your birthday month, and extends three months after. This gives you a seven-month window to enroll without penalty.
Why Age 65 Became the Standard
The age of 65 was established when Medicare was created, aligning with the full retirement age for Social Security benefits at that time. While Social Security's full retirement age has gradually increased to 67 for those born in 1960 or later, the age to qualify for Medicare has remained at 65. This means Medicare eligibility and full Social Security retirement age are now separate considerations for most Americans.
It's worth noting that you can claim Social Security benefits as early as age 62, but this doesn't affect your Medicare eligibility. The relationship between Social Security claiming age and Medicare is often misunderstood, but they operate independently in terms of eligibility requirements.
Exceptions to the Age 65 Requirement
Not everyone needs to wait until age 65 to access Medicare coverage. Several important exceptions allow certain individuals to qualify earlier based on specific health conditions or circumstances.
Disability-Based Eligibility
If you receive Social Security Disability Insurance (SSDI) or Railroad Retirement Board disability benefits for 24 consecutive months, you automatically qualify for Medicare regardless of your age. This means someone in their 40s or 50s could become Medicare-eligible if they meet the disability criteria.
The 24-month waiting period begins with your first month of disability benefit eligibility, not when you applied. After completing this waiting period, Medicare coverage starts automatically. For residents in Winston Salem, Greensboro, and throughout the Triad Area dealing with long-term disabilities, understanding this pathway is essential for planning healthcare coverage.
End-Stage Renal Disease (ESRD)
Individuals diagnosed with End-Stage Renal Disease requiring regular dialysis or a kidney transplant can qualify for Medicare at any age. Unlike disability-based eligibility, ESRD coverage typically begins immediately or within three months of starting dialysis treatments, depending on specific circumstances.
There's usually a three-month waiting period from the start of dialysis before Medicare coverage begins, but this can be waived if you participate in a home dialysis training program. For kidney transplant recipients, coverage continues for 36 months after a successful transplant.
Amyotrophic Lateral Sclerosis (ALS)
People diagnosed with ALS, also known as Lou Gehrig's disease, receive immediate Medicare eligibility upon approval for SSDI benefits. There's no 24-month waiting period for ALS patients, recognizing the aggressive nature of this condition and the immediate need for comprehensive healthcare coverage.
Medicare Enrollment Periods You Need to Know
Understanding when you can enroll is just as important as knowing the age to qualify for Medicare. Missing your enrollment window can result in permanent late enrollment penalties that increase your monthly premiums.
Initial Enrollment Period (IEP)
Your IEP is your first opportunity to enroll in Medicare and spans seven months:
- Three months before your 65th birthday month
- Your birthday month
- Three months after your birthday month
When you enroll during your IEP determines when your coverage begins. Enrolling during the three months before your birthday month ensures coverage starts on your birthday (or the first of the preceding month if you're born on the first). For individuals turning 65 in 2026, planning ahead ensures seamless coverage without gaps.
| Enrollment Timing | Part A Start Date | Part B Start Date |
|---|---|---|
| 3 months before birthday | First of birthday month | First of birthday month |
| During birthday month | First of following month | First of following month |
| Month after birthday | First of month after enrollment | First of month after enrollment |
| 2-3 months after birthday | 2-3 months after enrollment | 2-3 months after enrollment |
General Enrollment Period (GEP)
If you miss your IEP, the General Enrollment Period runs from January 1 through March 31 each year. Coverage begins July 1. However, enrolling during GEP typically means you'll face late enrollment penalties for Part B and potentially Part A if you're not eligible for premium-free Part A.
Special Enrollment Periods (SEP)
Several circumstances trigger Special Enrollment Periods that allow you to enroll outside the standard timeframes without penalty:
- You or your spouse are still working and covered by employer group health insurance
- You lose employer coverage
- You move outside your plan's service area
- You qualify for Extra Help with prescription drug costs
- You're in a disaster area
For those in High Point, Kernersville, or other Triad Area communities working past 65 with employer coverage, understanding SEP rules prevents costly mistakes.
Working Past Age 65: What You Need to Know
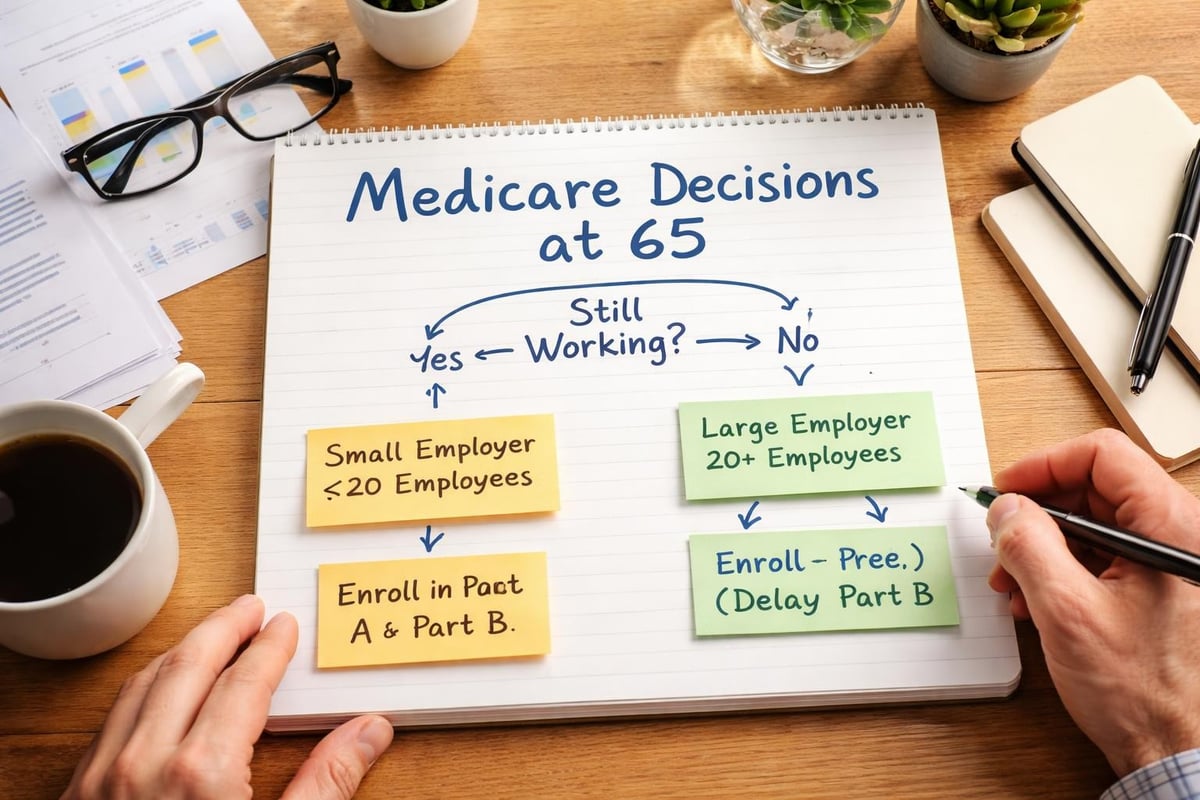
Many Americans continue working past the traditional age to qualify for Medicare. If you or your spouse have employer-based health insurance through a company with 20 or more employees, you can delay enrolling in Medicare Part B without penalty.
However, you should still enroll in Part A if you're eligible for premium-free coverage, as there's no cost and it can work alongside your employer plan. Part B enrollment can wait until you lose employer coverage, at which point you'll have an eight-month Special Enrollment Period.
Coordination with Employer Coverage
Understanding which insurance pays first matters significantly. For employers with 20 or more employees, the employer plan is primary and Medicare is secondary. For smaller employers (fewer than 20 employees), Medicare becomes primary, making it essential to enroll even while working.
If you're unsure about your situation in Greensboro, Winston Salem, or surrounding areas, consulting with a local Medicare expert can clarify your options. Contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com for personalized guidance.
Medicare Parts Explained
Once you reach the age to qualify for Medicare, you'll need to understand the different parts of coverage available. Each component serves a specific purpose in your overall healthcare strategy.
Part A: Hospital Insurance
Part A covers:
- Inpatient hospital stays
- Skilled nursing facility care
- Hospice care
- Some home healthcare services
Most people qualify for premium-free Part A based on their work history or their spouse's work history. You need 40 quarters (10 years) of Medicare-taxed employment to receive premium-free Part A.
Part B: Medical Insurance
Part B covers:
- Doctor visits and outpatient care
- Preventive services
- Medical equipment
- Some home healthcare
Unlike Part A, Part B requires a monthly premium. For 2026, the standard Part B premium is income-dependent, with higher earners paying more through Income-Related Monthly Adjustment Amounts (IRMAA).
Part C: Medicare Advantage
Medicare Advantage plans are offered by private insurance companies approved by Medicare. These plans combine Part A and Part B coverage, often including prescription drug coverage and additional benefits like dental, vision, and hearing. Reviewing the top Medicare Advantage plans available in your area helps identify which options best meet your needs.
Part D: Prescription Drug Coverage
Medicare Part D plans provide prescription drug coverage through private insurers. If you don't enroll in Part D when first eligible and don't have creditable prescription coverage, you'll face a late enrollment penalty that continues for as long as you have Part D coverage.
What Medicare Doesn't Cover
Understanding what Medicare does not cover is critical for comprehensive healthcare planning. Original Medicare doesn't include:
- Routine dental care
- Eye exams related to prescribing glasses
- Dentures
- Cosmetic surgery
- Acupuncture (with limited exceptions)
- Hearing aids and exams for fitting them
- Long-term custodial care
Many beneficiaries purchase Medicare Supplement (Medigap) policies or choose Medicare Advantage plans to address these coverage gaps. For personalized recommendations based on your healthcare needs in the Triad Area, working with an experienced broker makes the process much simpler.
Costs Associated with Medicare
While the age to qualify for Medicare is straightforward, understanding the costs requires careful attention. Medicare isn't free, even though Part A is premium-free for most beneficiaries.
2026 Medicare Costs Overview
| Medicare Part | Premium | Deductible | Additional Costs |
|---|---|---|---|
| Part A | $0 (most people) | $1,676 per benefit period | Coinsurance for extended stays |
| Part B | Starts at $185/month | $257 annually | 20% coinsurance for most services |
| Part D | Varies by plan | Varies by plan | Coverage gap considerations |
| Medigap | Varies by plan/insurer | Depends on Part A/B | Standardized plan options |
Income affects your Part B and Part D premiums through IRMAA surcharges. If your modified adjusted gross income exceeds certain thresholds, you'll pay additional premium amounts.
Late Enrollment Penalties
Missing your enrollment deadline creates permanent penalties in most cases:
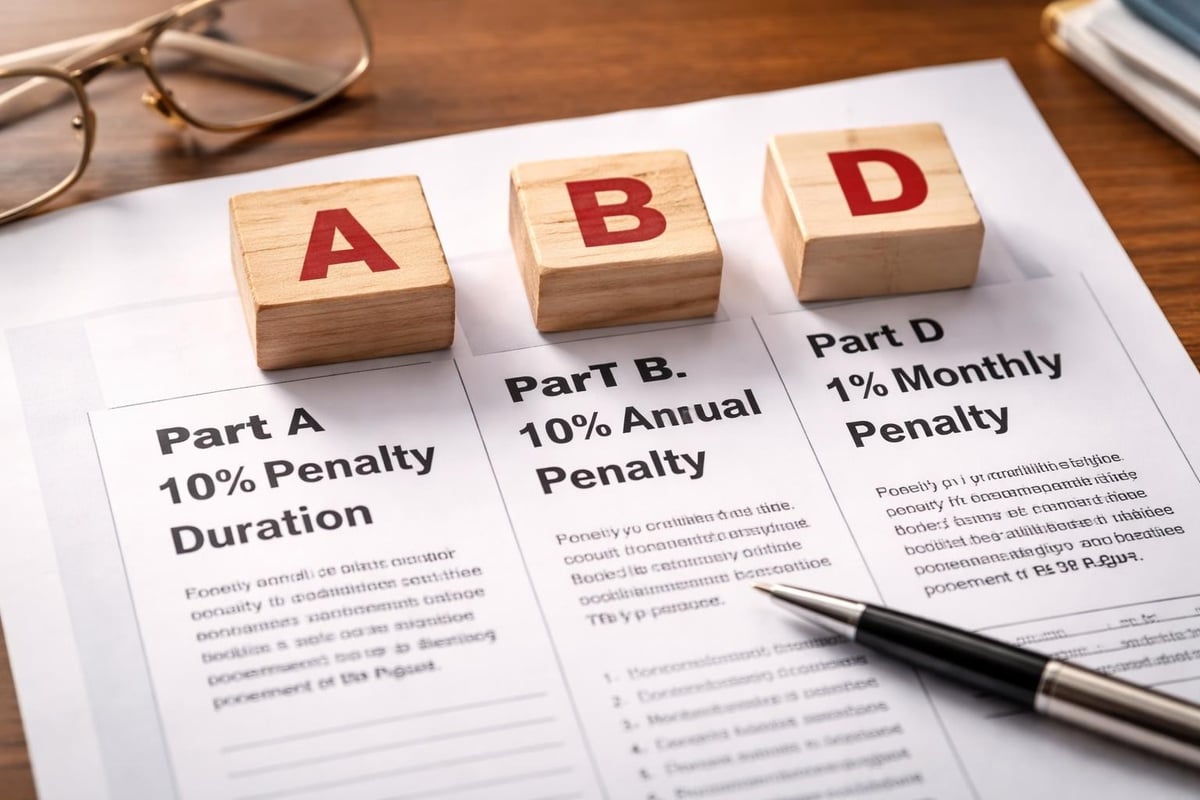
Part A Penalty: If you're not eligible for premium-free Part A and don't buy it when first eligible, your monthly premium may increase by 10%. You'll pay this higher premium for twice the number of years you could have had Part A but didn't sign up.
Part B Penalty: Your monthly premium increases by 10% for each full 12-month period you were eligible but didn't enroll. This penalty continues for as long as you have Part B coverage.
Part D Penalty: The penalty is 1% of the national base beneficiary premium multiplied by the number of months you went without creditable coverage. This penalty is permanent and added to your monthly Part D premium.
How to Enroll in Medicare
Enrollment processes vary depending on your circumstances. Understanding the basics of Medicare enrollment helps you navigate the system efficiently.
Automatic Enrollment
If you're already receiving Social Security or Railroad Retirement Board benefits when you turn 65, you'll be automatically enrolled in Medicare Parts A and B. You'll receive your Medicare card in the mail about three months before your 65th birthday.
If you don't want Part B (perhaps because you have employer coverage), you must decline it when you receive your card. Otherwise, your Part B premiums will be deducted from your Social Security payments.
Manual Enrollment
If you're not receiving Social Security benefits, you need to enroll manually. You can enroll:
- Online at the Social Security website
- By phone at 1-800-772-1213
- In person at your local Social Security office
For Triad Area residents in Greensboro, Winston Salem, High Point, or Kernersville, planning your enrollment strategy based on your work status and healthcare needs ensures optimal coverage without unnecessary costs.
Medicare Eligibility Beyond Age: Other Important Factors
While age is the primary qualifier, understanding complete Medicare eligibility requirements includes citizenship and residency considerations.
Citizenship and Residency Requirements
To qualify for Medicare, you must be:
- A U.S. citizen, or
- A legal permanent resident who has lived in the United States continuously for at least five years
You must also reside in the United States. Simply meeting the age to qualify for Medicare isn't sufficient if you don't meet these additional requirements.
Work History Requirements
For premium-free Part A, you or your spouse must have worked and paid Medicare taxes for at least 10 years (40 quarters). If you don't meet this requirement, you can still purchase Part A, but you'll pay monthly premiums.
Those with 30-39 quarters of Medicare-covered employment pay reduced Part A premiums. Those with fewer than 30 quarters pay the full premium.
Planning Ahead: What to Do Before You Turn 65
Preparation makes the Medicare transition smoother. Starting your planning six months before your 65th birthday gives you time to:
- Review your current health insurance coverage and how it coordinates with Medicare
- Determine whether you'll continue working and if employer coverage is creditable
- Research Medicare Advantage and Part D plans available in your area
- Consider whether Medigap coverage makes sense for your situation
- Calculate your expected healthcare costs under different coverage scenarios
For individuals approaching the age to qualify for Medicare in areas like Winston Salem, High Point, Greensboro, and Kernersville, connecting with local experts provides valuable insights into plan availability and pricing specific to North Carolina.
Visit moserinsurancegroup.com or call 336-862-1763 to schedule a consultation. You can also email questions to moserinsurancegroup@gmail.com for personalized guidance based on your unique situation.
Common Medicare Eligibility Mistakes to Avoid
Understanding the age to qualify for Medicare is just the beginning. Many people make costly errors during the enrollment process:
Assuming Medicare is Free: While Part A is premium-free for most people, Part B requires monthly premiums, and out-of-pocket costs can be substantial without supplemental coverage.
Missing Enrollment Deadlines: Late enrollment penalties are permanent in most cases and can significantly increase your lifetime healthcare costs.
Not Coordinating with Employer Coverage: Failing to understand how Medicare works with employer insurance can lead to coverage gaps or unnecessary duplicate coverage.
Ignoring Part D: Even if you don't currently take prescription medications, enrolling in Part D when first eligible avoids future penalties. Creditable coverage from employer plans can delay enrollment, but you must maintain that coverage without gaps.
Choosing Plans Without Research: Medicare coverage options vary significantly by location and provider. Comparing plans ensures you select coverage that matches your healthcare needs and budget.
Medicare Resources and Support
Navigating Medicare can feel overwhelming, but numerous resources exist to help:
- State Health Insurance Assistance Programs (SHIP): Free, unbiased Medicare counseling
- Medicare.gov Plan Finder: Compare plans available in your ZIP code
- Social Security Administration: Enrollment assistance and benefit coordination
- Local Medicare Brokers: Personalized guidance based on your specific needs
For residents throughout the Triad Area, Moser Insurance Group Inc provides clear guidance and personalized support to help you understand your Medicare options without pressure. Whether you're in Greensboro, Winston Salem, Kernersville, or High Point, working with a local expert who understands regional plan options and healthcare providers makes decision-making easier.
Medicare and Other Government Programs
Understanding how Medicare interacts with other programs helps maximize your benefits:
Medicare and Social Security
While closely related, Medicare and Social Security have different eligibility requirements and functions. You can claim Social Security as early as 62, but the age to qualify for Medicare remains 65 regardless of when you start Social Security benefits.
Medicaid and Medicare
Some individuals qualify for both programs, known as "dual eligibility." Medicaid can help pay Medicare premiums, deductibles, and coinsurance for those who meet income and resource requirements. Programs vary by state, so checking North Carolina-specific Medicaid programs is important.
Medicare Savings Programs
Medicare Savings Programs help people with limited income and resources pay Medicare costs. These state-run programs can cover Part A and Part B premiums, deductibles, and coinsurance.
Special Considerations for Different Situations
Every person's Medicare journey is unique based on their circumstances:
Working Past 65
If you're still working at age 65 with employer-based health insurance, coordinate your coverage carefully. Determine whether your employer plan is primary or secondary to Medicare based on company size, and decide whether to delay Part B enrollment.
Retiring Before 65
If you retire before reaching the age to qualify for Medicare, you'll need bridge coverage until Medicare eligibility begins. Options include COBRA, spouse's employer plan, private insurance, or marketplace plans. Planning this transition prevents coverage gaps.
Moving or Traveling
Medicare coverage works throughout the United States, but Medicare Advantage plans typically have network restrictions. If you spend significant time in multiple locations, Original Medicare with a Medigap plan often provides more flexibility than Medicare Advantage.
Understanding the age to qualify for Medicare and the enrollment rules surrounding it empowers you to make informed healthcare decisions as you approach 65. Whether you qualify at the standard age or through disability or ESRD exceptions, knowing your options and deadlines prevents costly mistakes. For personalized guidance tailored to your situation in Greensboro, Winston Salem, High Point, Kernersville, or throughout the Triad Area, Moser Insurance Group Inc helps individuals and families navigate Medicare options with clear explanations and supportive, pressure-free advice. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your Medicare planning needs and make confident insurance decisions.
Recent Comments