
Choosing the right healthcare coverage as you approach or enter retirement represents one of the most important financial decisions you'll make. For many seniors in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, an advantage plan for Medicare offers a compelling alternative to traditional Medicare coverage. These plans bundle hospital insurance, medical insurance, and often prescription drug coverage into a single, comprehensive package administered by private insurance companies approved by Medicare. Understanding how these plans work, what they cover, and whether they align with your healthcare needs can help you make an informed decision during enrollment periods.
What Is an Advantage Plan for Medicare
Medicare Advantage, also known as Medicare Part C, provides an alternative way to receive your Medicare benefits. Instead of getting coverage directly from the federal government through Original Medicare (Parts A and B), you receive all your Medicare benefits through a private insurance company that contracts with Medicare.
These private plans must cover everything Original Medicare covers, but they often include additional benefits that traditional Medicare doesn't provide. Most Medicare Advantage plans include prescription drug coverage, eliminating the need to purchase a separate Part D plan. Many also offer dental, vision, and hearing coverage-services that Original Medicare typically doesn't include.
The fundamental difference lies in how you access care. While Original Medicare allows you to see any doctor or specialist who accepts Medicare nationwide, Medicare Advantage plans typically operate within specific network structures. You'll generally need to use doctors and hospitals within the plan's network to receive the highest level of coverage, though exact rules vary by plan type.
How Medicare Advantage Plans Differ from Traditional Medicare
Understanding the key differences between Medicare Advantage and traditional Medicare helps you evaluate which option better suits your lifestyle and healthcare needs.
| Feature | Medicare Advantage | Original Medicare |
|---|---|---|
| Coverage Source | Private insurance company | Federal government |
| Provider Network | Usually required | Any Medicare-accepting provider |
| Out-of-Pocket Maximum | Yes, capped annually | No limit |
| Prescription Drugs | Often included | Requires separate Part D |
| Extra Benefits | Dental, vision, hearing common | Not typically included |
| Referrals | May be required | Not required |
Medicare Advantage plans often feature lower monthly premiums than the combined cost of Original Medicare with a Part D prescription drug plan and a Medigap supplement. However, you'll need to consider the total cost picture, including deductibles, copayments, and coinsurance when using healthcare services.
Types of Medicare Advantage Plans Available
The marketplace offers several distinct types of Medicare Advantage plans, each with different rules about how you access care and what you'll pay out of pocket.
Health Maintenance Organization Plans
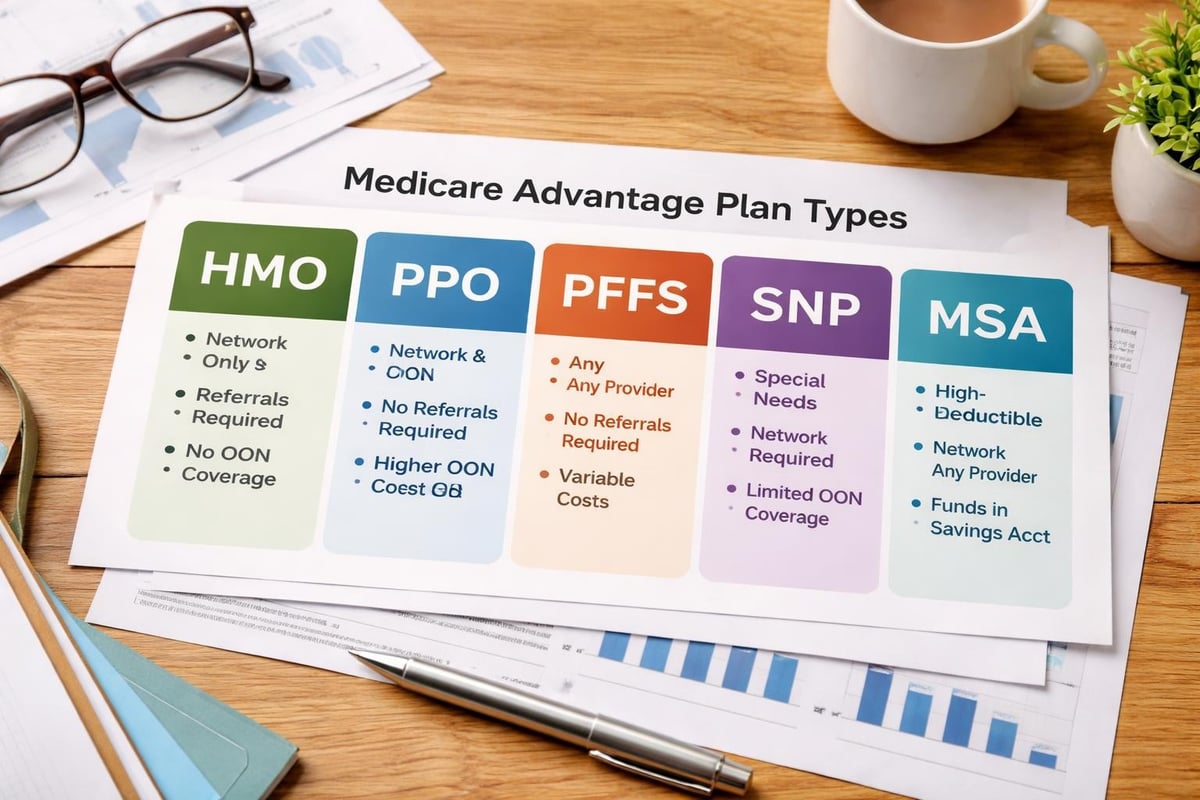
HMO plans represent the most common type of advantage plan for Medicare. These plans require you to select a primary care physician who coordinates all your care and provides referrals to specialists within the network. You must use network providers except in emergency situations.
HMO plans typically offer:
- Lower monthly premiums
- Predictable copayments
- Comprehensive care coordination
- Limited out-of-network coverage
Preferred Provider Organization Plans
PPO plans provide more flexibility in choosing healthcare providers. You can see any doctor who accepts Medicare, though you'll pay less when using in-network providers. Unlike HMOs, PPO plans don't require referrals to see specialists.
The trade-off for this flexibility usually includes:
- Higher monthly premiums
- More complex cost-sharing structures
- Freedom to see out-of-network providers
- No primary care physician requirement
Private Fee-for-Service Plans
PFFS plans determine how much they'll pay healthcare providers and how much you'll pay when you receive care. You can see any Medicare-approved provider who accepts the plan's payment terms and agrees to treat you, without network restrictions in most cases.
Special Needs Plans
Special Needs Plans (SNPs) target specific groups of Medicare beneficiaries, including those with chronic conditions, those who qualify for both Medicare and Medicaid, or those living in nursing homes. These plans tailor benefits, provider networks, and drug formularies to meet the unique needs of their target populations.
Medical Savings Account Plans
MSA plans combine a high-deductible insurance plan with a medical savings account. Medicare deposits money into your account, which you can use to pay for healthcare services before meeting your deductible.
Coverage and Benefits Details
An advantage plan for Medicare must cover all services that Original Medicare covers, including hospital stays, doctor visits, preventive care, and skilled nursing facility care. Beyond these mandatory benefits, plans frequently add valuable extras that can significantly enhance your healthcare coverage.
Prescription drug coverage stands as one of the most valuable additions. Rather than purchasing a separate Part D plan, most Medicare Advantage plans integrate drug coverage directly into the plan. This simplification means one premium, one deductible, and one insurance card for medical and prescription needs.
Additional benefits commonly included:
- Routine dental cleanings and examinations
- Annual eye exams and eyewear allowances
- Hearing tests and hearing aid coverage
- Over-the-counter medication allowances
- Fitness memberships and wellness programs
- Transportation to medical appointments
- Telehealth services beyond what Original Medicare covers
Some plans even offer meal delivery after hospital stays, in-home support services, or chronic condition management programs. These extras can provide substantial value, particularly for seniors managing multiple health conditions or living on fixed incomes in areas like Winston Salem and High Point.
Understanding Out-of-Pocket Costs
While Medicare Advantage plans often feature attractive premiums, you'll pay various costs when using healthcare services. For 2026, federal regulations require Medicare Advantage plans to cap your annual out-of-pocket spending for services covered under Parts A and B, providing financial protection that Original Medicare lacks.
Common cost-sharing structures include:
Copayments: Fixed amounts you pay for specific services, such as $20 for a primary care visit or $50 for a specialist appointment.
Coinsurance: A percentage of the service cost, typically ranging from 10% to 20% of Medicare-approved amounts.
Deductibles: The amount you pay before the plan starts covering services, which varies significantly between plans.
According to projected Medicare costs for 2025 and beyond, understanding these cost structures helps you budget for healthcare expenses throughout the year.
Enrollment Periods and Eligibility Requirements
Knowing when you can enroll in an advantage plan for Medicare ensures you don't miss critical opportunities to obtain or change coverage. Medicare establishes specific enrollment windows throughout the year, each with different rules and purposes.
Initial Enrollment Period
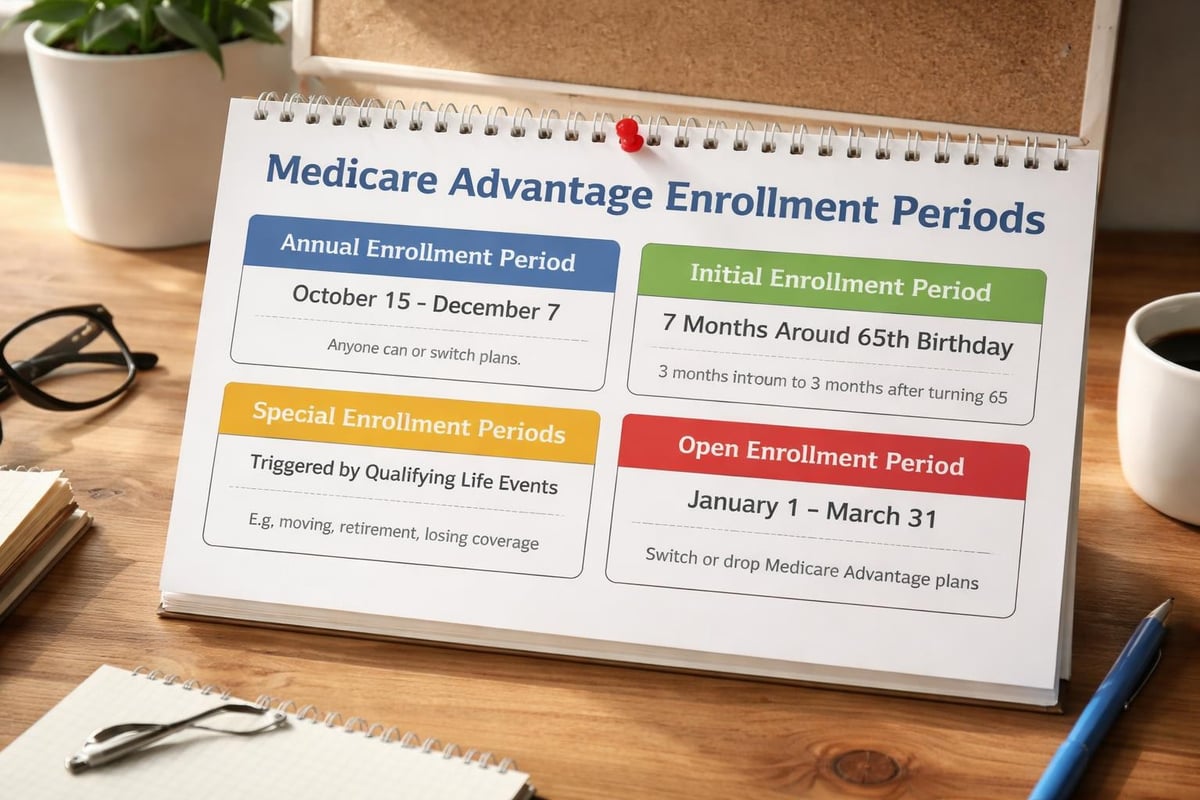
When you first become eligible for Medicare at age 65, you receive a seven-month Initial Enrollment Period. This window includes the three months before your birthday month, your birthday month, and the three months after. During this time, you can choose Original Medicare or enroll in a Medicare Advantage plan.
Annual Enrollment Period
The Annual Enrollment Period runs from October 15 through December 7 each year. During these weeks, all Medicare beneficiaries can:
- Switch from Original Medicare to Medicare Advantage
- Change from one Medicare Advantage plan to another
- Return to Original Medicare from Medicare Advantage
- Join, drop, or switch Medicare prescription drug plans
Changes made during this period take effect January 1 of the following year. This represents the primary opportunity for most people to modify their Medicare coverage annually.
Medicare Advantage Open Enrollment Period
From January 1 through March 31, current Medicare Advantage enrollees get one chance to switch to a different Medicare Advantage plan or return to Original Medicare and join a Part D prescription drug plan. You can make only one change during this period.
Special Enrollment Periods
Certain life events trigger Special Enrollment Periods that allow you to change coverage outside regular enrollment windows:
- Moving outside your plan's service area
- Losing other health coverage
- Moving into or out of a nursing home
- Qualifying for Medicaid
- Moving back to the United States after living abroad
If you're new to Medicare, understanding these enrollment periods prevents gaps in coverage and ensures you secure the right plan when you need it.
Choosing the Right Medicare Advantage Plan
Selecting an advantage plan for Medicare requires careful evaluation of your current health status, anticipated medical needs, and financial situation. The right plan for your neighbor might not suit your circumstances, making personalized research essential.
Assess Your Healthcare Needs
Start by documenting your current healthcare usage:
- List your current medications and research which plans cover them on their formularies
- Identify your preferred doctors and specialists to confirm they participate in plan networks
- Estimate your annual healthcare utilization, including routine visits, specialist care, and procedures
- Consider your budget for premiums, deductibles, and out-of-pocket maximums
- Evaluate additional benefits that would improve your quality of life
Compare Plan Networks and Providers
Network adequacy significantly impacts your satisfaction with an advantage plan for Medicare. Before enrolling, verify that your current doctors, specialists, and hospitals participate in the plan's network. If you frequently travel or spend time in multiple locations, consider how the plan covers care outside your primary service area.
In the Triad Area, plan networks can vary substantially between Greensboro, Kernersville, High Point, and Winston Salem, even though these communities sit close together geographically. A plan with excellent provider coverage in one city might have limited options in another.
Review Prescription Drug Coverage
Each Medicare Advantage plan maintains a formulary-a list of covered prescription drugs organized into tiers. Your medications' tier placement directly affects your out-of-pocket costs.
| Tier | Typical Drug Types | Cost-Sharing |
|---|---|---|
| Tier 1 | Preferred generic drugs | Lowest copay |
| Tier 2 | Generic drugs | Low copay |
| Tier 3 | Preferred brand drugs | Medium copay |
| Tier 4 | Non-preferred drugs | Higher copay |
| Tier 5 | Specialty drugs | Highest cost-sharing |
Some medications require prior authorization or step therapy, where you must try less expensive alternatives before the plan covers your prescribed medication. Understanding these requirements prevents surprise costs when filling prescriptions.
Examine Plan Ratings and Quality Measures
Medicare evaluates plans annually using a five-star rating system that considers:
- Health screenings and preventive services
- Managing chronic conditions
- Plan responsiveness and member satisfaction
- Customer service quality
- Complaints and appeals data
Plans receiving four or more stars demonstrate superior performance across these categories. You can review comprehensive Medicare Advantage plan information including ratings, costs, and coverage details through official Medicare resources.
Financial Considerations and Cost Analysis
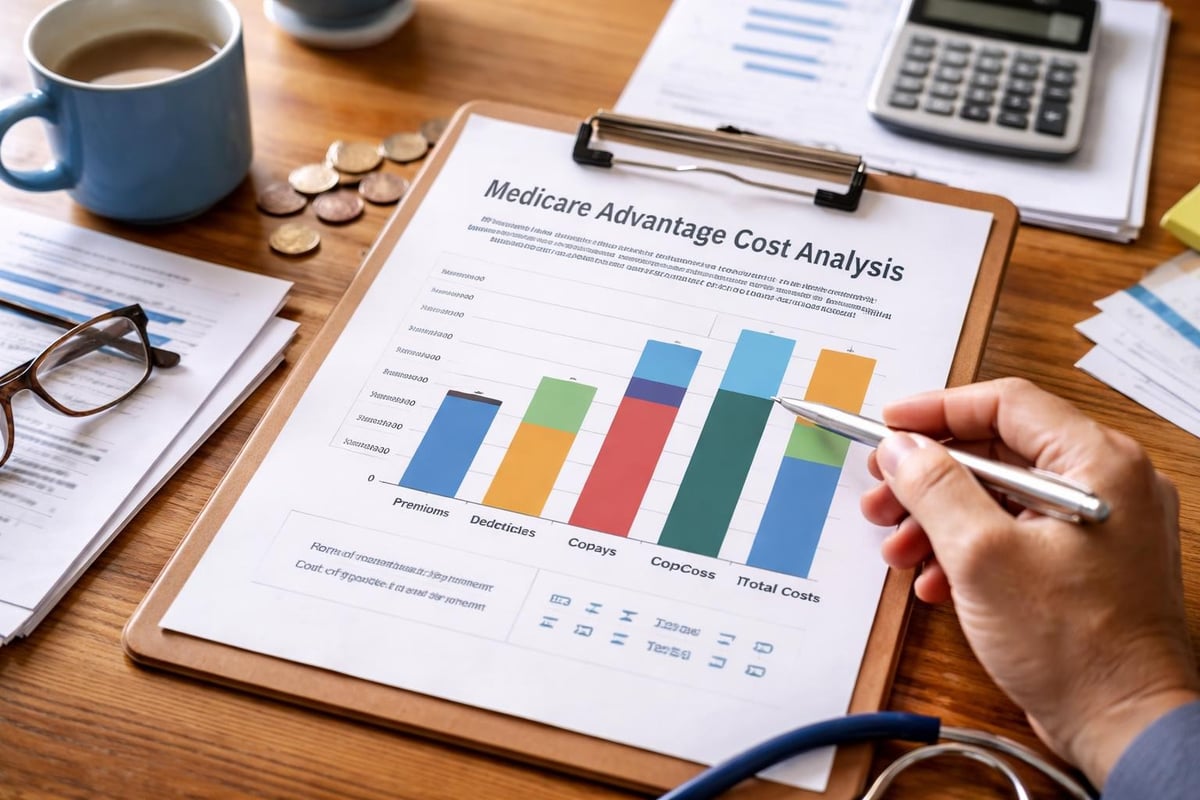
While an advantage plan for Medicare might advertise a $0 premium, comprehensive cost analysis requires examining the complete financial picture. Total healthcare spending includes multiple components that vary based on how much care you use throughout the year.
Premium Costs in Context
Medicare Advantage plan premiums represent just one piece of your total Medicare costs. You'll continue paying your Part B premium (unless you qualify for assistance programs), plus your plan's additional premium if applicable. Some plans charge no additional premium beyond Part B, while others add monthly costs ranging from under $50 to over $200.
Low premiums don't automatically translate to lower total costs. Plans with minimal monthly premiums often feature higher copayments, larger deductibles, or more restricted networks. Conversely, plans with higher premiums might offer broader networks, lower cost-sharing, and richer benefits.
Calculating Total Annual Costs
To accurately compare plans, project your total annual spending:
- Calculate annual premiums (Part B + plan premium × 12 months)
- Add your plan deductible
- Estimate copayments and coinsurance based on anticipated healthcare use
- Include prescription drug costs accounting for deductibles and tier placement
- Consider the out-of-pocket maximum as your worst-case scenario
This exercise reveals which plans deliver the best value for your specific situation. Someone requiring minimal healthcare might benefit from a low-premium, high-cost-sharing plan, while someone managing chronic conditions might save money overall with a higher-premium plan offering generous coverage.
Extra Help and Low-Income Benefits
If you have limited income and resources, you might qualify for Extra Help with prescription drug costs or Medicare Savings Programs that assist with premiums and cost-sharing. These programs significantly reduce your out-of-pocket expenses, making healthcare more affordable regardless of which type of advantage plan for Medicare you choose.
Eligibility thresholds change annually, and many eligible beneficiaries don't realize assistance is available. Checking your qualification status ensures you access all benefits you've earned.
Common Misconceptions About Medicare Advantage
Several persistent myths about Medicare Advantage plans create confusion during the decision-making process. Clearing up these misconceptions helps you evaluate options accurately.
Misconception: You can't return to Original Medicare once you choose Medicare Advantage.
Reality: You can switch back to Original Medicare during the Annual Enrollment Period or Medicare Advantage Open Enrollment Period. However, returning to Original Medicare might make purchasing Medigap supplemental insurance difficult or expensive due to medical underwriting requirements outside your Medigap open enrollment period.
Misconception: Medicare Advantage plans provide inferior coverage compared to Original Medicare.
Reality: Medicare Advantage plans must cover everything Original Medicare covers, often adding valuable extras. Coverage quality depends on the specific plan you choose and how well it aligns with your needs, not the coverage type itself.
Misconception: All Medicare Advantage plans are the same.
Reality: Significant variation exists between plan types, insurance companies, and specific offerings. Even two HMO plans in the same area can differ dramatically in networks, costs, and additional benefits. According to AARP’s Medicare Advantage FAQ, careful comparison shopping is essential.
Misconception: You must enroll in Medicare Advantage when you turn 65.
Reality: Choosing an advantage plan for Medicare remains optional. You can select Original Medicare with or without a Part D prescription drug plan and a Medigap supplement instead.
Regional Considerations for North Carolina Beneficiaries
Medicare Advantage plan availability and characteristics vary significantly by location. For residents of the Triad Area, understanding regional factors helps optimize your plan selection.
Plan Availability in the Triad
The Triad Area, encompassing Greensboro, Kernersville, High Point, and Winston Salem, enjoys robust Medicare Advantage plan competition. Multiple national and regional insurance carriers offer plans in this market, providing beneficiaries with substantial choice across HMO, PPO, and other plan types.
This competitive environment generally works to consumers' advantage, as insurance companies vie for enrollment by offering attractive benefit packages, competitive pricing, and comprehensive provider networks. The concentration of major healthcare systems in the region supports broad network coverage across most plans.
Provider Network Considerations
Major healthcare systems serving the Triad Area participate in many Medicare Advantage plan networks, but participation varies by plan and insurance carrier. Before enrolling, verify that your preferred hospitals, primary care physicians, and specialists accept your chosen plan.
Getting Local Assistance
Navigating Medicare options becomes easier with expert guidance. For personalized assistance understanding your choices, contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com. Working with a knowledgeable local agent who understands the Triad Area's healthcare landscape helps you identify plans that match your specific needs and budget.
Making Changes to Your Coverage
Your healthcare needs and circumstances change over time, making it important to review your advantage plan for Medicare regularly and adjust when necessary.
Annual Plan Review
Even if you're satisfied with your current coverage, annual review remains essential. Insurance companies can modify plan benefits, costs, provider networks, and prescription drug formularies each year. What worked well last year might not serve you as effectively in the coming year.
During each year's Annual Enrollment Period, evaluate:
- Changes to your current plan's benefits and costs
- Modifications to provider networks affecting your doctors
- Updates to prescription drug formularies
- New plans entering your market
- Your own health status and medication needs
When to Consider Switching Plans
Specific situations warrant serious consideration of switching your Medicare Advantage plan:
- Your doctor or hospital leaves your plan's network
- Your plan stops covering one or more of your medications
- You develop new health conditions requiring different specialists
- Your plan significantly increases costs or reduces benefits
- You move to a different area
- A new plan offers substantially better coverage for your needs
Understanding how Medicare Advantage works helps you recognize when your current plan no longer serves you well.
The Special Enrollment Period Advantage
Don't wait until the Annual Enrollment Period if you experience qualifying life events. Special Enrollment Periods allow immediate plan changes when you move, lose other coverage, or experience other qualifying circumstances. Acting promptly ensures continuous coverage without gaps.
Maximizing Your Medicare Advantage Benefits
Once enrolled in an advantage plan for Medicare, taking full advantage of your benefits optimizes the value you receive from your coverage.
Use Preventive Services
Medicare Advantage plans cover numerous preventive services at no cost to you, including:
- Annual wellness visits and personalized prevention plans
- Cardiovascular disease screenings
- Diabetes screenings and self-management training
- Cancer screenings (colorectal, breast, cervical, prostate)
- Bone mass measurements
- Vaccinations and immunizations
Regular use of these services helps detect health issues early when they're most treatable, potentially avoiding more serious and expensive problems later.
Leverage Extra Benefits
Many Medicare Advantage plans include benefits that Original Medicare doesn't cover. If your plan offers dental coverage, schedule regular cleanings. Use vision benefits for eye exams and glasses. Take advantage of fitness memberships to maintain your health. Access telehealth services for convenient care without traveling to appointments.
These extras represent real value that you've already paid for through your premiums. Failing to use them means leaving money on the table.
Understand Your Rights and Protections
Medicare Advantage enrollees maintain important rights and protections:
- Right to appeal: You can appeal plan decisions to deny, reduce, or stop services or prescription drug coverage
- Access to emergency care: Plans must cover emergency services anywhere in the United States
- Continuity of care: When your doctor leaves a plan network, you may receive temporary continued access
- Information access: Plans must provide clear information about coverage, costs, and rules
According to the Kaiser Family Foundation’s Medicare Advantage overview, knowing your rights ensures you receive the coverage you're entitled to under your plan.
Working with Insurance Professionals
Navigating Medicare choices alone can feel overwhelming, particularly as you approach Medicare eligibility for the first time or experience significant life changes. Professional guidance provides clarity and confidence in your decisions.
Benefits of Expert Assistance
Licensed insurance agents specializing in Medicare offer valuable expertise:
- Comprehensive plan comparisons tailored to your situation
- Network verification for your preferred providers
- Prescription drug coverage analysis
- Cost projections based on your healthcare usage
- Enrollment assistance and paperwork support
- Ongoing service for questions and coverage changes
Independent agents who represent multiple insurance carriers provide the broadest perspective, comparing options across different companies rather than limiting recommendations to a single carrier's products. This approach ensures you see the full range of choices available in your area, from priority health Medicare Advantage options to plans from other reputable carriers.
Questions to Ask Your Agent
When working with an insurance professional, ask questions that help you understand your options:
- Which plans include my doctors and hospitals in their networks?
- How do these plans cover my current medications?
- What are my total estimated annual costs under each plan?
- Which plans offer the additional benefits I value most?
- How do plan ratings compare for customer satisfaction and quality?
- What happens if I need care while traveling?
- Can I switch plans if my needs change?
Quality agents welcome these questions and provide clear, detailed answers that empower your decision-making.
The Future of Medicare Advantage
Medicare Advantage enrollment continues growing substantially, with nearly half of all Medicare beneficiaries now choosing these plans over Original Medicare. Understanding trends shaping the advantage plan for medicare marketplace helps you anticipate future changes.
Expanding Benefits and Innovation
Insurance companies increasingly add innovative benefits designed to address social determinants of health. Newer offerings include:
- Home-delivered meals following hospital discharge
- Non-emergency medical transportation
- Home safety modifications to prevent falls
- Pest control services
- Air conditioners for members with respiratory conditions
- Caregiver support programs
These benefits recognize that health outcomes depend on factors beyond traditional medical care. Plans that help members address food insecurity, transportation barriers, and unsafe living conditions may improve health while reducing costly hospitalizations.
Technology Integration
Telehealth services expanded dramatically during the COVID-19 pandemic and continue evolving. Many Medicare Advantage plans now offer:
- Virtual primary care visits
- Remote specialist consultations
- Digital mental health services
- Remote patient monitoring for chronic conditions
- Medication management through video appointments
Technology integration makes healthcare more accessible, particularly for beneficiaries in rural areas or those with mobility limitations.
Value-Based Care Models
Medicare Advantage plans increasingly emphasize care coordination and preventive services through value-based payment models. These approaches reward healthcare providers for keeping patients healthy rather than simply treating illness, potentially improving outcomes while controlling costs.
As these trends continue, beneficiaries can expect Medicare Advantage plans to offer increasingly comprehensive benefits that address broader aspects of health and wellness.
Choosing an advantage plan for Medicare represents a significant decision that affects your healthcare access, costs, and quality of life throughout your retirement years. By understanding how these plans work, comparing options carefully, and reassessing your coverage annually, you can optimize your Medicare benefits to match your evolving needs. Moser Insurance Group Inc helps individuals and families in the Triad Area navigate Medicare choices with personalized guidance and clear explanations. Whether you're approaching Medicare eligibility, considering a plan change, or simply have questions about your options in Greensboro, Kernersville, High Point, or Winston Salem, contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc for support you can trust.
Recent Comments