
Medicare beneficiaries often discover that Original Medicare doesn't cover all healthcare costs. Deductibles, copayments, and coinsurance can add up quickly, leaving many seniors searching for supplemental coverage. The aarp united healthcare medicare supplement partnership offers a solution that millions of Americans trust. This collaboration between AARP and UnitedHealthcare provides access to standardized Medigap plans designed to fill the gaps in Original Medicare coverage, offering financial predictability and peace of mind for beneficiaries across the country, including those in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem.
Understanding the AARP UnitedHealthcare Partnership
AARP doesn't provide insurance directly. Instead, the organization has partnered with UnitedHealthcare to offer Medicare Supplement insurance to its members. This relationship has existed for decades, making UnitedHealthcare the exclusive provider of AARP-branded Medigap policies.
The partnership combines AARP's advocacy for seniors with UnitedHealthcare's insurance infrastructure. When you purchase an aarp united healthcare medicare supplement plan, you're buying a UnitedHealthcare policy that's marketed under the AARP name. You must be an AARP member to enroll, though membership is relatively inexpensive and open to anyone age 50 or older.
Why This Partnership Matters
This collaboration has several advantages for beneficiaries:
- Brand recognition: Both organizations have established reputations in the senior market
- Extensive network: UnitedHealthcare's size means broad acceptance and resources
- Member benefits: AARP membership includes additional perks beyond insurance
- Customer service: Dedicated support teams familiar with Medicare beneficiaries' needs
According to AARP’s official Medicare Supplement page, these plans are available in most states and offer the full range of standardized Medigap options.
Available Medicare Supplement Plan Options
The aarp united healthcare medicare supplement lineup includes most of the standardized Medigap plans designated by letters. Each plan offers identical coverage regardless of which insurance company sells it, though premiums vary by insurer.
Most Popular Plan Choices
| Plan Type | Coverage Level | Best For |
|---|---|---|
| Plan G | Comprehensive (except Part B deductible) | Most new Medicare beneficiaries |
| Plan N | Moderate coverage with copays | Budget-conscious enrollees |
| High Deductible Plan G | Full coverage after high deductible | Healthy individuals wanting lower premiums |
| Plan F* | Most comprehensive | Those eligible (enrolled before 2020) |
*Plan F is only available to those who became eligible for Medicare before January 1, 2020.
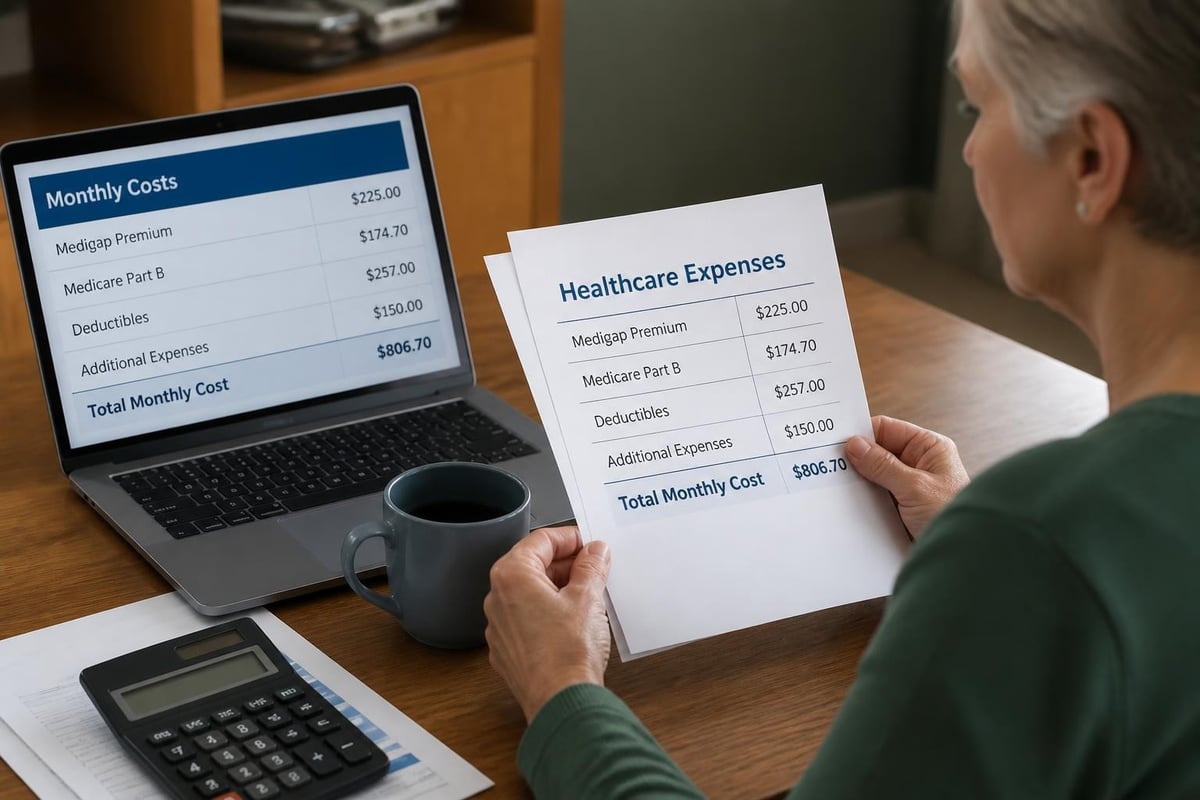
Plan G has become the most popular choice for new Medicare beneficiaries since 2020. It covers nearly everything except the Medicare Part B deductible, which is $257 in 2026. NerdWallet’s comprehensive review highlights Plan G as the best value for most enrollees.
Coverage Details Across Plans
Different aarp united healthcare medicare supplement plans cover varying percentages of Medicare's cost-sharing requirements. Understanding what each plan covers helps you match your healthcare needs with the right policy.
Plan G benefits include:
- Part A coinsurance and hospital costs up to 365 additional days
- Part B coinsurance or copayment
- First three pints of blood
- Part A hospice care coinsurance
- Skilled nursing facility coinsurance
- Part A deductible
- Foreign travel emergency coverage (up to plan limits)
Plan N offers similar benefits but requires copayments of up to $20 for office visits and $50 for emergency room visits (waived if admitted). This trade-off results in lower monthly premiums compared to Plan G.
Cost Considerations and Premium Factors
Premiums for an aarp united healthcare medicare supplement vary based on several factors. Understanding these variables helps you budget appropriately and compare options effectively.
Pricing Methods
UnitedHealthcare uses attained-age pricing in most states. This means your premium increases as you get older, independent of when you purchased the policy. Some key pricing considerations:
- Geographic location: Premiums differ significantly by ZIP code and state
- Age: Older beneficiaries typically pay higher premiums
- Tobacco use: Smokers may face surcharges in certain states
- Household discounts: Some states offer reduced rates when spouses both enroll
In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, premiums reflect regional healthcare costs and competition among insurers. Local factors influence pricing, making it essential to get personalized quotes.
Additional Costs Beyond Premiums
Beyond monthly premiums, beneficiaries should consider:
- Part B premium: $185.00 per month in 2026 (higher for high-income earners)
- Plan deductibles: Varies by plan type
- Out-of-pocket costs: What your specific plan doesn't cover
- Prescription drug coverage: Medigap doesn't include drug coverage; separate Part D needed
For personalized assistance understanding these costs, contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com.
Enrollment Periods and Guaranteed Issue Rights
Timing matters significantly when purchasing an aarp united healthcare medicare supplement. During certain periods, you have guaranteed issue rights, meaning insurance companies cannot deny coverage or charge higher rates due to health conditions.
Medicare Supplement Open Enrollment Period
Your six-month Medigap Open Enrollment Period begins the month you turn 65 AND are enrolled in Medicare Part B. During this window:
- Insurers cannot use medical underwriting to deny coverage
- You cannot be charged higher premiums due to health conditions
- You have access to any Medigap plan sold in your state
- Pre-existing conditions are covered immediately
Missing this enrollment period doesn't prevent you from buying coverage later, but insurers can require medical underwriting and potentially deny your application or charge higher premiums based on health status.
Special Guaranteed Issue Situations
Certain circumstances grant guaranteed issue rights outside the initial enrollment period:
- Losing employer-sponsored coverage through no fault of your own
- Moving out of a Medicare Advantage plan's service area
- Your Medicare Advantage plan leaving Medicare or stopping service in your area
- You were misled when purchasing your current coverage
Understanding Medicare Supplement enrollment rules helps you protect your rights and make informed decisions about when to apply.
Additional Benefits and Member Services
Beyond standard Medigap coverage, aarp united healthcare medicare supplement policyholders receive extra benefits and services. These value-added features distinguish the AARP program from other Medigap providers.
Wellness and Discount Programs
AARP membership includes access to various wellness programs:
- Renew Active: Gym memberships and fitness programs at no additional cost
- Health assessments: Personalized health reviews and screenings
- Health coaching: Telephonic support for chronic conditions
- Preventive care resources: Educational materials and tools
These programs support overall health management beyond just insurance coverage. While Medicare Supplement plans primarily focus on financial protection, these wellness benefits address preventive care and healthy living.
Customer Support and Resources
UnitedHealthcare provides dedicated support channels for AARP Medicare Supplement members:
| Support Type | Access Method | Availability |
|---|---|---|
| Phone support | Toll-free number | 24/7 assistance |
| Online portal | Member website | Anytime access |
| Mobile app | iOS and Android | On-the-go management |
| Local agents | In-person meetings | By appointment |
These resources help members navigate claims, understand coverage, and resolve issues quickly.
Comparing AARP Plans to Other Medigap Options
While aarp united healthcare medicare supplement plans are popular, they're not the only Medigap option available. Comparing different insurers helps ensure you're getting the best value for your specific situation.
What to Compare
When evaluating Medigap carriers:
- Premium costs: Get quotes from multiple insurers for the same plan letter
- Financial strength: Check AM Best ratings for insurer stability
- Customer service: Review satisfaction ratings and complaint data
- Additional benefits: Compare value-added programs and perks
- Rate increase history: Research how often and how much premiums have increased
MoneyGeek’s UnitedHealthcare review provides detailed analysis of the company's offerings, including strengths and potential drawbacks.
Standardization Means Apples-to-Apples Comparison
Because Medigap plans are standardized, Plan G from AARP UnitedHealthcare provides identical coverage to Plan G from any other insurer. The differences lie in:
- Monthly premium amounts
- Customer service quality
- Additional member benefits
- Company reputation and stability
This standardization simplifies comparison shopping. You can focus on price and service rather than trying to decode different coverage levels. Healthline’s Medicare Supplement comparison chart illustrates the standardized benefit structure across all insurers.
Application Process and Underwriting
Applying for an aarp united healthcare medicare supplement involves several steps. Understanding the process helps you prepare necessary documentation and avoid delays.
Step-by-Step Enrollment
The application process typically follows this sequence:
- Become an AARP member if you aren't already (required for enrollment)
- Determine your eligibility for guaranteed issue rights
- Compare available plans in your area and select the best fit
- Complete the application online, by phone, or with an agent
- Provide health information if outside guaranteed issue periods
- Submit payment for your first month's premium
- Receive policy documents and confirmation of coverage
Working with an experienced agent can streamline this process. At Moser Insurance Group Inc, we help clients throughout the Triad Area navigate applications efficiently. Visit moserinsurancegroup.com or call 336-862-1763 to start your enrollment.
Medical Underwriting Considerations
If you're applying outside your Medigap Open Enrollment Period and don't have guaranteed issue rights, you'll face medical underwriting. Insurers may ask about:
- Current prescription medications
- Recent doctor visits and diagnoses
- Chronic health conditions
- Planned surgeries or procedures
- Hospital admissions in the past 12 months
Some health conditions may result in higher premiums or coverage denial. However, each state has different rules, and some states offer additional protections. HelpAdvisor’s detailed coverage guide explains state-specific variations.
Network Flexibility and Provider Acceptance
One significant advantage of choosing an aarp united healthcare medicare supplement is provider flexibility. Unlike Medicare Advantage plans, Medigap policies work with any doctor or hospital that accepts Medicare.
No Network Restrictions
Medigap plans don't have networks. This means:
- You can see any provider who accepts Medicare
- No referrals needed for specialists
- No prior authorization requirements
- Coverage travels with you anywhere in the United States
This flexibility particularly benefits those who travel frequently, spend time in multiple states, or want access to specialized medical centers regardless of location.
How Provider Payment Works
When you have a Medicare Supplement:
- Medicare pays first: Your provider bills Medicare directly for covered services
- Medigap pays second: Your supplement automatically covers most remaining costs
- You pay last: You're responsible only for what Medicare and Medigap don't cover
This coordination of benefits happens automatically. You typically don't need to file claims or manage payments beyond showing your Medicare and Medigap cards.
For comparison, understanding how Medicare Advantage networks work highlights the differences between supplement and advantage plan structures.
Prescription Drug Coverage Considerations
An important limitation of aarp united healthcare medicare supplement plans is that they don't include prescription drug coverage. Medicare Part D addresses this gap separately.
Why You Need Part D
Medigap policies cover Medicare-approved services but exclude prescription medications. To avoid penalties and ensure drug coverage, most beneficiaries need:
- Standalone Part D plan: Purchased separately from any insurance company
- Creditable coverage: Through employer/union benefits or other qualified sources
- Low-income assistance: Extra help programs for those who qualify
The Part D late enrollment penalty applies if you go more than 63 days without creditable coverage after becoming eligible. This penalty continues for as long as you have Part D coverage.
Coordinating Supplement and Drug Coverage
Managing two separate policies (Medigap and Part D) requires attention to:
- Different premium payments and billing
- Separate deductibles and coverage rules
- Multiple insurance card management
- Coordination during the Part D coverage gap (donut hole)
While this seems complex, having separate policies provides flexibility. You can change Part D plans annually during Open Enrollment without affecting your Medicare Supplement coverage.
State-Specific Variations and Availability
While Medicare Supplement plans are federally standardized, states have some flexibility in regulating these policies. The aarp united healthcare medicare supplement program reflects these variations.
States With Different Rules
Massachusetts, Minnesota, and Wisconsin use their own standardized Medigap plans rather than the federal lettered system. These states offer different plan structures but similar overall benefits.
Some states provide additional protections, such as:
- Guaranteed issue rights during annual enrollment periods
- Birthday rules allowing plan changes
- Requirements that insurers offer specific plans
- Premium rating restrictions
Understanding your state's specific rules helps you maximize your enrollment opportunities and protections.
Availability Across the United States
AARP UnitedHealthcare offers Medicare Supplement plans in most states, with varying plan options depending on location. Not all plans are available in every state, and some states have unique offerings.
In North Carolina, including the Triad Area communities of Greensboro, Kernersville, High Point, and Winston Salem, beneficiaries have access to the full range of standardized Medigap plans. Local regulations and market competition influence premium rates and available discounts.
Household Discount Opportunities
Many carriers, including UnitedHealthcare, offer household discounts when multiple family members enroll in aarp united healthcare medicare supplement policies. These savings can reduce your overall insurance costs significantly.
Types of Household Discounts
Available discounts may include:
- Spousal discounts: Reduced rates when both spouses enroll
- Multi-policy discounts: Savings for having multiple policies with the same carrier
- Volume discounts: Reductions based on total household premium
Discount availability varies by state. Some states prohibit certain types of discounts, while others encourage them. Always ask about available discounts when comparing quotes.
Maximizing Your Savings
To get the best rates on Medicare Supplement coverage:
- Shop during your Open Enrollment Period when rates are guaranteed
- Compare multiple carriers for the same plan letter
- Ask about all available discounts including household, association, and loyalty programs
- Consider different plan types to find the right coverage-cost balance
- Review annually to ensure you're still getting competitive rates
Working with an independent agent who represents multiple carriers provides access to broader comparisons. For personalized assistance comparing options in the Greensboro, Kernersville, High Point, or Winston Salem areas, contact Moser Insurance Group Inc at moserinsurancegroup@gmail.com.
Claim Filing and Customer Service Experience
One practical consideration when choosing an aarp united healthcare medicare supplement is how claims are handled and what customer service experience you can expect.
Automated Claims Processing
Medicare Supplement claims typically process automatically through a system called crossover:
- Your healthcare provider bills Medicare first
- Medicare processes the claim and pays its portion
- Claim information automatically transfers to your Medigap insurer
- Your supplement pays its portion based on plan benefits
- You receive an Explanation of Benefits showing all payments
This automated process means you rarely need to file claims manually. However, understanding how to read your EOB statements helps you verify correct payment.
Customer Service Access Points
UnitedHealthcare provides multiple ways to access support:
- 24/7 phone assistance: Speak with representatives any time
- Online account management: View claims, download ID cards, check coverage
- Mobile app functionality: Access information on your smartphone
- Written correspondence: Mail for formal inquiries and documentation
- Local agent support: In-person guidance from licensed professionals
Customer satisfaction ratings provide insight into service quality. HelpAdvisor’s AARP plan review includes customer feedback and ratings based on actual member experiences.
Rate Increase History and Future Projections
While your initial premium is important, understanding how rates have increased over time helps you anticipate future costs with an aarp united healthcare medicare supplement policy.
Factors Affecting Rate Increases
Insurance companies adjust Medigap premiums based on:
- Medical inflation: Rising healthcare costs affect claim payments
- Aging: Attained-age pricing means premiums increase as you age
- Utilization rates: How often policyholders use their benefits
- Loss ratios: The percentage of premiums paid out in claims
- Regulatory changes: State-approved rate adjustments
All Medigap insurers face these pressures, making some rate increases inevitable across the industry.
Evaluating Historical Increases
When assessing an insurer's rate history:
| Evaluation Factor | What to Consider |
|---|---|
| Frequency | How often rates increase (annual, biennial) |
| Magnitude | Average percentage increase per adjustment |
| Consistency | Whether increases are predictable or erratic |
| Comparison | How increases compare to other carriers |
While past performance doesn't guarantee future results, a company's rate history provides useful context for long-term planning.
Switching Between Medicare Supplement Plans
Your aarp united healthcare medicare supplement choice isn't permanent. You can change plans, though the ease of switching depends on your circumstances and timing.
When You Can Switch
You have the right to apply for a different Medigap plan anytime. However, guaranteed issue rights (protection from medical underwriting) typically only apply during:
- Your initial six-month Medigap Open Enrollment Period
- Certain guaranteed issue situations (losing other coverage, plan discontinuation)
- State-specific enrollment periods (in states that offer them)
Outside these periods, you may face medical underwriting, which could result in coverage denial or higher premiums based on health status.
Reasons to Consider Switching
Common motivations for changing Medicare Supplement plans include:
- Premium reduction: Finding a better rate for the same coverage
- Plan change: Switching to a different plan letter (like Plan G to Plan N)
- Insurer change: Moving to a different company while keeping the same plan type
- Coverage adjustment: Changing coverage levels as healthcare needs evolve
Before switching, carefully evaluate whether potential savings justify the risk of medical underwriting if you're outside guaranteed issue periods. Healthline’s guide to Medigap policies provides helpful context for making switching decisions.
Comparing Supplement Plans to Medicare Advantage
Many Medicare beneficiaries wonder whether an aarp united healthcare medicare supplement or a Medicare Advantage plan better suits their needs. Understanding the fundamental differences helps clarify this decision.
Key Structural Differences
| Feature | Medicare Supplement | Medicare Advantage |
|---|---|---|
| Provider networks | No restrictions | HMO/PPO networks |
| Coverage | Supplements Original Medicare | Replaces Original Medicare |
| Drug coverage | Separate Part D needed | Often included |
| Premiums | Supplement + Part B + Part D | Plan premium + Part B |
| Out-of-pocket max | None required | Annual limit required |
| Travel coverage | Works nationwide | Limited outside service area |
These structural differences create very different coverage experiences. Medicare Supplement plans offer predictability and flexibility, while Medicare Advantage plans often provide additional benefits like dental and vision at lower premiums.
Choosing Based on Your Priorities
Consider a Medicare Supplement if you:
- Want freedom to see any Medicare provider
- Travel frequently or split time between states
- Prefer predictable costs with minimal surprises
- Have chronic conditions requiring specialist access
Consider Medicare Advantage if you:
- Want comprehensive coverage including extras
- Prefer lower monthly premiums
- Stay in one geographic area
- Are comfortable with network restrictions
For a detailed comparison of top Medicare Advantage plans, review options specific to your area and healthcare needs.
Choosing the right Medicare Supplement coverage requires understanding how aarp united healthcare medicare supplement plans work, what they cost, and how they fit your specific healthcare and financial situation. The standardized nature of Medigap policies simplifies comparison, but variables like premiums, customer service, and additional benefits still require careful evaluation. At Moser Insurance Group Inc, we help individuals and families throughout the Triad Area navigate Medicare options with personalized guidance and educational support. Whether you're in Greensboro, Kernersville, High Point, or Winston Salem, our team provides clear explanations without pressure, helping you make confident insurance decisions. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to explore your Medicare Supplement options today.
Recent Comments