

Financial protection isn't just about what happens after you're gone. It's also about ensuring you and your family can weather serious medical crises without financial devastation. Life insurance and critical illness cover represent two complementary protection strategies that address different but equally important scenarios: protecting your family's financial future and safeguarding your current financial stability during severe health events. Understanding how these coverages work individually and together helps you make informed decisions about your family's security, especially if you're exploring insurance options in the Greensboro, Kernersville, High Point, Winston Salem, or broader Triad Area.
Understanding Life Insurance Fundamentals
Life insurance provides a tax-free death benefit to your beneficiaries when you pass away. The primary purpose is income replacement-ensuring your spouse, children, or other dependents maintain their standard of living without your income. According to Insurance Information Institute statistics, approximately 52% of Americans owned some form of life insurance in 2024, though coverage gaps remain significant.
Types of Life Insurance Coverage
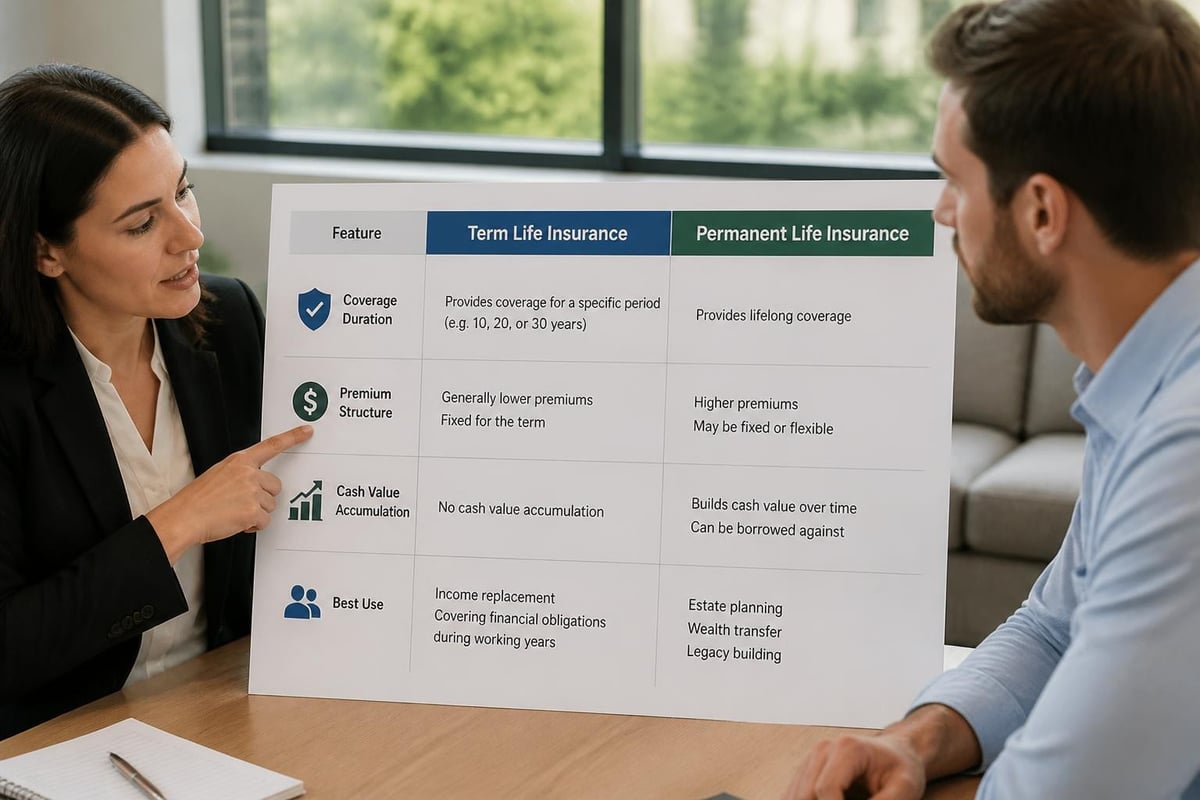
Term life insurance offers coverage for a specific period-typically 10, 20, or 30 years-at the most affordable premiums. If you're primarily concerned about replacing income during your working years while children are young or mortgage debt remains, term life insurance provides straightforward, cost-effective protection.
Permanent life insurance includes whole life and universal life policies that provide lifetime coverage with a cash value component. These policies cost more but offer additional financial planning benefits beyond pure death benefit protection.
Key features that distinguish life insurance products:
- Death benefit amount: The lump sum paid to beneficiaries (typically $100,000 to $1 million or more)
- Premium structure: Fixed or flexible payments
- Policy duration: Term (temporary) or permanent (lifetime)
- Cash value: Accumulation feature in permanent policies
- Conversion options: Ability to convert term to permanent coverage
How Life Insurance Underwriting Works
When you apply for coverage, insurers assess your risk through medical underwriting. The process examines your health history, current conditions, lifestyle factors (smoking, weight, occupation), and family medical history. NAIC’s consumer guidance explains that this underwriting determines your premium class and coverage eligibility.
The Consumer Financial Protection Bureau notes that specialty consumer reports (prescription drug histories, medical information bureaus) play an increasing role in underwriting decisions. Understanding how these reports affect your application helps you prepare appropriate documentation and explanations.
Most policies include a contestability period-typically two years-during which the insurer can investigate claims and potentially deny benefits if material misrepresentations are discovered on the application.
Critical Illness Insurance Explained
Critical illness insurance pays a lump-sum cash benefit directly to you upon diagnosis of a covered serious illness. Unlike traditional health insurance that pays providers, this benefit goes to the policyholder to use as needed-mortgage payments, experimental treatments, travel for specialized care, or simply replacing lost income during recovery.
Conditions Typically Covered
Standard critical illness policies cover major health events with significant financial impact:
- Heart attack: Myocardial infarction requiring hospitalization
- Stroke: Cerebrovascular accident with lasting neurological damage
- Cancer: Invasive cancers (exclusions often apply to early-stage or skin cancers)
- Organ failure: Kidney, liver, or heart requiring transplant
- Major organ transplant: As recipient
- Paralysis: Permanent loss of function in limbs
- Blindness or deafness: Permanent and irreversible sensory loss
- Coma: Requiring life support for specified duration
Research from the American Heart Association’s 2025 statistics update shows that cardiovascular disease remains the leading cause of death in America, with someone experiencing a heart attack every 40 seconds. National Cancer Institute data indicates nearly 2 million new cancer diagnoses occur annually. These statistics underscore why critical illness coverage addresses real, common risks.
How Critical Illness Payments Work
When diagnosed with a covered condition meeting policy definitions, you file a claim with medical documentation. Upon approval, the insurer pays the benefit amount-commonly $10,000 to $100,000 depending on coverage purchased.
| Aspect | Critical Illness Cover | Traditional Health Insurance |
|---|---|---|
| Pays whom | Policyholder directly | Healthcare providers |
| Trigger | Diagnosis of covered condition | Medical services rendered |
| Amount | Lump sum (fixed) | Percentage of costs (variable) |
| Use restrictions | None-any purpose | Must be qualified medical expenses |
| Coordination | Independent of other coverage | Primary/secondary coordination |
The flexibility matters enormously. You might use critical illness benefits to cover health insurance deductibles and copays, travel costs for treatment at specialized facilities, experimental therapies not covered by insurance, home modifications for disability accessibility, or simply household expenses while unable to work.
How Life Insurance and Critical Illness Cover Work Together
Life insurance and critical illness cover address different moments in your protection timeline. Life insurance activates after death; critical illness coverage provides resources while you're living through serious illness.
Complementary Protection Strategies
Many families combine both coverages for comprehensive protection. Consider a 45-year-old primary earner with mortgage debt and college-bound children. Term life insurance ensures the family maintains financial stability if the earner dies unexpectedly. Critical illness coverage addresses the immediate financial strain if that same earner survives a stroke but faces months of rehabilitation without income.
The Society of Actuaries research on life insurance pricing and product design increasingly shows insurers bundling these benefits. Some policies now include accelerated death benefits or living benefits that allow terminally ill policyholders to access a portion of the death benefit before death-blurring the traditional separation between life insurance and critical illness features.
Living Benefits and Accelerated Death Benefits
Modern life insurance policies frequently include riders or built-in provisions allowing access to death benefits before death in qualifying circumstances:
- Terminal illness riders: Access death benefit when diagnosed with terminal condition (typically less than 12-24 months to live)
- Chronic illness riders: Partial benefit access for chronic conditions requiring long-term care
- Critical illness riders: Standalone critical illness coverage added to base life policy
These hybrid approaches offer convenience-one policy, one premium, integrated underwriting. However, standalone critical illness policies often provide more generous coverage amounts and broader condition definitions than riders attached to life insurance.
Evaluating Your Coverage Needs
Determining appropriate coverage requires honest assessment of your financial obligations, health risks, and existing protection gaps.
Financial Obligations Analysis
Calculate the financial resources your family would need in two scenarios: your unexpected death and your survival through critical illness with reduced earning capacity.
Death scenario considerations:
- Outstanding mortgage balance
- Other debts (auto loans, credit cards, personal loans)
- Income replacement duration (years until spouse retires or children are independent)
- College funding for children
- Final expenses (funeral, estate settlement)
Critical illness scenario considerations:
- Health insurance out-of-pocket maximums
- Income replacement during 3-6+ month recovery
- Experimental or alternative treatment costs
- Home healthcare or rehabilitation expenses
- Transportation and lodging for specialized treatment
Risk Assessment Based on Personal Factors
Your age, family health history, occupation, and lifestyle all influence your exposure to critical illness events. Research from the Society of Actuaries on expanding health insurance access discusses how product designers price critical illness coverage based on age-graded risk curves and gender-specific incidence rates.
A 35-year-old non-smoker with no family history of heart disease faces different risks than a 55-year-old with diabetes and family history of stroke. These factors affect both your need for protection and your cost to obtain it.
Cost Factors and Premium Considerations
Understanding what drives insurance costs helps you budget appropriately and identify opportunities to reduce premiums without sacrificing necessary coverage.
Life Insurance Premium Determinants
Life insurance pricing reflects mortality risk assessment:
- Age: Premiums increase significantly with age-a 30-year-old pays far less than a 50-year-old for identical coverage
- Health status: Medical conditions, prescription medications, and recent health events increase premiums
- Tobacco use: Smokers typically pay 2-3 times more than non-smokers
- Gender: Women generally pay less due to longer life expectancy
- Coverage amount and term: Higher death benefits and longer terms cost more
- Occupation and hobbies: High-risk jobs or activities (aviation, diving, racing) increase premiums
A healthy 40-year-old non-smoking male in the Triad Area might pay $30-50 monthly for $500,000 of 20-year term coverage, while the same coverage for a 40-year-old smoker with controlled hypertension might cost $120-180 monthly.
Critical Illness Coverage Costs
Critical illness insurance premiums depend on similar factors plus coverage-specific elements:
- Benefit amount: Higher lump-sum payouts increase premiums proportionally
- Covered conditions: More comprehensive condition lists cost more
- Partial payment options: Some policies pay reduced benefits for less severe diagnoses
- Recurrence provisions: Whether the policy pays again for separate occurrences
- Return of premium: Options that refund premiums if no claim is filed
| Age | $25,000 Benefit | $50,000 Benefit | $100,000 Benefit |
|---|---|---|---|
| 30 | $15-25/month | $30-45/month | $60-85/month |
| 40 | $25-40/month | $50-75/month | $95-140/month |
| 50 | $50-80/month | $95-150/month | $180-280/month |
| 60 | $100-160/month | $190-300/month | $360-550/month |
Estimates for healthy non-smokers; actual premiums vary by carrier and underwriting
Employer Coverage vs. Individual Policies
Many people first encounter life insurance and critical illness cover through workplace benefits. Understanding the differences between employer-provided and individual coverage helps you identify protection gaps.
Employer Group Coverage Features
According to SHRM’s 2025 employee benefits survey, employer adoption of supplemental benefits including critical illness insurance continues growing, with 24% of employers now offering voluntary critical illness coverage.
Advantages of employer coverage:
- Guaranteed issue up to certain amounts (no medical underwriting)
- Payroll deduction convenience
- Group pricing potentially lower than individual rates
- Immediate availability to new employees
Limitations to consider:
- Coverage typically limited to 1-2 times salary for life insurance
- Portability issues-coverage often ends when employment ends
- Insufficient benefit amounts for comprehensive protection
- Less customization than individual policies
When Individual Policies Make Sense
Individual policies offer control and customization that group coverage cannot match. You own the policy regardless of employment changes, select coverage amounts based on your actual needs rather than employer formulas, customize riders and features specific to your situation, and lock in premiums at your current age and health status.
For residents of Greensboro, Kernersville, High Point, Winston Salem, and the Triad Area, working with a local insurance professional ensures you understand both your employer benefits and how individual policies fill remaining gaps. Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to review your complete coverage picture.
Policy Features Worth Understanding
Beyond basic coverage amounts, specific policy provisions significantly affect how well your insurance performs when you need it most.
Exclusions and Limitations
Every policy excludes certain circumstances or conditions. Common exclusions include:
Life insurance exclusions:
- Suicide within first two policy years
- Death during commission of illegal acts
- Material misrepresentation on application (during contestability period)
- War or acts of terrorism (in some policies)
Critical illness exclusions:
- Pre-existing conditions diagnosed before coverage effective date
- Self-inflicted injuries
- Alcohol or drug-related conditions
- Certain cancers (skin cancer often excluded or limited)
- Conditions not meeting severity thresholds defined in policy
Conversion and Portability Options
Term life insurance with conversion privileges allows you to convert to permanent coverage without new medical underwriting-valuable if you develop health conditions during the term. This feature costs slightly more but provides crucial flexibility as your needs evolve.
Group coverage portability lets you continue employer-provided coverage when you leave the company, though premiums typically increase to individual rates and coverage amounts may be limited.
Waiver of Premium Provisions
Waiver of premium riders continue your coverage without premium payments if you become disabled and unable to work. This prevents your protection from lapsing precisely when you're most financially vulnerable.
Application and Underwriting Process
Understanding what to expect during the application process reduces stress and helps ensure smooth approval.
Documentation Requirements
Life insurance applications require comprehensive information:
- Personal identification and contact details
- Medical history including conditions, treatments, medications, and surgeries
- Family health history (parents, siblings)
- Lifestyle questions (tobacco, alcohol, dangerous hobbies)
- Financial information (income, net worth, existing coverage)
- Beneficiary designations
Critical illness applications ask similar questions with emphasis on risk factors for covered conditions-cardiovascular history, cancer screenings, diabetes markers, and more.
Medical Examinations and Testing
Most life insurance applications above $250,000 require a medical exam conducted by a paramedical professional at your home or convenient location. The exam typically includes:
- Height, weight, blood pressure measurement
- Blood draw for cholesterol, glucose, liver function, and other markers
- Urinalysis
- Medical history review and questionnaire
Simplified issue policies skip the exam in exchange for lower coverage amounts and higher premiums. Guaranteed issue policies require no medical questions or exam but carry significant premium increases and lower maximum benefits.
Timeline Expectations
From application to policy issuance typically takes 4-8 weeks for fully underwritten coverage. The process includes application submission (1-2 days), medical exam scheduling and completion (1-2 weeks), lab results and medical records collection (2-3 weeks), underwriting review and decision (1-2 weeks), and policy delivery and acceptance (3-5 days).
Simplified issue policies can be approved in days rather than weeks, making them attractive despite higher costs.
Integrating With Overall Financial Planning
Life insurance and critical illness cover don't exist in isolation-they form part of your comprehensive financial protection strategy alongside emergency funds, disability insurance, health insurance, and retirement savings.
Coordination With Health Insurance
Understanding how health insurance and critical illness coverage interact prevents duplication while ensuring gaps are filled. Your health insurance pays medical bills directly to providers based on covered services minus deductibles and copays. Critical illness insurance pays you regardless of what health insurance covers, providing funds for non-medical expenses or costs your health plan doesn't cover.
This coordination matters particularly for those with high-deductible health plans. A hospital indemnity plan or critical illness policy provides cash to cover those substantial deductibles when serious illness strikes. For more information about supplemental coverage options, visit Moser Insurance Group Inc.
Estate Planning Considerations
Life insurance proceeds pass directly to named beneficiaries outside of probate-providing immediate liquidity when families need it most. This makes life insurance a powerful estate planning tool, especially for:
- Providing immediate cash for estate taxes, debts, and final expenses
- Equalizing inheritances when some heirs receive illiquid assets (business, real estate)
- Creating inheritance for heirs when most assets are in retirement accounts
- Funding special needs trusts for disabled beneficiaries
Regular Coverage Reviews
Your insurance needs change as life circumstances evolve. Schedule annual reviews to assess whether coverage remains appropriate:
- Marriage or divorce affecting beneficiary designations and coverage needs
- Birth or adoption of children increasing income replacement requirements
- Mortgage payoff reducing necessary coverage
- Career advancement changing income and benefit amounts
- Health changes affecting insurability and premium rates
- Policy anniversary approaching allowing conversion or adjustments
Common Misconceptions and Mistakes
Avoiding common errors ensures your coverage performs as intended when needed.
"I'm Too Young" or "I'm Too Healthy"
Many people delay purchasing life insurance and critical illness cover because they feel invincible. This logic backfires-premiums increase with age, and future health conditions may make coverage more expensive or unobtainable. A 30-year-old locks in dramatically lower premiums than the same person at 50, even if both remain healthy.
Relying Solely on Employer Coverage
While employer benefits provide valuable foundation coverage, they rarely suffice for comprehensive protection. Coverage amounts limited to one or two times salary leave significant gaps for families with mortgages, childcare costs, or college savings goals. Moreover, employer coverage disappears when you change jobs-precisely when gaps in coverage are most dangerous.
Naming Minor Children as Beneficiaries
Life insurance proceeds cannot be paid directly to minor children. Without proper planning, courts appoint guardians to manage funds until children reach majority-an expensive, time-consuming process. Instead, establish a trust or name an adult custodian under the Uniform Transfers to Minors Act as beneficiary.
Overlooking Policy Riders
Valuable riders often cost little but provide significant additional protection. Accelerated death benefit riders, waiver of premium for disability, accidental death benefits, and child term riders enhance coverage for modest additional premium.
Failing to Update Beneficiaries
Life changes-marriage, divorce, births, deaths-require beneficiary updates. Outdated designations cause unintended consequences, like ex-spouses receiving benefits intended for current families. Review and update beneficiaries after any major life event.
Finding the Right Coverage for Your Situation
No single approach fits every family. Your optimal combination of life insurance and critical illness cover depends on your unique circumstances, goals, and risk tolerance.
Questions to Guide Your Decision
Consider these questions as you evaluate options:
- What financial obligations would burden my family if I died unexpectedly?
- How would six months without my income affect my household if I faced serious illness?
- Do I have adequate emergency savings to cover health insurance deductibles and coinsurance?
- What employer benefits do I currently have, and are they sufficient?
- Are there health conditions in my family history that increase my risk?
- Can I afford the premium both now and if my financial situation changes?
Working With Insurance Professionals
Insurance products involve complex terms, exclusions, and pricing structures that challenge even sophisticated consumers. Working with experienced insurance professionals ensures you understand what you're purchasing and how it fits your overall financial plan.
Local professionals serving the Greensboro, High Point, Winston Salem, Kernersville, and Triad Area understand specific considerations affecting North Carolina families-from regional health statistics to state insurance regulations and local economic factors.
Look for professionals who:
- Prioritize education over sales pressure
- Represent multiple carriers to offer genuine comparison
- Explain policy details in plain language
- Provide ongoing service for claims and policy adjustments
- Maintain proper licenses and professional credentials
Protecting your family's financial security requires understanding how different insurance products address different risks. Life insurance and critical illness cover each serve distinct but complementary purposes-one safeguarding your family's future after your death, the other providing resources during serious illness when you're still alive. By carefully evaluating your obligations, risks, and existing coverage, you can build a protection strategy that delivers genuine peace of mind. The team at Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate these important decisions with clear guidance and personalized support. Call us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your insurance needs without pressure-just honest answers to help you protect what matters most.
Recent Comments