

Medicare coverage can feel overwhelming, especially when you're trying to understand the alphabet soup of plan letters and options. While many people have heard of Medicare Part A and Part B, there's often confusion around what "Medicare Part G" actually means. The term itself can be misleading-there isn't technically a "Medicare Part G" offered by the federal government. What most people are referring to is Medicare Supplement Plan G, also called Medigap Plan G, which has become the most popular and comprehensive supplemental insurance option available to Medicare beneficiaries in 2026. This plan works alongside Original Medicare to cover many of the out-of-pocket costs that Parts A and B don't pay, providing substantial financial protection and peace of mind for seniors and those with qualifying disabilities across the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem.
Understanding What Medicare Part G Actually Is
When someone mentions medicare part g, they're typically talking about Medigap Plan G, a standardized supplemental insurance policy sold by private insurance companies. This plan is designed to work with Original Medicare (Parts A and B) to help cover gaps in coverage.
Original Medicare consists of:
- Part A (hospital insurance)
- Part B (medical insurance)
These two parts cover many healthcare services, but they don't cover everything. You'll still face deductibles, copayments, and coinsurance that can add up quickly. That's where medicare part g comes in.
The Standardization of Medigap Plans
The federal government standardizes all Medigap plans, including medicare part g, meaning that Plan G from one insurance company offers the exact same benefits as Plan G from another company. The standardized Medigap coverage framework ensures beneficiaries can compare plans apples-to-apples.
What differs between carriers is:
- Premium costs (can vary significantly)
- Customer service quality
- Claims processing efficiency
- Financial stability ratings
This standardization makes shopping for medicare part g more straightforward than navigating many other insurance products.
What Medicare Part G Covers in 2026
Medicare part g provides extensive coverage that fills nearly all the gaps left by Original Medicare. Understanding exactly what it covers helps you evaluate whether it's the right choice for your situation.
| Service | What Plan G Pays |
|---|---|
| Part A deductible | 100% (after you meet it once) |
| Part A copays/coinsurance | 100% for hospital stays, skilled nursing |
| Part A hospice care copays | 100% |
| Part B copays/coinsurance | 100% |
| Part B excess charges | 100% |
| First three pints of blood | 100% |
| Foreign travel emergency (up to plan limits) | 80% after $250 deductible |
The most notable gap in coverage is the Part B deductible, which medicare part g does not cover. In 2026, this deductible is set by Medicare annually and must be paid out-of-pocket before Plan G benefits begin for Part B services.
Key Benefits That Set Plan G Apart
Beyond the basic coverage table, medicare part g offers several practical advantages:
- No network restrictions: See any doctor who accepts Medicare
- Guaranteed renewable: Cannot be canceled as long as you pay premiums
- Coverage travels with you: Valid anywhere in the U.S. and during foreign travel emergencies
- Predictable costs: After the Part B deductible, you have minimal out-of-pocket expenses
For beneficiaries in Winston Salem, Greensboro, High Point, and Kernersville, having the freedom to choose providers without network limitations means access to Duke, Wake Forest Baptist, and Cone Health facilities without referral requirements or prior authorizations.
Costs and Premiums for Medicare Part G
Premium costs for medicare part g vary widely based on several factors. Understanding these variables helps you find the most affordable option while maintaining comprehensive coverage.
Factors Affecting Your Premium
Age: Insurance companies use three pricing methods:
- Community-rated (same price regardless of age)
- Issue-age-rated (based on your age when you buy)
- Attained-age-rated (increases as you get older)
Location: Premiums vary significantly by ZIP code. In North Carolina's Triad region, you might see different rates in Greensboro compared to rural areas nearby.
Gender: Some states allow gender-based pricing; women often pay slightly higher premiums due to longer life expectancy.
Tobacco use: Smokers typically pay 15-30% more than non-smokers.
Insurance company: Even for identical coverage, premiums can differ by $50-100 per month between carriers.
According to recent data on Medigap enrollment and costs, national average premiums for medicare part g in 2026 range from approximately $140 to $220 per month, though individual quotes may fall outside this range.
Comparing Plan G to Other Options
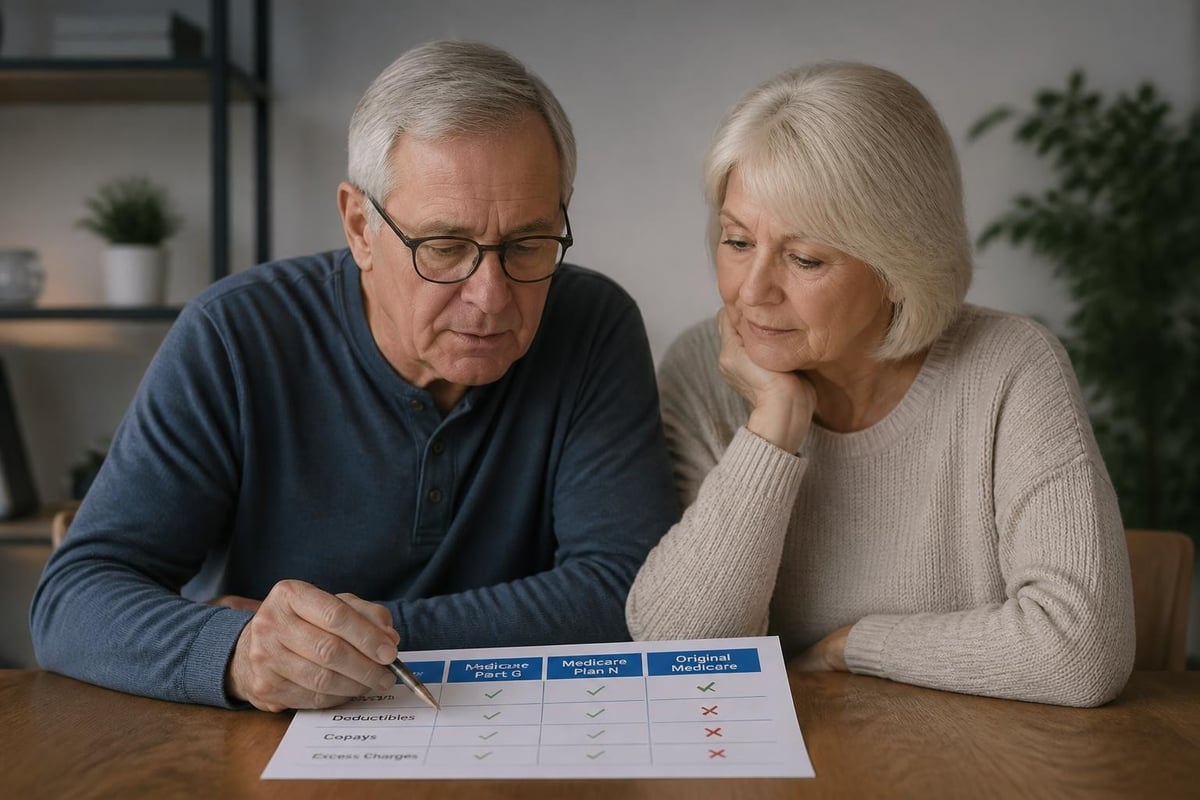
| Factor | Plan G | Plan N | Plan F |
|---|---|---|---|
| Part B deductible coverage | No | No | Yes |
| Part B excess charges | Yes | Yes | Yes |
| Part B copays | Yes | No (up to $20 office, $50 ER) | Yes |
| Availability to new enrollees | Yes | Yes | No (grandfathered only) |
| Typical premium | Mid-high | Lower | Highest |
Plan F was historically the most comprehensive option but became unavailable to new Medicare beneficiaries after January 1, 2020. This change made medicare part g the new gold standard for comprehensive Medigap coverage.
Enrollment and Eligibility Requirements
Timing matters significantly when enrolling in medicare part g. The best time to purchase a Medigap policy is during your Medigap Open Enrollment Period, when you have guaranteed issue rights.
Your Medigap Open Enrollment Period
This six-month window begins the first day of the month when you're both:
- Age 65 or older AND
- Enrolled in Medicare Part B
During this period, insurance companies:
- Cannot deny you coverage
- Cannot charge you more due to health conditions
- Cannot impose waiting periods for pre-existing conditions
The step-by-step Medicare enrollment guidance explains the importance of acting during this window to secure the best rates and guaranteed acceptance.
Enrollment Outside the Open Enrollment Period
If you miss your Medigap Open Enrollment Period, you can still apply for medicare part g, but insurers may:
- Require medical underwriting
- Deny coverage based on health status
- Charge higher premiums
- Impose waiting periods for pre-existing conditions
Guaranteed issue rights exist in specific situations:
- Losing employer coverage
- Moving out of a Medicare Advantage plan's service area
- Insurance company bankruptcy or contract termination
In North Carolina, specific state regulations and consumer protections may provide additional enrollment opportunities beyond federal minimum requirements.
Why Medicare Part G Has Become the Most Popular Choice
The popularity of medicare part g has surged since 2020 when Plan F became unavailable to new enrollees. Several factors explain why beneficiaries and insurance professionals consistently recommend this option.
Comprehensive Coverage with Predictability
After paying the annual Part B deductible, medicare part g covers virtually all Medicare-approved costs. This means:
- No surprise medical bills from covered services
- Simplified healthcare budgeting
- Reduced financial stress during illness
For someone managing chronic conditions or facing unexpected health challenges, this predictability proves invaluable.
Better Value Than Plan F for New Enrollees
While Plan F covers the Part B deductible (which Plan G doesn't), the premium difference typically exceeds the deductible amount. Basic math shows:
- Plan F average premium: $210/month ($2,520/year)
- Plan G average premium: $180/month ($2,160/year)
- Annual savings with Plan G: $360
- Part B deductible (2026): Approximately $240
Net savings with medicare part g: roughly $120 annually, plus lower premiums compound over time.
Protection Against Part B Excess Charges
Medicare Part B excess charges occur when doctors who accept Medicare but haven't agreed to accept assignment charge up to 15% more than the Medicare-approved amount. Medicare part g covers these excess charges completely, while some less comprehensive plans don't.
In practice, excess charges are relatively rare-only about 1% of providers bill above Medicare rates-but the protection offers peace of mind and eliminates another variable in healthcare costs.
How to Shop for Medicare Part G Effectively
Shopping for medicare part g requires more than just comparing the lowest premium. A strategic approach ensures you get quality coverage at a fair price while working with a reliable insurance company.
Step 1: Verify the plan is genuine Plan G
All Plan G policies must offer identical benefits. Confirm you're comparing true Plan G coverage from licensed insurers.
Step 2: Request quotes from multiple carriers
Get at least 3-5 quotes to understand your local market. Premiums in the Greensboro and Winston Salem areas may differ from state or national averages.
Step 3: Check the insurance company's financial ratings
Look for carriers rated A- or better by A.M. Best. Financial stability matters for a policy you'll keep for decades.
Step 4: Understand the pricing methodology
Ask whether premiums are community-rated, issue-age-rated, or attained-age-rated. This affects your long-term costs.
Step 5: Review customer service reputation
Read reviews and check complaint ratios with your state insurance department. Quality customer service matters when filing claims.
The Missouri Department of Insurance shopping guide provides an excellent template for creating your own comparison worksheet, even if you're shopping in North Carolina.
Common Misconceptions About Medicare Part G
Several myths and misunderstandings surround medicare part g. Clearing these up helps beneficiaries make informed decisions.
"Medicare Part G is a government program"
Reality: Medicare part g is private insurance that supplements government Medicare. While the benefits are standardized by federal regulations, you purchase the policy from private insurance companies.
"I can't switch plans once I choose one"
Reality: You can switch Medigap plans at any time, though you may face medical underwriting if switching outside guaranteed issue periods. Some beneficiaries switch to take advantage of lower premiums from different carriers.
"Plan G doesn't cover prescriptions"
Reality: No Medigap plan covers prescription drugs. You need a separate Medicare Part D plan for prescription coverage. Medicare part g works alongside Part D, not instead of it.
"I need to re-enroll every year"
Reality: Unlike Medicare Advantage Plans, Medigap policies including medicare part g don't have annual enrollment periods. Your coverage continues automatically as long as you pay premiums.
Medicare Part G vs. Medicare Advantage
Many beneficiaries weigh medicare part g against Medicare Advantage (Part C) plans. These represent fundamentally different approaches to Medicare coverage.
Structural Differences
Medicare Part G approach:
- Keep Original Medicare Parts A & B
- Add private supplemental insurance
- Separate Part D drug plan
- Pay Part B premium + Plan G premium + Part D premium
Medicare Advantage approach:
- Replace Original Medicare
- All-in-one plan (medical + often drug coverage)
- May include extra benefits (dental, vision, hearing)
- Pay Part B premium + plan premium (sometimes $0)
Flexibility and Provider Access
Medicare part g offers maximum flexibility:
- Any doctor accepting Medicare
- No referrals needed
- No network restrictions
- Nationwide coverage
Medicare Advantage typically requires:
- Staying in network (HMO) or paying more out-of-network (PPO)
- Referrals for specialists (HMO plans)
- Geographic service area limitations
For residents of the Triad Area spanning Greensboro, High Point, Winston Salem, and Kernersville who may seek care at various facilities or travel frequently, the unrestricted access with medicare part g often proves more convenient.
Cost Structure Comparison
| Cost Element | Medicare Part G | Medicare Advantage |
|---|---|---|
| Monthly premium | Higher ($140-220+) | Lower (often $0-50) |
| Per-service costs | Minimal after Part B deductible | Copays per visit/service |
| Maximum out-of-pocket | Generally none beyond deductible | Yes (varies by plan) |
| Predictability | Very high | Moderate (depends on usage) |
The comparison analysis from Consumer Reports highlights that medicare part g typically makes more financial sense for those with frequent medical needs, while Medicare Advantage may benefit healthy individuals with limited healthcare usage.
Special Considerations for North Carolina Residents
North Carolina residents shopping for medicare part g should understand state-specific factors that may affect their coverage and costs.
State Regulations and Consumer Protections
North Carolina follows federal Medigap rules but doesn't offer additional state-specific guaranteed issue rights beyond federal minimums. This means timing your enrollment during the Medigap Open Enrollment Period is particularly important.
Regional Premium Variations
Premium costs vary across North Carolina. Urban areas like Greensboro, Winston Salem, and High Point may have:
- More carrier competition (potentially lower premiums)
- Higher healthcare costs (potentially higher premiums)
- Better access to independent agents specializing in Medicare
Rural areas may face:
- Fewer carrier options
- Limited local agent availability
- Different rating factors
Access to Quality Healthcare Providers
The Triad region offers excellent healthcare access through major systems including Cone Health, Novant Health, and Wake Forest Baptist Health. Medicare part g allows beneficiaries to use any of these providers without network concerns.
Tax Implications and Financial Planning
Understanding how medicare part g fits into your broader financial picture helps with retirement planning and tax strategy.
Premium Deductibility
Medicare part g premiums may be tax-deductible if you itemize deductions and meet certain criteria. According to IRS Publication 502, medical expenses including Medicare supplemental insurance premiums are deductible to the extent they exceed 7.5% of your adjusted gross income.
Example calculation:
- Adjusted Gross Income: $50,000
- 7.5% threshold: $3,750
- Total medical expenses: $5,200 (including Plan G premiums)
- Deductible amount: $1,450
This deduction is only valuable if you itemize rather than taking the standard deduction, which many retirees don't exceed.
Household Discount Opportunities
Many insurance carriers offer household discounts when both spouses purchase Medigap policies from the same company. These discounts typically range from 5-12% and can result in significant savings over time.
If both you and your spouse need medicare part g, exploring household discounts can reduce your combined premiums by $200-400 annually.
Long-Term Cost Projections
When evaluating medicare part g, consider long-term premium increases. Attained-age-rated policies increase premiums as you age, while community-rated policies spread costs across all ages more evenly.
20-year cost comparison (hypothetical):
- Attained-age Plan G starting at $150/month: Total ~$52,000
- Community-rated Plan G starting at $180/month: Total ~$54,000
The difference narrows over time, and community-rated plans may actually become cheaper in later years.
When Medicare Part G May Not Be the Best Choice
Despite its comprehensive coverage, medicare part g isn't the optimal solution for every Medicare beneficiary. Certain situations call for alternative approaches.
Light Healthcare Users
If you're in excellent health and rarely visit doctors, the high premiums of medicare part g may exceed your actual out-of-pocket costs with Original Medicare alone or with a less expensive supplement like Plan N.
Calculation for minimal healthcare use:
- Plan G annual premium: $2,160
- Part B deductible: $240
- Actual healthcare costs with no supplement: $800
- Savings without Plan G: $1,600
However, this approach carries risk if unexpected health issues arise.
Budget-Conscious Beneficiaries
Those on tight fixed incomes may find the monthly premium for medicare part g challenging to afford. Alternatives include:
- Plan N: Lower premiums with modest copays
- High-deductible Plan G: Significantly lower premiums but higher out-of-pocket maximums
- Medicare Advantage: Often $0 premium with per-service costs
The decision ultimately depends on balancing monthly cash flow against potential out-of-pocket medical expenses.
Those Who Travel Extensively Abroad
While medicare part g includes limited foreign travel emergency coverage (80% after $250 deductible, up to $50,000 lifetime), it's not comprehensive international insurance. Beneficiaries spending significant time abroad may need supplemental travel medical insurance.
Making Your Medicare Part G Decision
Choosing whether to purchase medicare part g requires evaluating your personal health status, financial situation, and healthcare preferences. According to analysis from Kiplinger on selecting Medigap coverage, Plan G has emerged as the most balanced option for most new Medicare beneficiaries in 2026.
Questions to Ask Yourself
Before committing to medicare part g, consider:
- How frequently do I visit doctors and specialists?
- Can I afford the monthly premium comfortably?
- Do I want maximum flexibility in choosing providers?
- Am I willing to pay more monthly for minimal out-of-pocket costs?
- Do I have chronic conditions requiring regular treatment?
- Is financial predictability important to me?
Working with an Independent Insurance Agent
Navigating Medicare options can be complex. An independent insurance agent who understands medicare part g and other Medicare supplements can:
- Provide personalized quotes from multiple carriers
- Explain coverage details specific to your situation
- Help you understand the enrollment timeline
- Answer questions about how Medigap works with other coverage
- Assist with application completion
In the Triad Area communities of Greensboro, Kernersville, High Point, and Winston Salem, working with a local agent means getting advice tailored to North Carolina's insurance market and regional healthcare landscape.
For personalized guidance, you can reach Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com.
Review Your Decision Annually
Even after enrolling in medicare part g, review your coverage annually to ensure it still meets your needs. While you don't need to re-enroll, circumstances change:
- Premiums increase at different rates across carriers
- Your health status may change
- Your financial situation may shift
- New plan options may become available
An annual review helps you stay informed and potentially save money by switching carriers if you qualify for better rates without medical underwriting.
Medicare part g represents the most comprehensive supplemental insurance option available to new Medicare beneficiaries in 2026, offering extensive coverage that eliminates most out-of-pocket costs beyond the Part B deductible. Understanding exactly what this standardized Medigap plan covers, how premiums are determined, and when to enroll empowers you to make a confident insurance decision. Whether you're approaching your Medicare eligibility or helping a family member navigate their options, the combination of comprehensive benefits and provider flexibility makes medicare part g worth serious consideration. Moser Insurance Group Inc helps individuals and families in the Greensboro, Winston Salem, High Point, and Kernersville areas understand their Medicare options with clear guidance and personalized support-call us at 336-862-1763 or visit Moser Insurance Group Inc to discuss how medicare part g fits your specific situation.
Recent Comments