

Planning for end-of-life expenses might feel uncomfortable, but it represents one of the most thoughtful gifts you can give your family. A final expense plan ensures that your loved ones won't face the financial burden of funeral costs, burial expenses, and related bills during an already difficult time. In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, families face average funeral costs ranging from $7,000 to $12,000, a sum that can create significant hardship for those left behind. Understanding how final expense insurance works helps you make an informed decision about protecting your family's financial future while maintaining your peace of mind.
What Is a Final Expense Plan
A final expense plan is a type of permanent life insurance specifically designed to cover end-of-life costs. Unlike traditional life insurance policies that provide large death benefits for income replacement, these plans offer smaller coverage amounts typically ranging from $5,000 to $35,000.
The primary purpose focuses on covering funeral services, burial or cremation costs, outstanding medical bills, and other final obligations. These policies feature simplified underwriting, making them accessible to seniors and individuals who might struggle to qualify for traditional life insurance due to health conditions.
Key Characteristics That Set It Apart
Guaranteed acceptance represents one of the most significant features for many applicants. Most final expense plans accept applicants aged 50 to 85 without requiring medical exams, though some carriers extend coverage to age 90 or beyond.
The coverage remains in force for your entire lifetime as long as premiums are paid. This permanent protection means your beneficiaries will receive the death benefit regardless of when you pass away, whether that's next year or three decades from now.
- Fixed premiums that never increase with age or health changes
- Quick benefit payout to beneficiaries, often within days
- Cash value accumulation in many policies
- No medical exam required for most applicants
- Flexible payment options including monthly, quarterly, or annual premiums
Premium amounts depend on your age at application, coverage amount, gender, tobacco use, and specific health questions answered during the application process. A 65-year-old non-smoking woman might pay $45 monthly for $10,000 in coverage, while a 75-year-old male smoker could pay $125 for the same benefit.
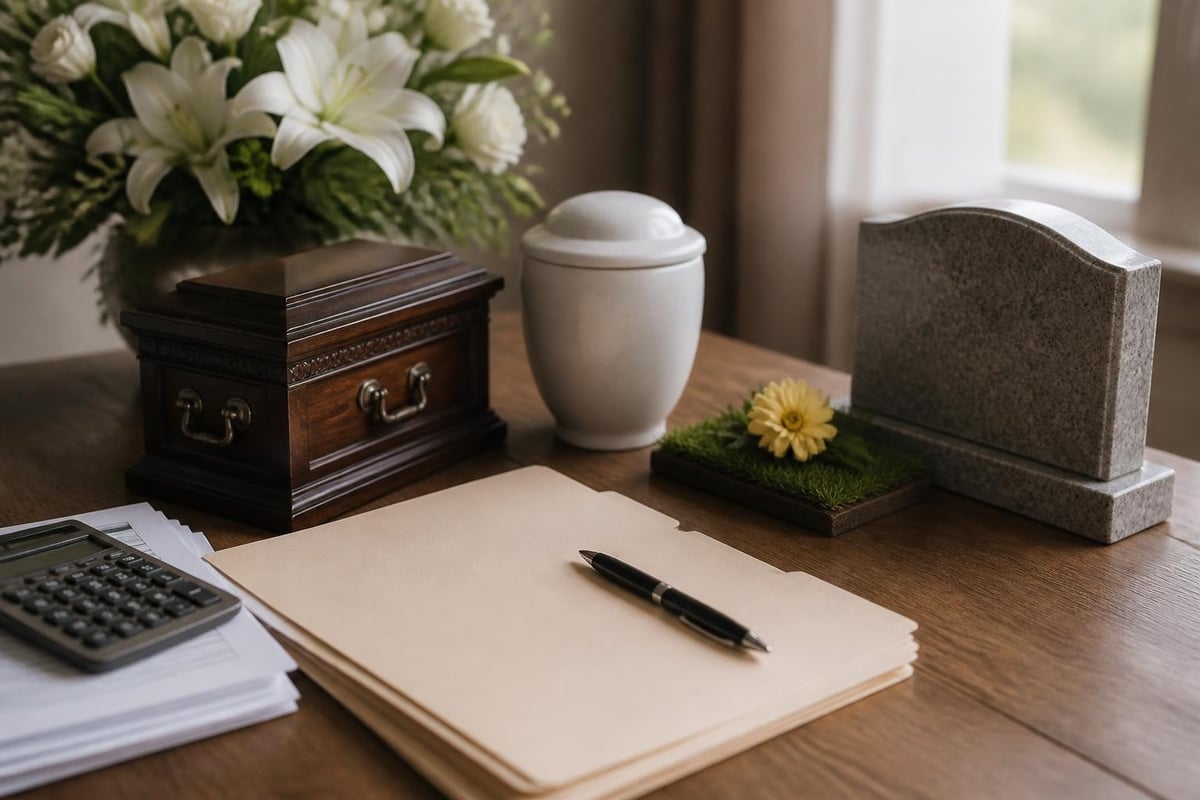
Coverage Amounts and Cost Considerations
Determining the right coverage amount requires careful consideration of anticipated expenses. According to recent Consumer Financial Protection Bureau research on household financial shocks, unexpected funeral costs rank among the top financial disruptions American families face.
Calculating Your Coverage Needs
Start by estimating typical funeral home charges in your area. In the Triad Area, basic services from funeral directors average $2,500 to $4,000 before additional selections. The casket alone can range from $2,000 for basic models to $10,000 or more for premium options.
| Expense Category | Low Range | High Range |
|---|---|---|
| Funeral home basic services | $2,500 | $4,000 |
| Casket or cremation container | $1,000 | $10,000 |
| Burial vault | $1,200 | $4,000 |
| Cemetery plot | $1,000 | $5,000 |
| Headstone or marker | $1,500 | $8,000 |
| Memorial service venue | $500 | $2,000 |
| Flowers, programs, obituary | $500 | $1,500 |
Beyond funeral expenses, consider outstanding debts, final medical bills not covered by Medicare or other insurance, estate administration costs, and probate fees. The IRS Publication 559 provides detailed guidance on which expenses may be deductible from the estate.
Premium Factors and Payment Structures
Insurance carriers calculate premiums using actuarial tables that predict life expectancy. Younger applicants pay significantly less because they'll likely pay premiums for more years before the death benefit is claimed.
Gender matters in pricing because women statistically live longer than men. A 70-year-old woman typically pays 15-25% less than a man of the same age for identical coverage. Tobacco users face premiums that are 30-50% higher due to reduced life expectancy and increased health risks.
Most final expense plans offer level premiums that remain constant throughout the policy's life. Some carriers provide limited-pay options where you pay for 10, 15, or 20 years, after which the policy remains in force with no further payments required.
Application Process and Eligibility Requirements
The simplified application process makes final expense insurance accessible to most seniors. Unlike traditional life insurance that requires extensive medical underwriting, blood tests, and physical examinations, these policies typically use a streamlined approach.
Guaranteed Issue vs. Simplified Issue
Guaranteed issue policies accept all applicants within the age range without any health questions. These policies often include a graded benefit period, usually two to three years, during which the full death benefit isn't available. If death occurs from illness during this period, beneficiaries receive a return of premiums plus interest rather than the full benefit amount. Accidental death typically pays the full benefit immediately.
Simplified issue policies ask basic health questions but don't require medical exams. Common questions address current treatments for cancer, heart disease, stroke, COPD, or kidney disease. Past health issues that have been resolved typically don't affect eligibility.
The application itself takes 15-30 minutes and can often be completed by phone, online, or in person. You'll need to provide basic information including full legal name, date of birth, Social Security number, current medications, and recent hospitalizations.
Most carriers approve applications within 24-48 hours for simplified issue policies. Guaranteed issue policies often provide immediate approval since there's no underwriting review.
How Beneficiaries Access and Use Benefits
When you pass away, your designated beneficiaries must notify the insurance company and submit a claim. This process requires providing a certified death certificate and completing claim forms provided by the carrier.
Claim Processing and Payout Timeline
Most insurance companies process final expense claims within 7-14 business days of receiving all required documentation. Some carriers offer accelerated benefit options that provide partial advances within 24-48 hours to cover immediate funeral expenses.
The death benefit is paid as a lump sum, tax-free payment directly to your named beneficiaries. They receive complete discretion in how these funds are used. While the intent is covering final expenses, no legal requirement mandates they use the money for funeral costs.
Multiple beneficiaries can be designated with percentage allocations you specify. Common arrangements include 50% to a spouse and 25% each to two children, or 100% to one trusted family member with the understanding they'll handle arrangements.
- Death certificate must be certified, not a photocopy
- Claim forms require beneficiary signatures and contact information
- Payment options include direct deposit or check
- Funds are available for any purpose the beneficiary chooses
- No probate delay since proceeds pass directly to named beneficiaries
Tax Implications and Estate Considerations
Life insurance death benefits, including those from a final expense plan, are generally income tax-free to beneficiaries. This tax advantage makes these policies efficient vehicles for transferring wealth and covering final costs.
However, death benefits may be included in your taxable estate if you own the policy at death and your total estate exceeds federal exemption thresholds. For 2026, the federal estate tax exemption stands at $13.61 million per individual, so most families won't face estate tax concerns.
The IRS Instructions for Form 1041 explain how estate administrators should handle insurance proceeds and which funeral expenses may be deductible on estate tax returns when applicable.
Comparing Final Expense to Other Life Insurance Options
Understanding where final expense insurance fits within the broader life insurance landscape helps you make informed coverage decisions. Each type of life insurance serves different purposes and offers distinct advantages.
Whole life insurance provides permanent coverage with guaranteed cash value growth and level premiums, but typically requires medical underwriting and offers much larger death benefits than most people need solely for final expenses. A whole life policy might provide $100,000 to $500,000 in coverage, making it suitable for estate planning and legacy building but potentially more expensive than necessary for end-of-life costs alone.
Policy Type Comparison
| Feature | Final Expense | Term Life | Whole Life |
|---|---|---|---|
| Coverage duration | Lifetime | 10-30 years | Lifetime |
| Medical exam | Usually no | Usually yes | Yes |
| Coverage amount | $5,000-$35,000 | $100,000+ | $50,000+ |
| Premium cost | Moderate | Low | High |
| Cash value | Sometimes | No | Yes |
| Age limits | 50-85+ | 18-65 | 18-80 |
Term life insurance offers affordable protection for specific time periods, making it ideal for income replacement during working years when dependents rely on your earnings. However, term policies expire, and if you outlive the term, you receive no benefit despite years of premium payments. This temporary nature makes term insurance poorly suited for covering final expenses that will definitely occur eventually.
Universal life insurance provides permanent coverage with flexible premiums and death benefits, but the complexity and required active management make it less straightforward than final expense policies designed specifically for covering end-of-life costs.
Common Questions and Misconceptions
Many people approaching retirement age have questions about final expense coverage and how it differs from other financial planning tools. Addressing these concerns helps clarify whether this type of policy fits your situation.
Pre-Need Funeral Plans vs. Final Expense Insurance
Pre-need funeral plans involve prepaying a funeral home directly for specific services at current prices. These arrangements lock in costs and guarantee particular services will be provided. However, you're tied to one funeral home, and if you move or change preferences, transferring funds can be complicated.
A final expense plan provides cash to beneficiaries who then have complete flexibility in choosing funeral arrangements, negotiating prices, and allocating any remaining funds as needed. This flexibility proves valuable if you relocate, if the contracted funeral home goes out of business, or if your family prefers different arrangements than you initially planned.
Graded vs. Immediate Death Benefits
Immediate benefit policies pay the full death benefit regardless of when death occurs, though they typically require answering health questions and may deny coverage based on serious conditions. These policies suit relatively healthy seniors who can qualify through simplified underwriting.
Graded benefit policies accept everyone regardless of health but include a waiting period (usually 24-36 months) during which deaths from illness result in premium refunds rather than the full benefit. Deaths from accidents pay the full benefit immediately even during the waiting period.
For someone aged 72 with significant health issues, a graded benefit policy might cost $65 monthly for $10,000 coverage. If they pass away from natural causes at age 73 (12 months in), beneficiaries would receive approximately $780 (premiums paid) plus interest. If death occurred at age 75 (after the graded period), the full $10,000 would be paid.
Making the Right Choice for Your Situation
Deciding whether a final expense plan makes sense requires evaluating your current financial picture, family circumstances, and existing coverage. Several factors should guide your decision-making process.
When Final Expense Insurance Makes Sense
If you have limited savings set aside specifically for funeral costs, a final expense plan provides peace of mind that these expenses won't burden your family. Many seniors on fixed incomes find it easier to budget for predictable monthly premiums rather than accumulating several thousand dollars in savings.
Health conditions that prevent qualifying for traditional life insurance make final expense policies particularly valuable. The guaranteed issue options ensure coverage regardless of your medical history, though you'll pay for this accessibility through higher premiums or graded benefits.
Individuals who want to ensure specific family members receive funds directly without going through probate appreciate how life insurance proceeds pass immediately to named beneficiaries. This arrangement avoids court delays and maintains privacy about your financial affairs.
When Other Options Might Be Better
If you're under 60 and in good health, term life insurance typically offers more cost-effective coverage. You might purchase a $250,000 20-year term policy for the same premium as a $15,000 final expense plan, providing significantly more financial protection for your family.
Substantial liquid savings dedicated to final expenses might make additional insurance unnecessary. If you've already set aside $15,000 in a payable-on-death account designated for funeral costs, adding insurance could be redundant.
Those with existing life insurance coverage should evaluate whether current policies already provide adequate death benefits to cover final expenses along with other financial needs. Adding a final expense policy when you already carry $500,000 in term coverage may not be necessary unless you want to earmark specific funds exclusively for end-of-life costs.
Regulatory Protections and Company Selection
The life insurance industry operates under robust regulatory oversight designed to protect consumers. Understanding these protections helps you evaluate carriers and policies with confidence.
The National Association of Insurance Commissioners provides regulatory frameworks that govern life insurance products, including disclosure requirements and solvency standards. Each state insurance department oversees carriers operating within its borders, reviewing policy forms, monitoring financial stability, and investigating consumer complaints.
Evaluating Insurance Companies
Financial strength ratings from independent agencies like A.M. Best, Moody's, and Standard & Poor's indicate a company's ability to pay future claims. Look for carriers with ratings of A- or higher, signaling strong financial stability.
State guaranty associations provide backup protection if an insurance company becomes insolvent. These associations typically cover up to $300,000 in life insurance death benefits per insured individual, though limits vary by state. In North Carolina, the North Carolina Life and Health Insurance Guaranty Association protects policyholders up to statutory limits.
- Verify the company is licensed in your state
- Check complaint ratios through your state insurance department
- Review financial strength ratings from multiple agencies
- Understand the company's claims payment history
- Read policy illustrations and disclosures carefully
Working with an experienced insurance professional helps navigate the options and find coverage that fits your specific needs. Independent agents can compare policies from multiple carriers, explaining differences in pricing, underwriting, and policy features.
Application Tips and Best Practices
Maximizing the value of your final expense plan starts with making informed decisions during the application process. Several strategies help ensure you get appropriate coverage at fair prices.
Timing Your Application
Age significantly impacts premium costs, with rates increasing substantially as you get older. A 62-year-old might pay $42 monthly for $10,000 coverage, while waiting until age 67 could increase that premium to $58 for the same benefit. Applying sooner rather than later locks in lower rates that remain level for life.
However, purchasing coverage you don't truly need simply to secure lower rates doesn't make financial sense. Balance the desire for lower premiums against your actual current need for coverage and ability to afford ongoing payments.
Health status considerations matter for simplified issue policies. If you're currently being treated for a serious condition, waiting until treatment concludes and you've been stable for 6-12 months might help you qualify for better rates or immediate benefits rather than graded coverage.
Being Honest on Applications
Providing accurate information on your application is legally and ethically essential. Insurance companies can contest claims if material misrepresentations are discovered, potentially denying benefits to your beneficiaries when they need them most.
The contestability period, typically two years from the policy issue date, allows carriers to investigate and potentially void coverage if fraud or material misstatements are found. After this period passes, benefits are generally paid regardless of application errors except in cases of outright fraud.
Answer all health questions truthfully, disclose tobacco use accurately, and provide correct age information. If you're unsure how to answer a question, ask the agent for clarification rather than guessing.
Reviewing Your Coverage Regularly
Life circumstances change, and your final expense plan should be reviewed periodically to ensure it still meets your needs. Marriage, divorce, birth of grandchildren, or changes in financial circumstances might warrant beneficiary updates or coverage adjustments.
Beneficiary designations should be reviewed every few years or after major life events. Outdated beneficiaries (ex-spouses, deceased individuals, or estranged family members) can create complications and unintended consequences for your estate.
Some policies allow you to increase coverage at certain ages without new underwriting, while others might require a new application. Understanding your policy's provisions helps you make informed decisions about maintaining or adjusting coverage over time.
The Role of Final Expense Planning in Comprehensive Financial Security
End-of-life planning represents just one component of a complete financial security strategy. Integrating final expense coverage with other protections creates a robust safety net for you and your family.
Medicare covers many healthcare costs for seniors but includes gaps that can create financial exposure. Hospital deductibles, skilled nursing facility coinsurance, and Part B excess charges can accumulate significantly. While Medicare provides excellent core coverage, supplemental protection through Medigap or Medicare Advantage plans addresses these gaps.
Coordinating Multiple Coverage Types
Understanding how different insurance products work together prevents both coverage gaps and unnecessary overlap. Your final expense plan specifically addresses end-of-life costs, while health insurance manages ongoing medical expenses, and longer-term life insurance provides income replacement or legacy benefits.
For many Triad Area families in Greensboro, Kernersville, High Point, and Winston Salem, a coordinated approach might include Medicare for healthcare, a final expense plan for end-of-life costs, and perhaps a small whole life policy for estate planning purposes. This layered protection addresses different financial risks without overpaying for redundant coverage.
If you need help understanding how these pieces fit together for your specific situation, reaching out to Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com provides access to professionals who can explain your options without pressure.
Taking Action on Your Final Expense Planning
Once you understand how final expense insurance works and have determined it fits your needs, taking action involves several concrete steps. Preparing for the application process and organizing necessary information streamlines the experience.
Information to Gather Before Applying
Collect basic personal information including your Social Security number, driver's license, current address, and contact details. If applying for simplified issue coverage, prepare a list of current medications with dosages, recent hospitalizations or surgeries within the past two years, and names of physicians you see regularly.
Beneficiary information should be complete and accurate, including full legal names, dates of birth, Social Security numbers, and relationship to you. Deciding on primary and contingent beneficiaries before starting the application prevents delays.
Consider whether you want to add any policy riders such as an accidental death benefit, which pays an additional amount if death results from an accident, or a waiver of premium rider, which continues coverage without premium payments if you become totally disabled.
Questions to Ask Insurance Professionals
Working with a knowledgeable agent helps clarify details specific to the policies you're considering. Important questions include how long the graded benefit period lasts if applicable, whether premiums can be paid annually for a discount, what happens if you miss a premium payment, whether there's a grace period, and how to submit a claim when the time comes.
Understanding the specific underwriting questions for simplified issue policies helps you anticipate whether you'll likely qualify or if guaranteed issue makes more sense. Ask about the company's financial ratings, how long they've been offering final expense coverage, and what their typical claims processing timeline looks like.
Request policy illustrations showing premium amounts, death benefits, and any cash value accumulation over time. Compare illustrations from multiple carriers to ensure you're getting competitive pricing and favorable terms.
Geographic Considerations for Triad Area Residents
Living in the Triad Area presents specific considerations when planning for final expenses. Funeral costs in Greensboro, Kernersville, High Point, and Winston Salem vary based on provider, services selected, and local market conditions.
Cemetery plot prices in the region range from approximately $1,000 for basic spaces in municipal cemeteries to $5,000 or more in private memorial parks with premium locations. Cremation has become increasingly popular in North Carolina, with costs typically ranging from $1,500 to $4,000 depending on the crematory and services included.
Local Resources and Support
North Carolina residents benefit from state insurance department resources that help resolve disputes, investigate complaints, and provide consumer education. The NC Department of Insurance maintains detailed information about licensed carriers and agents, making it easy to verify credentials before purchasing coverage.
For families in Greensboro, Kernersville, High Point, and Winston Salem, working with a local insurance professional who understands regional cost factors and can meet in person if desired adds value to the planning process. Local agents maintain relationships with multiple carriers and can facilitate the application and claims processes more personally than distant call centers.
Protecting your family from the financial burden of final expenses represents a thoughtful act of care that provides peace of mind for everyone involved. A final expense plan offers accessible, affordable coverage designed specifically to handle end-of-life costs without complicated underwriting or extensive medical requirements. If you're ready to explore your options and understand which coverage makes sense for your situation, Moser Insurance Group Inc provides personalized guidance throughout the Triad Area without pressure or confusing jargon. Contact them at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to start a conversation about securing your family's financial future with confidence.
Recent Comments