

Medicare beneficiaries in the Triad Area-including Greensboro, Kernersville, High Point, and Winston Salem-often search for ways to reduce out-of-pocket healthcare costs while maintaining flexibility in provider choice. Medicare Plan N has emerged as a practical middle-ground option among the standardized Medicare Supplement plans available today. This plan offers comprehensive coverage at a lower premium than some alternatives, though it requires modest copayments for certain services. Understanding how medicare plan n works, what it covers, and how it compares to other options can help you make an informed decision about your supplemental coverage.
What Medicare Plan N Covers
Medicare plan n is one of ten standardized Medigap policies regulated by federal law. The standardization means that Plan N benefits remain identical regardless of which insurance company sells the policy, though premiums vary by carrier and location.
Core Benefits Included
Plan N covers several major expense categories that Original Medicare leaves to beneficiaries:
- Part A coinsurance and hospital costs up to an additional 365 days after Medicare benefits end
- Part A hospice care coinsurance or copayment
- Part B coinsurance or copayment with specific exceptions noted below
- Blood for the first three pints each year
- Skilled nursing facility coinsurance
- Part A deductible ($1,676 in 2026)
The plan provides strong protection against the high costs of hospital stays and skilled nursing care. When you're admitted to a hospital, medicare plan n pays your share of coinsurance after you've met the Part A deductible, which the plan itself covers.
What You Pay Out-of-Pocket
Unlike some Medigap plans that cover virtually everything, Plan N requires three specific out-of-pocket payments:
Part B Deductible: You must pay the annual Part B deductible ($257 in 2026) before Plan N coverage begins for Part B services. This represents your only annual deductible responsibility.
Doctor Office Visits: A copayment of up to $20 per visit applies when you see your doctor or specialist. This modest fee makes each appointment predictable and affordable.
Emergency Room Visits: Up to $50 per visit if the visit doesn't result in hospital admission. If you're admitted, the copay is waived and Plan N's hospital coverage takes over.
| Service Type | Your Cost with Plan N | What Plan N Pays |
|---|---|---|
| Hospital stays (after deductible) | $0 | 100% of coinsurance |
| Part A deductible | $0 | $1,676 (2026) |
| Part B deductible | $257 (2026) | Nothing |
| Doctor office visits | Up to $20 copay | Balance after copay |
| Emergency room | Up to $50 copay | Balance after copay |
| Skilled nursing coinsurance | $0 | 100% |
How Medicare Plan N Differs from Other Medigap Options
The standardized Medigap landscape offers choices ranging from comprehensive to basic coverage. According to recent enrollment data from Kaiser Family Foundation, Plan N has grown in popularity as beneficiaries seek affordable coverage without sacrificing essential protection.
Plan N vs. Plan G
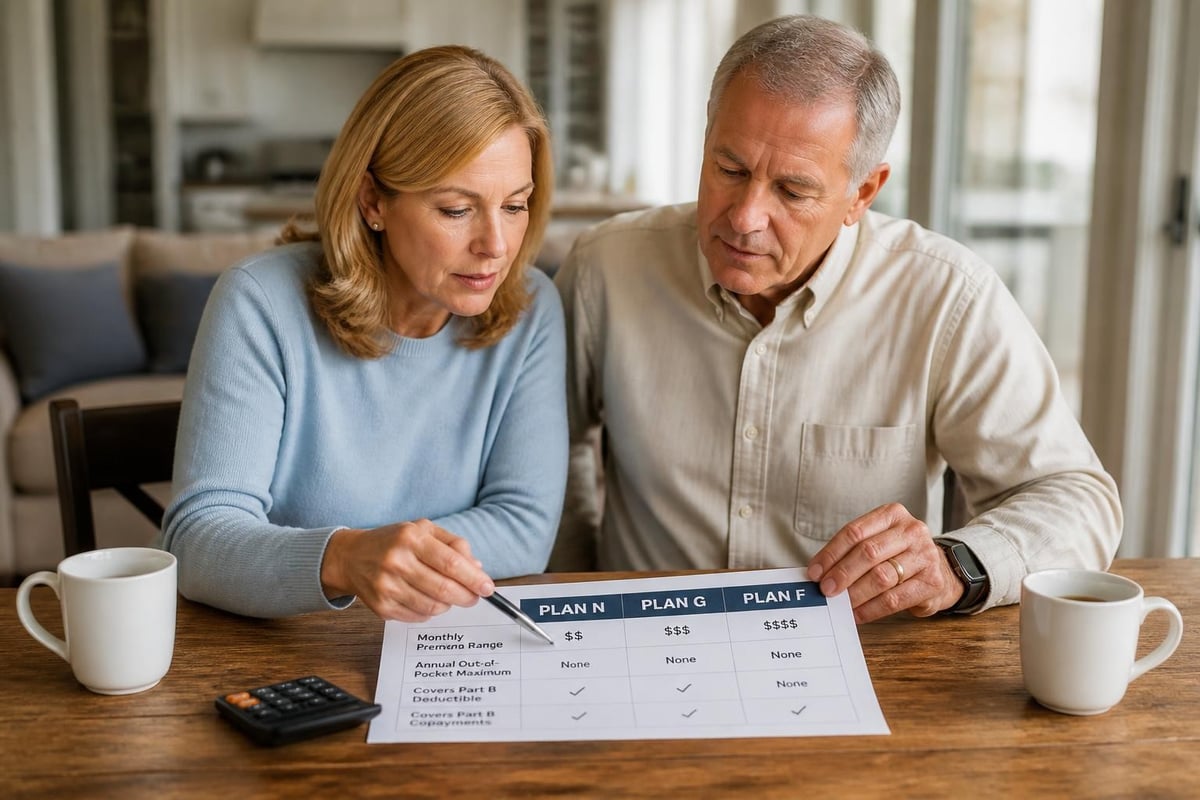
Plan G currently holds the largest market share among newly eligible beneficiaries. The key difference lies in cost-sharing:
Plan G covers the Part B deductible, office visit copays, and emergency room copays. You pay nothing beyond your premium once enrolled. However, Plan G premiums typically run $30-$60 higher monthly than Plan N in most markets.
Plan N requires the Part B deductible and modest copays but offers lower premiums. For someone who visits the doctor six times yearly, the copays total approximately $120 annually-often less than the premium difference between the two plans.
The choice depends on your healthcare utilization and budget preferences. Frequent medical users may prefer Plan G's predictability, while healthier beneficiaries often save money with medicare plan n.
Plan N vs. Plan F
Plan F, once the most popular Medigap option, closed to new Medicare beneficiaries on January 1, 2020. Only those eligible for Medicare before that date can purchase Plan F today.
For those comparing existing Plan F coverage to Plan N:
- Plan F covers the Part B deductible; Plan N does not
- Plan F has no office visit or ER copays; Plan N requires them
- Plan F premiums significantly exceed Plan N premiums
- Both plans offer identical coverage for hospital and skilled nursing costs
Switching from Plan F to Plan N can reduce monthly premiums substantially, but you'll need to budget for the Part B deductible and occasional copays.
Premium Costs and Pricing Factors
Medicare plan n premiums vary considerably based on multiple factors. Understanding these variables helps you find competitive rates in your area.
What Influences Your Premium
Geographic Location: Premiums in the Triad Area reflect regional healthcare costs, competition among carriers, and state insurance regulations. North Carolina beneficiaries should compare multiple carriers serving Greensboro, Kernersville, High Point, and Winston Salem.
Age: Insurance companies use one of three pricing methods:
- Community-rated: Same premium regardless of age
- Issue-age-rated: Premium based on your age when you buy; doesn't increase due to aging
- Attained-age-rated: Premium increases as you age (most common method)
Tobacco Use: Smokers typically pay 15-30% higher premiums than non-smokers for the same coverage.
Household Discounts: Many carriers offer discounts when both spouses enroll in Medigap plans with the same company.
Average Premium Ranges
While specific rates require personalized quotes, national averages provide helpful context:
- Age 65: $90-$140 per month
- Age 70: $110-$165 per month
- Age 75: $130-$190 per month
These represent typical ranges for non-tobacco users. Your actual premium depends on the carrier, pricing method, and any applicable discounts. Shopping among multiple insurers during your initial enrollment period ensures you find competitive rates.
Enrollment Timing and Guaranteed Issue Rights
Federal law provides specific protections for Medicare beneficiaries enrolling in Medigap plans, including medicare plan n. Understanding these rules prevents costly mistakes.
Medigap Open Enrollment Period
Your six-month Medigap Open Enrollment Period begins the month you turn 65 and enroll in Medicare Part B. During this window:
- Insurance companies must sell you any Medigap plan they offer
- They cannot charge more due to pre-existing conditions
- They cannot deny coverage based on health status
- Coverage begins no later than the policy effective date
This represents your best opportunity to purchase Plan N without medical underwriting. Missing this period means insurers can review your health history and potentially deny coverage or charge higher rates.
Guaranteed Issue Situations
Outside the initial enrollment period, federal guaranteed-issue rights protect you in specific situations:
- Your Medicare Advantage plan leaves your area or stops providing care
- You move outside your plan's service area
- Your Medigap insurance company goes bankrupt
- You were misled when purchasing coverage
In these circumstances, you can purchase medicare plan n (or certain other plans) without medical underwriting, regardless of pre-existing conditions.
Medical Underwriting Considerations
If you apply for Plan N outside guaranteed-issue periods, insurance companies typically evaluate your health status. This process varies by state and carrier.
Common Underwriting Questions
Applications generally ask about:
- Current medications and dosages
- Recent hospitalizations or surgeries
- Chronic conditions (diabetes, heart disease, COPD)
- Cancer history within the past 10 years
- Ongoing treatments or upcoming procedures
North Carolina specifics: State regulations may provide additional protections beyond federal requirements. Understanding your state's rules helps you time your application strategically.
Medical Conditions That May Affect Approval
While practices vary by carrier, certain conditions often trigger closer scrutiny:
- Recent heart attack or stroke
- Active cancer treatment
- End-stage renal disease
- Insulin-dependent diabetes with complications
- Oxygen use for respiratory conditions
Some applicants receive conditional offers with exclusions for specific conditions, higher premiums, or outright denials. Working with experienced advisors who understand carrier underwriting guidelines can identify the most receptive insurers for your situation.
For personalized guidance on Medicare Supplement options in the Triad Area, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific health profile and enrollment timing.
Benefits of Choosing Medicare Plan N
Medicare plan n delivers several advantages that make it attractive for many beneficiaries, particularly those who want comprehensive coverage without maximum premiums.
Cost Predictability
The small, fixed copays for doctor visits and emergency room care create predictable budgeting. You know each office visit costs a maximum of $20, making healthcare expenses manageable and transparent.
Unlike Medicare Advantage plans with complex formularies and changing networks, Plan N works with any provider accepting Medicare. This stability extends year after year without annual plan changes.
Provider Freedom
One of the most valuable aspects of Medicare Supplement plans is nationwide provider access. With medicare plan n:
- See any doctor or specialist accepting Medicare
- No referrals required for specialists
- No network restrictions when traveling
- Consistent coverage across all 50 states
This flexibility matters tremendously if you split time between locations, have family in different states, or want confidence that coverage travels with you.
Premium Savings vs. Comprehensive Plans
The premium difference between Plan N and Plan G typically ranges from $360 to $720 annually. For beneficiaries with moderate healthcare needs, the copays rarely exceed this amount, resulting in net savings.
Example calculation:
- Plan G premium: $165/month ($1,980/year)
- Plan N premium: $125/month ($1,500/year)
- Monthly savings: $40 ($480/year)
- Eight doctor visits: $160 in copays
- Part B deductible: $257
- Net additional cost with Plan N: $417 – $480 saved = $63 ahead
Even with regular medical care, Plan N often costs less overall while delivering robust protection against major expenses.
Common Questions About Medicare Plan N
Understanding how medicare plan n handles specific situations helps you evaluate whether it matches your needs.
Does Plan N Cover Excess Charges?
No. Medicare Part B excess charges occur when providers who accept Medicare but don't accept Medicare assignment charge up to 15% above Medicare's approved amount. Plan N doesn't cover these charges.
However, excess charges affect relatively few beneficiaries. According to CMS data, fewer than 5% of providers nationwide charge excess fees, and some states prohibit them entirely. You can avoid excess charges by confirming providers accept Medicare assignment before appointments.
Can You Switch from Plan N to Another Medigap Plan?
Yes, you can apply to switch at any time. However, outside guaranteed-issue periods, insurance companies can require medical underwriting. Your health status may affect approval, premiums, or both.
The best strategy involves purchasing the right plan initially during your Medigap Open Enrollment Period when guaranteed-issue rights apply. Changes later may prove difficult or expensive depending on your health.
How Does Plan N Work with Medicare Part D?
Medicare plan n doesn't include prescription drug coverage. You'll need a separate Part D plan for medications. The State Health Insurance Assistance Program (SHIP) offers free counseling to help you compare Part D options alongside your Medigap choice.
Combining Plan N with an appropriate Part D plan creates comprehensive coverage for both medical care and prescriptions at a predictable total cost.
What Happens If You Travel Internationally?
Plan N includes foreign travel emergency coverage after a $250 deductible. The plan pays 80% of medically necessary emergency care during the first 60 days of a trip, with a $50,000 lifetime maximum.
This benefit provides valuable protection for international travelers, though those taking extended trips should consider supplemental travel medical insurance for comprehensive coverage.
Factors to Consider Before Enrolling
Selecting medicare plan n requires evaluating your specific circumstances, health needs, and financial priorities. Several key considerations influence whether Plan N represents your best choice.
Healthcare Utilization Patterns
Review your typical medical care:
- Frequent office visits: If you see doctors monthly or more, the $20 copays accumulate. Calculate your annual total and compare against premium differences with Plan G.
- Minimal care needs: Healthy beneficiaries who visit doctors only for preventive care maximize Plan N's value through premium savings.
- Specialist care: Complex conditions requiring multiple specialists generate more copays, though the $20 maximum per visit maintains affordability.
Budget Considerations
Balancing monthly premiums against occasional out-of-pocket costs depends on your financial situation:
Fixed income beneficiaries often prefer consistent monthly expenses. Plan G's higher premium but zero copays may suit this preference better than Plan N's lower premium with variable copays.
Flexible budget holders typically find Plan N's structure works well. The modest copays remain manageable while monthly premium savings provide immediate relief.
Future Healthcare Needs
While you cannot predict medical needs perfectly, reasonable assumptions help:
- Family health history suggests potential conditions
- Existing chronic conditions may require ongoing monitoring
- Age-related healthcare typically increases over time
Medicare plan n serves beneficiaries well across changing health needs. The plan's comprehensive hospital and skilled nursing coverage protects against major expenses regardless of how health evolves.
Regional Considerations in North Carolina
North Carolina beneficiaries should understand state-specific factors affecting medicare plan n enrollment and costs.
Available Carriers in the Triad Area
Multiple insurance companies offer Plan N in Greensboro, Kernersville, High Point, and Winston Salem. Comparing carriers ensures competitive pricing:
- Different companies use different pricing methods
- Premium differences for identical coverage can exceed $50 monthly
- Customer service quality and claim processing vary
- Some carriers offer additional member benefits
Shopping multiple carriers during your enrollment period maximizes value. Remember, Plan N benefits are standardized-you're comparing premiums and service, not coverage differences.
State Regulations and Protections
North Carolina insurance regulations provide consumer protections beyond federal minimums. Understanding these rules helps you navigate enrollment:
- Rate increase approval requirements
- Complaint resolution processes
- Licensing and solvency standards for carriers
- Consumer assistance resources
The North Carolina Department of Insurance offers resources for beneficiaries comparing Medigap options, including Plan N.
Making Your Decision
Choosing medicare plan n involves weighing multiple factors simultaneously. A structured decision process helps clarify your best path forward.
Decision Framework
- Calculate total costs: Premium plus estimated annual copays for your typical care patterns
- Compare alternatives: Run the same calculation for Plan G and any other plans you're considering
- Evaluate provider preferences: Confirm your doctors accept Medicare assignment to avoid excess charges
- Consider budget style: Determine whether you prefer lower monthly costs or maximum predictability
- Review guarantee periods: Time your application to maximize guaranteed-issue protections
Getting Personalized Guidance
According to research published by the Medicare Rights Center, many beneficiaries struggle with Medigap decisions due to complexity and aggressive marketing. Working with knowledgeable advisors who explain options without pressure makes the process significantly easier.
Moser Insurance Group Inc specializes in helping individuals throughout the Triad Area understand their Medicare options. We explain how medicare plan n compares to alternatives based on your specific situation, not generic sales pitches.
Important Deadlines
Mark these critical dates:
- Three months before turning 65: Your Medicare Initial Enrollment Period begins
- The month you turn 65 and enroll in Part B: Your Medigap Open Enrollment Period starts
- Six months later: Your guaranteed-issue rights for Medigap end
Missing these windows can result in medical underwriting, higher premiums, or coverage denials. Plan ahead to ensure you enroll during optimal timing.
Long-Term Value of Medicare Plan N
Beyond immediate costs, medicare plan n delivers lasting benefits that extend throughout retirement.
Rate Stability
While all Medigap premiums increase over time, Plan N has demonstrated relative stability. The Congressional Research Service analysis notes that plans with modest cost-sharing often show slower premium growth than plans covering every dollar.
This trend reflects that beneficiaries who pay small copays use healthcare slightly more judiciously than those with zero cost-sharing. Insurance companies price this behavior into their rates, potentially moderating increases.
Flexibility for Changing Needs
Medicare plan n adapts well to evolving circumstances:
- Coverage remains consistent if you move to different states
- Benefits don't change when you develop new health conditions
- Provider access continues without network restrictions
- The plan coordinates seamlessly if you add Part D coverage or adjust your prescription plan
This flexibility provides peace of mind as life circumstances shift throughout retirement.
Comprehensive Protection
The aspects medicare plan n covers-hospital stays, skilled nursing, hospice care-represent the most financially devastating potential expenses. The small copays pale in comparison to the hundreds of thousands in potential costs the plan protects you from.
Beneficiaries with Plan N enjoy protection against:
- Extended hospital stays costing tens of thousands in coinsurance
- Skilled nursing facility care at $200+ daily for coinsurance
- The Part A deductible exceeding $1,600 per benefit period
- Part B coinsurance typically running 20% of approved amounts
This comprehensive protection, combined with reasonable premiums and modest predictable copays, positions Plan N as a balanced, sustainable choice for many Medicare beneficiaries.
Visit moserinsurancegroup.com or call 336-862-1763 to explore how Medicare Plan N fits your specific healthcare and budget needs in the Greensboro, Kernersville, High Point, or Winston Salem area.
Medicare Plan N offers comprehensive coverage with modest cost-sharing that delivers excellent value for many beneficiaries, particularly those seeking lower premiums while maintaining strong protection against major medical expenses. The plan's standardized benefits, nationwide provider access, and predictable copayments create a sustainable long-term solution. Moser Insurance Group Inc helps individuals and families in the Triad Area understand how Medicare Plan N compares to other options through clear, personalized guidance-so you can make confident insurance decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Medicare supplement options today.
Recent Comments