

Planning for end-of-life expenses is one of the most thoughtful gifts you can give your family. Final expense whole life insurance offers a straightforward solution to cover funeral costs, outstanding medical bills, and other expenses that arise after someone passes away. Unlike traditional whole life policies designed for large estates, these specialized plans focus on smaller benefit amounts tailored specifically to cover burial, cremation, and related costs. This type of coverage ensures your loved ones won't face financial hardship during an already difficult time, and it provides guaranteed protection that never expires as long as premiums are paid.
Understanding Final Expense Whole Life Insurance
Final expense whole life insurance is a permanent life insurance product designed to cover end-of-life costs, typically ranging from $5,000 to $35,000 in coverage. These policies remain in force for your entire lifetime, with premiums that never increase and death benefits that won't decrease. The application process is usually simplified, making it accessible to seniors and individuals who might struggle to qualify for traditional life insurance.
According to industry data on final expense insurance trends, the final expense market has grown significantly, with new annualized premium increasing 16% in 2024. This growth reflects the increasing awareness among Americans about the importance of planning for funeral and burial costs.
Key Features That Set It Apart
Final expense whole life insurance differs from standard whole life policies in several important ways:
- Lower coverage amounts: Typically $5,000 to $35,000 rather than $100,000+
- Simplified underwriting: Many policies require only health questions, no medical exam
- Guaranteed acceptance options: Some plans accept all applicants within age ranges
- Fixed premiums: Monthly payments never increase regardless of age or health changes
- Fast payout: Benefits often paid within days to cover immediate expenses
The simplified application process makes these policies particularly valuable for individuals ages 50-85 who may have pre-existing health conditions. While whole life insurance traditionally requires extensive medical underwriting, final expense policies prioritize accessibility.
The Real Cost of Final Expenses
Understanding what final expense whole life insurance needs to cover helps determine appropriate coverage amounts. Consumer Reports explains funeral planning costs in detail, revealing that the median cost of a funeral with viewing and burial reached $7,848 in 2024, while cremation with a memorial service averaged $6,971.
However, funeral home costs represent just part of the total picture. Additional expenses accumulate quickly:
| Expense Category | Typical Cost Range |
|---|---|
| Funeral home services | $2,000 – $4,000 |
| Casket or urn | $1,000 – $10,000+ |
| Cemetery plot | $1,000 – $4,000 |
| Headstone or marker | $1,500 – $3,500 |
| Flowers and memorial | $300 – $1,500 |
| Outstanding medical bills | Varies widely |
| Legal and administrative fees | $500 – $2,000 |
In the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, these costs often align with or exceed national averages. Families face additional expenses like travel costs for out-of-town relatives, meals for guests, and potential lost income while handling estate matters.
Hidden Costs Families Often Overlook
Beyond the obvious funeral and burial expenses, several additional costs catch families unprepared:
Immediate financial obligations include final mortgage or rent payments, utility bills, credit card debts, and outstanding loans. Many people also leave behind unpaid medical bills from their final illness, which can total thousands of dollars depending on the circumstances.
Estate settlement costs encompass probate fees, attorney expenses, executor compensation, and tax preparation. Even modest estates face these administrative burdens, and without designated funds, families must cover these costs out-of-pocket while waiting for estate assets to become available.
How Final Expense Whole Life Insurance Works
The mechanics of final expense whole life insurance are intentionally straightforward. You apply for a policy, answer health questions (and sometimes undergo a brief phone interview), and receive approval often within 24-48 hours. Once approved, you select your coverage amount and pay your first premium.
The Application Process
Most final expense applications can be completed in 15-30 minutes. The process typically unfolds in these steps:
- Choose your coverage amount based on estimated expenses
- Answer health questions about current conditions and medications
- Review premium quotes for your age and health status
- Select payment frequency (monthly, quarterly, or annual)
- Designate beneficiaries who will receive the death benefit
- Submit application for immediate review and approval
At Moser Insurance Group Inc, we help clients in the Triad Area navigate this process with personalized guidance, ensuring they understand every detail before making a decision. You can reach us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation.
Premium Structures and Payment Options
Final expense whole life insurance premiums remain fixed for life once the policy is issued. Your monthly payment depends on several factors including age at application, coverage amount, health status, and whether you choose guaranteed acceptance or simplified issue underwriting.
Typical monthly premiums for a healthy 65-year-old seeking $10,000 in coverage range from $35 to $85, while a 75-year-old might pay $70 to $150 for the same benefit. Guaranteed acceptance policies, which don't require health questions, carry higher premiums due to increased risk for the insurance company.
Payment flexibility allows policyholders to choose monthly, quarterly, semi-annual, or annual payment schedules. Many insurers offer slight discounts for annual payments, and some provide automatic bank draft discounts of 5-10%.
Types of Final Expense Policies
Not all final expense whole life insurance policies offer identical features. Understanding the differences helps you select the right coverage for your circumstances and budget.
Simplified Issue Policies
Simplified issue policies require answering health questions but no medical examination. These represent the most common type of final expense coverage, offering competitive premiums for applicants in reasonably good health.
Advantages include faster approval, affordable premiums for healthy individuals, immediate full death benefit coverage, and access to higher coverage amounts (up to $35,000 or more).
Considerations involve potential denial based on health answers, higher premiums than fully underwritten traditional policies, and more detailed health questions than guaranteed acceptance options.
Guaranteed Acceptance Policies
Guaranteed acceptance (also called guaranteed issue) policies accept all applicants within specified age ranges, typically 50-85. No health questions are asked, and approval is automatic.
These policies typically include a graded death benefit period, usually two or three years. If the insured dies from illness during this period, beneficiaries receive only the premiums paid plus interest (often 10%). After the graded period, the full death benefit pays regardless of cause of death. Accidental death usually pays the full benefit immediately from day one.
| Feature | Simplified Issue | Guaranteed Acceptance |
|---|---|---|
| Health questions | Yes | No |
| Medical exam | No | No |
| Approval rate | 70-90% | 100% (within age limits) |
| Premium cost | Lower | Higher |
| Immediate full benefit | Yes | Only for accidents |
| Graded period | No | Yes (2-3 years) |
| Age limits | Usually 40-80 | Usually 50-85 |
Modified or Graded Benefit Structures
The graded benefit structure protects insurance companies from adverse selection while providing coverage to individuals who might otherwise be uninsurable. During the graded period (typically two or three years), death from natural causes results in return of premiums plus interest rather than the full death benefit.
Example scenario: A 70-year-old purchases a $15,000 guaranteed acceptance policy with a two-year graded period at $85 monthly. If she passes away 18 months later from heart disease, beneficiaries receive the $1,530 in premiums paid plus 10% interest. If she passes away after 25 months, beneficiaries receive the full $15,000 benefit.
This structure makes coverage accessible to individuals with serious health conditions while managing risk for the insurance company. For many families in Greensboro, Kernersville, High Point, and Winston Salem, this accessibility proves invaluable when traditional coverage isn't available.
Tax Benefits and Beneficiary Considerations
One of the most significant advantages of final expense whole life insurance involves its favorable tax treatment. According to IRS guidance on decedent taxation, life insurance death benefits generally pass to beneficiaries completely income-tax-free.
Tax Advantages for Beneficiaries
Income tax exemption means your beneficiaries receive the full death benefit without reporting it as taxable income. A $15,000 benefit pays out exactly $15,000, with no portion withheld for federal or state income taxes.
Estate tax considerations become relevant only for very large estates. For 2026, the federal estate tax exemption stands at $13.61 million per individual ($27.22 million for married couples). Final expense policies rarely push estates above these thresholds, meaning most beneficiaries face no estate tax consequences.
Cash value growth inside the policy accumulates tax-deferred. While final expense policies build cash value more slowly than larger whole life policies due to their smaller face amounts, any growth isn't taxed unless you surrender the policy for more than you've paid in premiums.
Naming and Updating Beneficiaries
Properly designating beneficiaries ensures your final expense whole life insurance serves its intended purpose. Primary beneficiaries receive the death benefit first, while contingent (or secondary) beneficiaries receive it only if primary beneficiaries predecease you or cannot be located.
Best practices include:
- Name specific individuals rather than "my children" or "my estate"
- Include full legal names, Social Security numbers, and relationships
- Specify percentage splits if multiple beneficiaries (e.g., 50% each to two children)
- Name contingent beneficiaries to avoid probate if primary beneficiaries can't collect
- Review and update beneficiaries after major life events (marriage, divorce, births, deaths)
- Keep a copy of beneficiary designations with important papers
Avoid naming your estate as beneficiary unless absolutely necessary, as this subjects the death benefit to probate, delays, creditor claims, and potential estate taxes. Visit moserinsurancegroup.com for personalized guidance on beneficiary designation strategies.
Comparing Final Expense to Other Coverage Options
Several alternatives to final expense whole life insurance exist, each with distinct advantages and limitations. Understanding how they compare helps determine the best approach for your situation.
Pre-Need Funeral Insurance
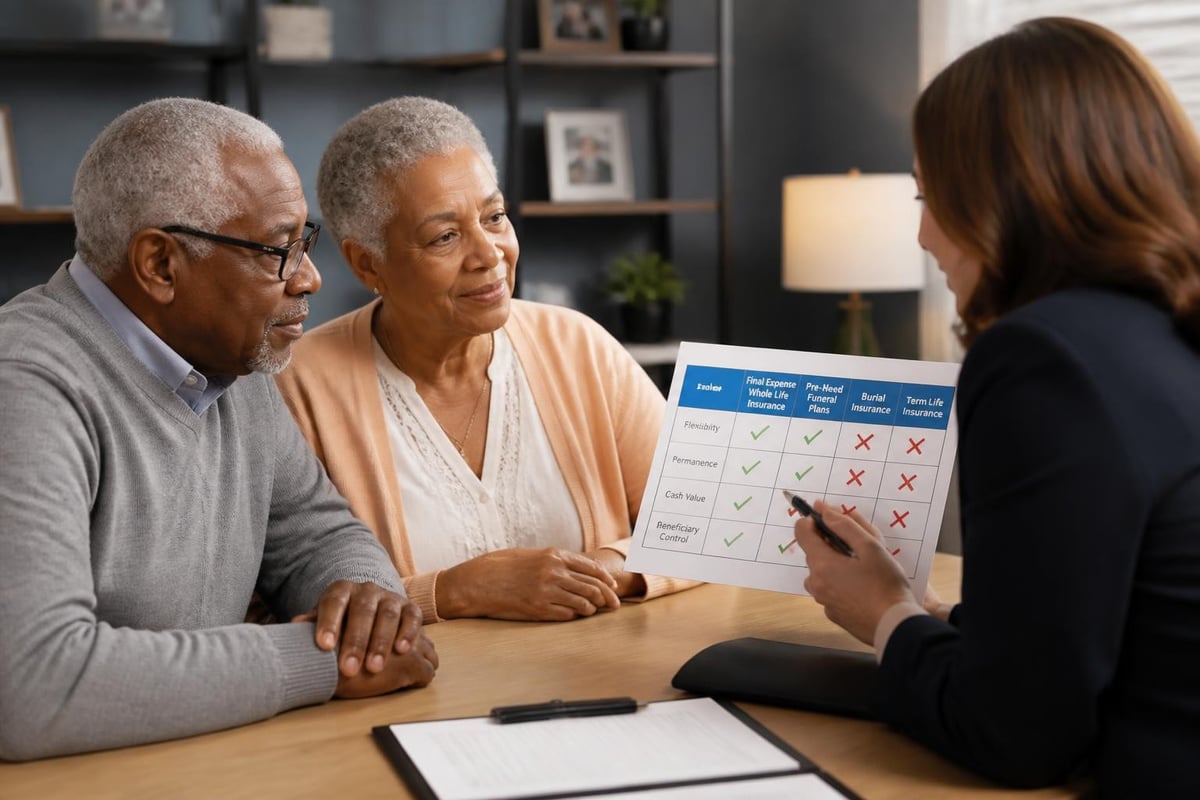
Pre-need policies are sold directly through funeral homes and pay benefits directly to the funeral home rather than your beneficiaries. These policies lock in current funeral costs, protecting against inflation, but offer limited flexibility.
Limitations include restriction to one funeral home (creating issues if you relocate), potential loss of benefits if the funeral home closes, lack of refunds if you change your mind, and no cash value for beneficiaries if actual costs are lower than the policy amount.
Final expense whole life insurance provides much greater flexibility, allowing beneficiaries to choose any funeral home and use excess funds for other needs.
Burial Insurance vs. Final Expense Insurance
The terms "burial insurance" and "final expense insurance" are often used interchangeably, though some providers distinguish between them. Burial insurance traditionally refers to smaller policies ($5,000-$10,000) focused solely on burial costs, while final expense insurance encompasses broader end-of-life expenses with higher coverage options.
Both operate as whole life insurance products with the features described throughout this article. The naming difference relates more to marketing than substantive policy differences.
Term Life Insurance for Final Expenses
Some families consider term life insurance to cover final expenses, particularly younger individuals who want affordable coverage. While term policies offer higher coverage amounts at lower initial premiums, they carry significant drawbacks for final expense planning:
- Coverage expires: Term policies end after 10, 20, or 30 years, potentially leaving you uninsured in your 80s and 90s when final expenses actually occur
- Increasing renewal costs: Renewing expired term coverage at advanced ages becomes prohibitively expensive
- No cash value: Term insurance builds no savings component
- Approval challenges: Older applicants face difficult underwriting for new term policies
For individuals specifically focused on funeral and burial costs, final expense whole life insurance provides more appropriate coverage that can't be outlived.
When Final Expense Whole Life Insurance Makes Sense
This coverage type proves particularly valuable in specific circumstances and for certain demographic groups. Understanding when it provides optimal benefits helps you make informed decisions.
Ideal Candidates for Final Expense Coverage
Seniors ages 50-85 represent the primary market for final expense whole life insurance. These individuals have accumulated enough life experience to recognize the burden funeral costs place on families, yet may struggle to qualify for traditional life insurance due to age or health conditions.
Individuals with pre-existing conditions find final expense policies accessible when other coverage isn't. Simplified issue policies accept many conditions that would trigger denials from traditional insurers, while guaranteed acceptance options eliminate medical underwriting entirely.
Those seeking modest, affordable coverage benefit from the lower face amounts and proportionally lower premiums. If you need $10,000-$25,000 in coverage rather than $250,000, final expense policies offer appropriate sizing without paying for unnecessary coverage.
People who value guaranteed premiums appreciate the budget certainty final expense whole life insurance provides. Fixed monthly payments never increase, making long-term financial planning easier for retirees on fixed incomes throughout the Triad Area.
Situations Where Other Coverage Works Better
Final expense whole life insurance isn't always the optimal choice. Younger, healthy individuals needing substantial coverage to protect mortgages or replace income should consider traditional term or whole life insurance instead, which offers better value for larger coverage amounts.
Similarly, individuals with significant assets might prefer self-funding final expenses rather than paying insurance premiums. If you've accumulated substantial savings and have no estate liquidity concerns, setting aside designated funds might cost less over time than insurance premiums.
Regulatory Protections and Consumer Safeguards
Final expense whole life insurance operates under comprehensive regulatory oversight designed to protect consumers. The National Association of Insurance Commissioners provides detailed guidance on life insurance products, including model regulations that many states adopt.
State Insurance Department Oversight
Every state maintains an insurance department that licenses insurers, approves policy forms, regulates marketing practices, and handles consumer complaints. Before purchasing final expense coverage, verify that the insurer is licensed in North Carolina and maintains good standing with the state insurance department.
Free look periods, mandated by state law, allow you to cancel a new policy within a specified timeframe (typically 10-30 days) and receive a full refund of premiums paid. This protection lets you review policy documents carefully and reconsider your decision without financial penalty.
Understanding Your Rights as a Policyholder
Life Happens provides consumer-focused education about life insurance rights and responsibilities. Key protections include the right to clear policy disclosure, honest answers to your questions, privacy of your personal information, and fair claims handling.
The Federal Trade Commission’s Funeral Rule complements insurance protections by requiring funeral providers to give detailed price information, preventing them from requiring customers to buy packages, and protecting consumers from deceptive practices. Understanding these rights helps you make informed decisions about both insurance coverage and eventual funeral arrangements.
Cost Factors and Premium Determinants
Multiple variables influence final expense whole life insurance premiums. Understanding these factors helps you anticipate costs and potentially reduce premiums through strategic timing and policy selection.
Primary Rating Factors
Age at application represents the single most significant premium determinant. Insurers use actuarial tables showing life expectancy by age, with older applicants paying substantially more than younger ones for identical coverage. A 60-year-old might pay $45 monthly for $10,000 in coverage, while a 75-year-old pays $95 for the same benefit.
Health status and medical history affect premiums for simplified issue policies. Specific conditions like diabetes, heart disease, cancer history, or COPD may increase premiums or trigger denials. Guaranteed acceptance policies eliminate this variable but charge higher baseline premiums to all applicants.
Coverage amount and type directly impact monthly costs. Higher face amounts require proportionally higher premiums, while guaranteed acceptance policies cost more than simplified issue policies for the same coverage amount.
Gender creates premium differences, with women typically paying slightly less than men at the same age due to longer average life expectancy.
Tobacco use significantly increases premiums across all life insurance types, including final expense policies. Insurers typically charge tobacco users 50-100% more than non-tobacco users.
Strategies to Minimize Premiums
Several approaches can help reduce final expense whole life insurance costs:
- Apply earlier: Premiums increase with age, so applying at 62 costs less than waiting until 70
- Quit tobacco: Most insurers offer non-tobacco rates after 12 months tobacco-free
- Compare multiple carriers: Premium differences of 30-50% exist between insurers for identical coverage
- Choose annual payments: Annual or semi-annual payment modes often receive discounts
- Right-size coverage: Buy only what you need; every $1,000 in coverage adds to monthly premiums
Working with an experienced advisor at Moser Insurance Group Inc helps identify the most competitive options for your specific situation. Call 336-862-1763 to discuss strategies for maximizing value while minimizing cost.
Cash Value Accumulation and Policy Loans
While final expense whole life insurance focuses primarily on death benefit protection, these policies do accumulate modest cash value over time. Understanding how cash value works helps you utilize this feature if needed while maintaining appropriate coverage.
How Cash Value Grows
A portion of each premium payment goes toward building cash value inside the policy. This cash value grows tax-deferred at rates specified in the policy, typically 2-4% annually. The accumulation starts slowly, as initial premiums cover policy acquisition costs and administrative expenses, then accelerates over time.
Due to their smaller face amounts and higher proportional costs, final expense policies build cash value more slowly than larger whole life policies. A $10,000 final expense policy might accumulate $1,500-$2,500 in cash value after 10 years, while a $250,000 whole life policy would build substantially more.
Accessing Cash Value Through Policy Loans
Most final expense whole life insurance policies allow you to borrow against accumulated cash value. These loans don't require credit checks or approval processes, and you can use the funds for any purpose.
Important loan considerations:
- Loan interest (typically 5-8% annually) accrues against the outstanding balance
- Unpaid loans reduce the death benefit dollar-for-dollar if not repaid
- Excessive loans can cause policy lapse if cash value is depleted
- Loan repayment is optional but recommended to preserve full death benefit
- Surrendering a policy with outstanding loans may create taxable income
Policy loans provide emergency access to funds while keeping coverage in force, but should be used judiciously to avoid unintentionally reducing the benefit available to beneficiaries.
Making an Informed Decision
Selecting the right final expense whole life insurance requires careful evaluation of your circumstances, needs, and available options. A systematic approach ensures you choose coverage that truly serves your goals.
Questions to Ask Before Buying
Coverage amount determination: Calculate total anticipated expenses including funeral costs, burial or cremation, outstanding debts, medical bills, and estate administration. Add 10-20% buffer for unexpected costs or inflation.
Policy type selection: Assess whether you qualify for simplified issue policies based on your health, or whether guaranteed acceptance better suits your situation. Compare premiums and graded benefit periods across options.
Insurer financial strength: Research the insurance company's financial ratings from agencies like A.M. Best, Moody's, and Standard & Poor's. Look for ratings of A- or higher, indicating strong financial stability and claims-paying ability.
Premium affordability: Confirm that monthly premiums fit comfortably in your budget for the long term. Remember that whole life premiums continue for life; a policy that strains your finances now becomes unsustainable over time.
Working with Knowledgeable Advisors
Industry research from LIMRA consistently shows that working with insurance professionals increases satisfaction and reduces the likelihood of purchasing inadequate or inappropriate coverage. Advisors help navigate complex product differences, explain underwriting requirements, and identify competitive pricing.
When selecting an advisor, look for individuals who:
- Represent multiple insurance carriers to offer comparative options
- Take time to understand your specific needs rather than pushing products
- Explain policy features, limitations, and costs transparently
- Provide educational resources without high-pressure sales tactics
- Maintain appropriate state licensing and professional credentials
In High Point, Winston Salem, and throughout the Triad Area, Moser Insurance Group Inc provides this type of client-focused guidance. Our approach emphasizes education and personalized support, helping you make confident decisions about final expense coverage and other insurance needs. For more information about our services, visit moserinsurancegroup.com.
Common Myths and Misconceptions
Several persistent myths about final expense whole life insurance create confusion and sometimes prevent people from securing valuable coverage. Clearing up these misunderstandings helps you make decisions based on accurate information.
"Medicare or Medicaid Covers Funeral Costs"
This represents one of the most common misconceptions. Medicare does not provide any death benefit or funeral expense coverage. Medicaid may offer minimal funeral assistance in some states (typically $1,000-$2,500), but this varies by state, requires specific eligibility criteria, and falls far short of actual funeral costs.
Families relying on Medicare or Medicaid to cover final expenses face significant out-of-pocket costs averaging $7,000-$10,000 or more. Final expense whole life insurance fills this gap, ensuring designated funds are available regardless of government program limitations.
"I'm Too Old to Get Coverage"
Many seniors assume they've aged out of life insurance eligibility, but final expense policies specifically target individuals ages 50-85. Guaranteed acceptance policies, in particular, provide options for seniors who believe their age or health makes insurance impossible.
While premiums increase with age, coverage remains accessible and valuable even for individuals in their 70s and 80s. The key is comparing your premium costs against the expenses your family will otherwise face.
"My Savings Can Cover Everything"
Some individuals with modest savings believe dedicated insurance is unnecessary. However, several factors make final expense whole life insurance valuable even with available savings:
Liquidity timing: Estate assets often remain frozen during probate for months, while funeral expenses require immediate payment. Insurance benefits typically pay within days, providing immediate funds.
Asset preservation: Using insurance to cover final expenses preserves savings and investments for beneficiaries' other needs or inheritance.
Guaranteed payout: Savings can be depleted by market downturns, long-term care costs, or unexpected expenses during your lifetime. Insurance provides guaranteed funds regardless of what happens to other assets.
Simplicity: Life insurance pays directly to beneficiaries outside probate, avoiding legal fees, delays, and complications of estate settlement.
"Guaranteed Acceptance Means I'm Overpaying"
While guaranteed acceptance policies do carry higher premiums than simplified issue coverage, they serve an important purpose for individuals who couldn't otherwise obtain coverage. The increased cost reflects increased risk to the insurance company from accepting all applicants without medical screening.
For someone with serious health conditions who would be declined by simplified issue policies, guaranteed acceptance represents the only available option. In this context, the premium reflects appropriate pricing for the coverage provided, not overcharging.
The Claims Process and Beneficiary Support
Understanding how final expense whole life insurance death benefits are paid helps ensure smooth, timely settlement when your family needs funds most. The claims process is designed for efficiency during a difficult time.
Filing a Death Claim
When a policyholder passes away, beneficiaries or their representatives must notify the insurance company and file a death claim. This process typically requires:
- Contacting the insurance company via phone or online claim portal
- Completing a claim form with policy information and death details
- Providing a certified death certificate from the state vital records office
- Submitting beneficiary identification such as Social Security number and photo ID
- Choosing payment method (direct deposit, check, or retained asset account)
Most insurance companies process complete claims within 7-14 business days, though some offer expedited processing in as little as 24-48 hours for final expense policies specifically.
Payment Options for Beneficiaries
Beneficiaries typically receive benefits through one of several methods:
Lump sum payment represents the most common choice, providing the full death benefit in a single payment via check or direct deposit. This allows beneficiaries to immediately pay funeral expenses and other obligations.
Retained asset accounts function like checking accounts managed by the insurance company, where the full benefit is deposited and beneficiaries can write checks or make transfers as needed. This provides immediate access while earning modest interest on unused funds.
Installment payments allow beneficiaries to receive the death benefit in scheduled payments over months or years, which can help with budgeting and reduce the temptation to spend the full amount quickly.
What Beneficiaries Should Know
Prompt notification to the insurance company starts the claims process and prevents delays. Beneficiaries should locate the policy documents, contact information, and policy number as soon as possible after a death occurs.
Multiple death certificates should be ordered initially (typically 5-10 certified copies), as various institutions require originals. These cost $10-25 each depending on your state.
Tax reporting is generally not required for life insurance death benefits, as they're received income-tax-free. However, any interest earned on retained asset accounts is taxable income and will be reported on Form 1099-INT.
Unclaimed benefits remain a surprising problem, with billions in life insurance proceeds going unclaimed because beneficiaries don't know policies exist. Inform beneficiaries about your coverage and store policy information where it can be easily found. Consider providing copies to beneficiaries or your attorney.
Final expense whole life insurance provides guaranteed, affordable protection that covers funeral costs, outstanding bills, and end-of-life expenses, ensuring your loved ones aren't burdened financially during an already challenging time. Whether you need simplified issue coverage or guaranteed acceptance options, the right policy offers peace of mind and practical support when it matters most. Moser Insurance Group Inc helps individuals and families throughout Greensboro, Kernersville, High Point, Winston Salem, and the Triad Area understand their final expense insurance options with personalized guidance and educational support. Reach out to us at 336-862-1763, moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss how final expense coverage fits into your overall financial plan with no pressure, just clear answers to your questions.
Recent Comments