
Understanding annuity general concepts is essential for anyone planning a secure retirement. An annuity general framework encompasses the basic principles, structures, and benefits of annuity products that provide guaranteed income streams during retirement years. For individuals and families in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, grasping these foundational concepts helps make informed financial decisions that align with long-term goals. Whether you're approaching retirement or already navigating Medicare and insurance choices, understanding how annuities work within the broader financial landscape can provide clarity and confidence. For personalized guidance on your retirement and insurance options, contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com.
What Is Annuity General and Why It Matters
Annuity general refers to the overarching framework and fundamental principles that govern how annuity products function within retirement planning. At its core, an annuity is a contract between an individual and an insurance company designed to provide regular income payments over a specified period or for life. The annuity general structure addresses critical retirement concerns: outliving your savings, market volatility, and predictable income needs.
The National Association of Insurance Commissioners provides comprehensive resources that outline the regulatory framework and consumer protections surrounding these products. These safeguards ensure that annuity general principles remain consistent across different insurance providers and product variations.
Core Components of Annuity Structure
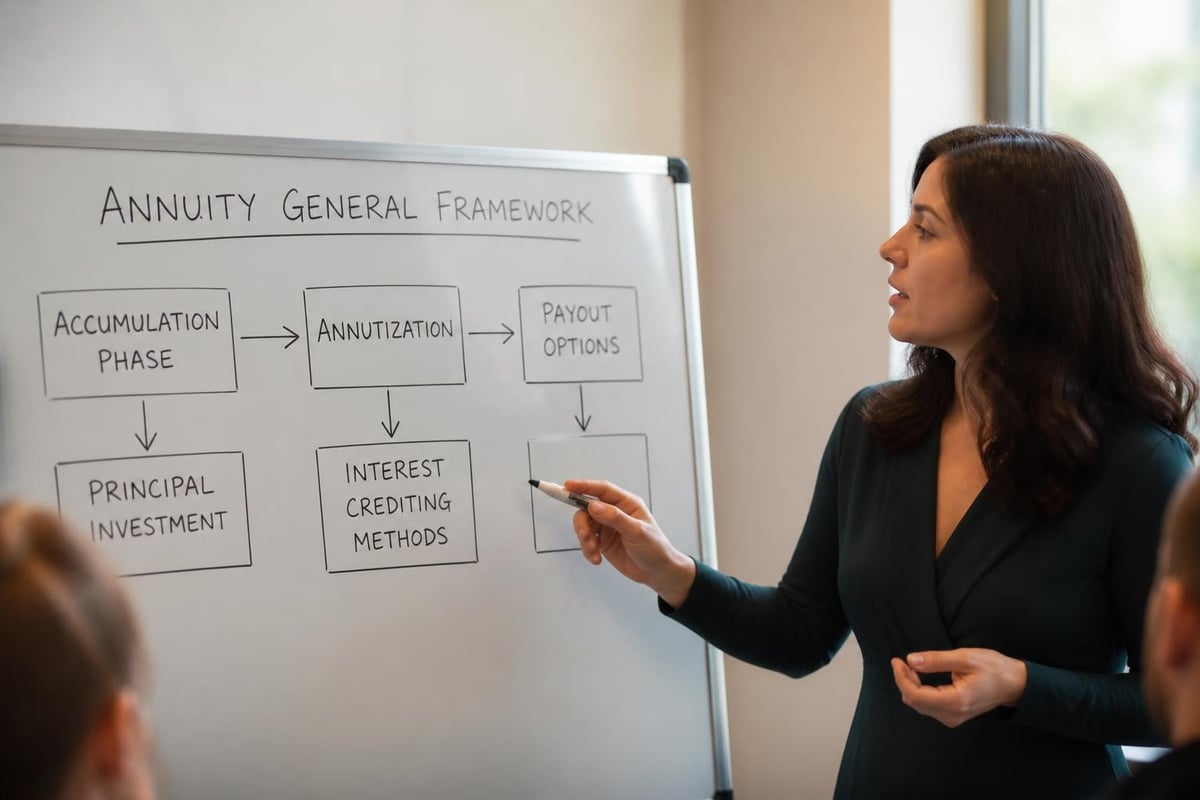
Understanding annuity general mechanics requires familiarity with several key components:
- Accumulation phase: The period when you contribute funds to the annuity
- Annuitization phase: When the annuity begins making regular payments to you
- Principal: The initial amount invested in the annuity contract
- Interest crediting: How your annuity grows during the accumulation phase
- Payout options: The various ways you can receive income from your annuity
The annuity general framework establishes rules for each of these components, creating standardized expectations while allowing for product customization.
Types of Annuities Within the General Framework
The annuity general category encompasses multiple product types, each serving different retirement needs and risk tolerances. Understanding these distinctions helps match the right annuity type to your specific situation.
Fixed Annuities
Fixed annuities guarantee a specific interest rate for a predetermined period. The insurance company assumes all investment risk, providing stability and predictability. These products appeal to conservative investors who prioritize capital preservation over aggressive growth.
Key features include:
- Guaranteed minimum interest rate
- Principal protection from market downturns
- Predictable accumulation value
- Tax-deferred growth until withdrawal
Variable Annuities
Variable annuities allow you to invest in sub-accounts similar to mutual funds. Your accumulation value fluctuates based on market performance, offering growth potential with corresponding risk exposure.
| Feature | Fixed Annuity | Variable Annuity |
|---|---|---|
| Investment Risk | Insurance company | Contract holder |
| Growth Potential | Limited to fixed rate | Unlimited market upside |
| Principal Protection | Yes | No (unless rider purchased) |
| Fees | Lower | Higher due to investment options |
Indexed Annuities
Indexed annuities represent a middle ground, linking returns to a market index while providing downside protection. The annuity general principles apply, but with unique crediting methods based on index performance.
Immediate vs. Deferred Annuities
The annuity general classification system distinguishes between when income payments begin, fundamentally affecting how these products fit into retirement planning.
Immediate Annuities
Immediate annuities start paying income within one year of purchase, typically within 30 days. You exchange a lump sum for guaranteed income, converting assets into an income stream.
Common use cases:
- Recent retirees needing immediate income
- Pension rollover strategies
- Structured settlement planning
- Creating predictable monthly cash flow
Deferred Annuities
Deferred annuities postpone income payments to a future date, allowing tax-deferred accumulation. Most individuals purchase deferred annuities during their working years, planning for retirement decades ahead.
The Financial Industry Regulatory Authority explains how deferred annuities work and what investors should consider before purchasing. This resource highlights important fee structures and surrender periods that impact long-term value.
For individuals in the Triad Area considering retirement planning alongside Medicare Supplement plans, understanding how annuity general concepts integrate with healthcare coverage creates a comprehensive retirement strategy.
Tax Treatment Under Annuity General Rules
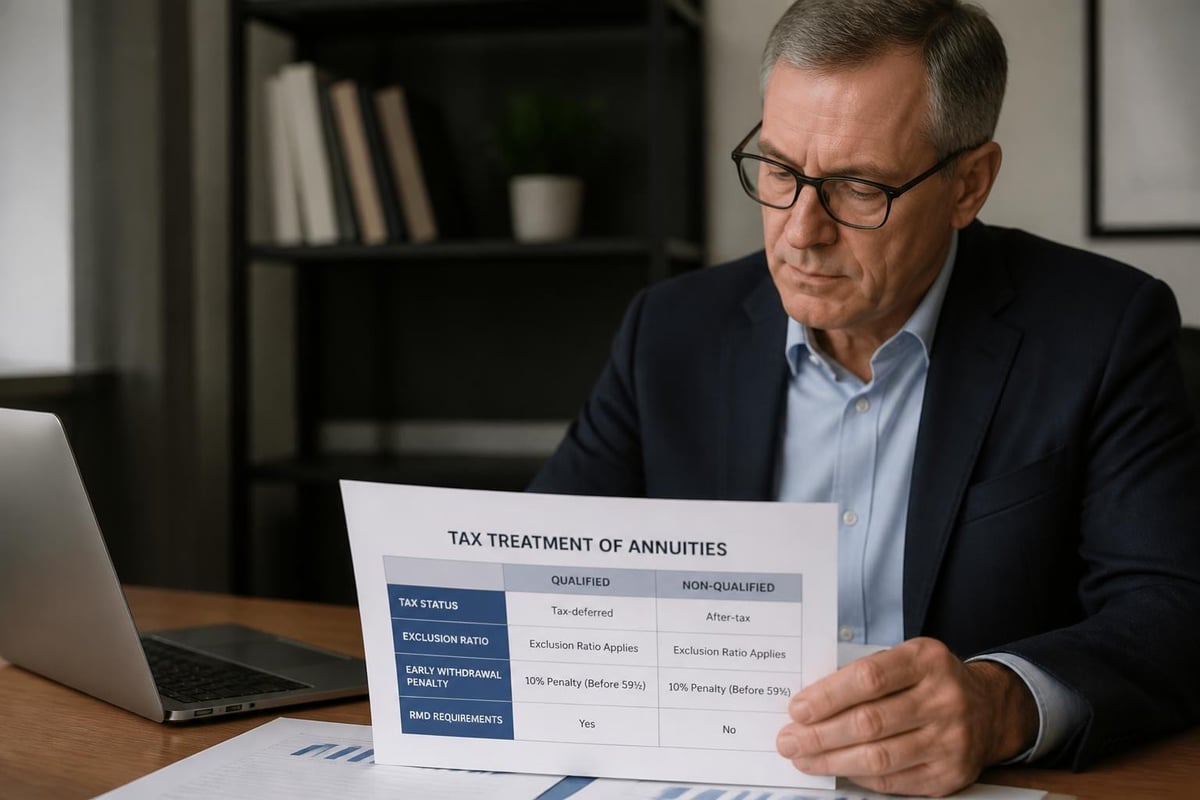
One of the most compelling aspects of annuity general principles involves favorable tax treatment. Annuities grow tax-deferred, meaning you don't pay taxes on earnings until you receive distributions. This feature accelerates accumulation compared to taxable accounts.
Qualified vs. Non-Qualified Annuities
Qualified annuities are funded with pre-tax dollars through retirement accounts like IRAs or 401(k)s. Distributions are taxed entirely as ordinary income since no taxes were paid on contributions.
Non-qualified annuities use after-tax dollars. The IRS Publication 575 details the exclusion ratio that determines how much of each payment represents taxable earnings versus tax-free principal return.
Distribution Tax Implications
The annuity general tax framework includes specific rules for withdrawals:
- Distributions before age 59½ typically incur a 10% early withdrawal penalty
- After age 59½, you pay ordinary income tax on earnings
- Required Minimum Distributions (RMDs) apply to qualified annuities starting at age 73
- Death benefit proceeds may be subject to income tax depending on beneficiary elections
Payout Options and Income Strategies
The annuity general framework provides multiple payout structures, each addressing different longevity and legacy concerns. Selecting the appropriate option requires balancing income needs, life expectancy, and beneficiary considerations.
Life-Only Payout
A life-only payout provides the highest periodic payment but ceases upon death with no remaining value for beneficiaries. This option makes sense when maximizing income takes priority over leaving an inheritance.
Period Certain Options
Period certain annuities guarantee payments for a specific timeframe (10, 15, or 20 years) regardless of whether you're alive. If you die before the period ends, beneficiaries receive the remaining payments.
Joint and Survivor Annuities
Joint and survivor options continue payments as long as either you or your spouse lives. The annuity general structure typically reduces payment amounts compared to single-life options due to extended payment probability.
| Payout Option | Payment Amount | Payments Stop When | Beneficiary Protection |
|---|---|---|---|
| Life Only | Highest | Death of annuitant | None |
| 10-Year Certain | High | Death after 10 years | 10 years guaranteed |
| Joint & Survivor | Moderate | Death of both spouses | Until second death |
| Installment Refund | Lower | Principal returned | Remaining principal |
Fees and Costs in Annuity General Products
Understanding the annuity general fee structure helps evaluate whether a specific product aligns with your financial interests. Transparency around costs has improved significantly following regulatory reforms, but complexity remains.
Common Fee Components
Mortality and expense (M&E) charges compensate the insurance company for insurance risk and administrative costs. Variable annuities typically charge 1.0% to 1.5% annually.
Investment management fees apply to variable annuity sub-accounts, similar to mutual fund expense ratios. These range from 0.5% to 2.0% depending on investment options selected.
Surrender charges penalize early withdrawals during the surrender period, which typically lasts 5 to 10 years. These charges start high (often 7-10%) and decline annually.
Rider fees add optional benefits like guaranteed minimum income, enhanced death benefits, or long-term care provisions. Each rider increases annual costs by 0.25% to 1.5%.
Morningstar’s comprehensive guide to annuities breaks down fee structures and helps consumers compare total costs across different products. This analysis proves invaluable when evaluating competing proposals.
The Annuity Puzzle and Consumer Behavior
Academic research has identified what economists call the "annuity puzzle": despite clear longevity protection benefits, relatively few retirees purchase income annuities. The annuity general framework theoretically addresses significant retirement risks, yet adoption rates remain lower than economic models predict.
Barriers to Annuitization
Research from the National Bureau of Economic Research explores multiple factors that discourage annuity purchases:
- Bequest motives: Desire to leave assets for heirs
- Liquidity concerns: Fear of needing lump-sum access
- Complexity aversion: Difficulty understanding product features
- Pricing perceptions: Belief that annuities offer poor value
- Social insurance: Reliance on Social Security as de facto annuity
Understanding these behavioral factors helps frame annuity general concepts within realistic retirement planning conversations rather than purely mathematical optimization.
Riders and Enhanced Features
The annuity general product landscape has evolved to include numerous optional riders addressing specific concerns. These enhancements make annuities more attractive by mitigating traditional drawbacks.
Guaranteed Minimum Income Benefit (GMIB)
GMIB riders guarantee a minimum income level regardless of account performance. You benefit from market gains while protecting against prolonged downturns affecting your income stream.
Long-Term Care Riders
Some annuity general products now incorporate long-term care benefits, allowing accelerated withdrawals if you require custodial care. This dual-purpose approach addresses both retirement income and potential care costs.
Return of Premium Death Benefits
Enhanced death benefits guarantee beneficiaries receive at least your total contributions, protecting against losses due to poor market timing or early death after annuitization.
The trade-off for these features involves additional costs that reduce overall returns. Evaluating whether specific riders justify their expense requires careful analysis of your personal risk factors and existing coverage.
Annuity General Integration with Retirement Planning
Viewing annuities in isolation misses their strategic role within comprehensive retirement planning. The annuity general framework works best when coordinated with Social Security timing, pension decisions, tax planning, and estate strategies.
Creating Income Floors
Financial planners often recommend establishing an "income floor" covering essential expenses through guaranteed sources: Social Security, pensions, and annuities. Discretionary spending then draws from investment portfolios subject to market risk.
Steps to construct an income floor:
- Calculate guaranteed monthly expenses (housing, utilities, food, healthcare)
- Determine Social Security benefits and optimal claiming age
- Add any pension income from employer plans
- Identify the remaining gap between guaranteed income and essential needs
- Consider annuitizing sufficient assets to close that gap
This approach applies annuity general principles to address specific, quantified needs rather than annuitizing arbitrary amounts.
Tax Location Strategy
The annuity general tax-deferral benefit proves most valuable in higher tax brackets. Strategic placement involves funding annuities with dollars that would otherwise face immediate taxation while preserving Roth accounts for tax-free growth.
For residents of Greensboro, High Point, Winston Salem, and Kernersville working with Moser Insurance Group Inc, coordinating annuity decisions with Medicare planning and life insurance creates an integrated approach addressing multiple retirement risks simultaneously.
Regulatory Oversight and Consumer Protection
The annuity general regulatory framework involves multiple agencies ensuring consumer protection and market stability. Insurance commissioners at the state level maintain primary oversight, while federal agencies monitor variable products with securities features.
State Insurance Regulation
Each state insurance department approves annuity products, monitors insurer solvency, and investigates consumer complaints. State guaranty associations provide limited protection if an insurance company fails, typically covering $250,000 in annuity values.
FINRA and SEC Oversight
Variable annuities fall under securities regulation because of investment components. Registered representatives selling these products must hold appropriate licenses and follow suitability standards. NAIC’s consumer publications provide guidance on questions to ask and red flags to watch for.
Suitability Standards
Annuity general regulations require that recommendations align with your financial situation, risk tolerance, investment objectives, and time horizon. Representatives must document why a specific annuity suits your needs and explain all material features, fees, and surrender terms.
Innovations in Annuity Products
The annuity general marketplace continues evolving with products addressing traditional concerns about flexibility and cost. Recent innovations attempt to make annuities more appealing without sacrificing core income guarantees.
Registered Index-Linked Annuities (RILAs)
RILAs offer market participation with buffers or floors limiting downside exposure. These products accept some loss potential in exchange for higher growth potential than traditional indexed annuities, appealing to moderate-risk investors.
Guaranteed Lifetime Withdrawal Benefits
Modern withdrawal benefit riders allow systematic withdrawals while maintaining a death benefit and account liquidity. Vanguard’s research on hybrid solutions explores how these features integrate with other retirement vehicles.
Fee Compression
Competitive pressure and regulatory scrutiny have driven down costs in the annuity general market. Low-cost providers now offer products with total annual fees below 1%, significantly cheaper than traditional variable annuities.
When Annuities Make Sense
The annuity general framework addresses specific retirement challenges particularly well, making these products suitable for certain situations while less appropriate for others.
Ideal Scenarios for Annuity Consideration
Annuities deserve serious consideration when you:
- Lack employer pensions or other guaranteed income sources
- Worry about outliving your savings regardless of portfolio size
- Want predictable income for budgeting essential expenses
- Prefer delegating investment and longevity risk to an insurance company
- Have maximized tax-advantaged retirement accounts
- Face significant required minimum distributions from IRAs
Situations Where Alternatives May Be Better
Annuity general products may not fit when you:
- Need maximum liquidity for unpredictable expenses
- Have significant assets relative to spending needs
- Prefer maintaining full investment control
- Already have adequate guaranteed income from other sources
- Have poor health suggesting below-average life expectancy
The annuity general decision framework requires honest assessment of your risk tolerance, income needs, health status, and overall financial situation rather than following generic recommendations.
Evaluating Annuity Proposals
When considering specific annuity general products, systematic evaluation prevents costly mistakes and ensures alignment with your goals. Insurance representatives should provide clear documentation and welcome questions throughout the process.
Critical Questions to Ask
Before purchasing any annuity product, obtain clear answers to these essential questions:
- What are all fees, including M&E charges, investment expenses, rider costs, and administrative fees?
- How long is the surrender period and what are the annual surrender charges?
- What guarantees does the product provide and how are they funded?
- How does the death benefit work and what do beneficiaries receive?
- What happens if I need to access funds during the surrender period?
- How strong is the insurance company's financial rating?
Understanding Illustrations
Annuity illustrations project potential future values under various scenarios. The annuity general regulatory framework requires displaying guaranteed values alongside non-guaranteed projections. Focus primarily on guarantees since hypothetical returns may not materialize.
Morningstar’s analysis of what investors need to know emphasizes understanding the difference between best-case scenarios and contractual minimums when reviewing illustrations.
Market Trends and Industry Outlook
The annuity general market has grown substantially as baby boomers transition into retirement seeking income solutions. Industry data shows increasing sales across all product categories, with indexed and RILA products capturing significant market share.
Total annuity sales in the United States exceeded $300 billion in 2025, reflecting growing recognition of longevity risk among retirees. Fixed indexed annuities represent the largest product segment, appealing to investors seeking growth potential with principal protection.
The shift toward fee-based financial advice has prompted development of commission-free annuity products designed for registered investment advisors. This evolution expands access to annuity general benefits while aligning with fiduciary compensation models.
Demographic trends suggest continued growth as more Americans reach retirement age with inadequate pension coverage. The annuity general framework provides solutions to this retirement income gap, positioning these products for sustained demand.
Understanding annuity general principles empowers you to make informed decisions about incorporating guaranteed income into your retirement plan. While annuities aren't appropriate for everyone, they address legitimate concerns about longevity risk and income predictability that affect most retirees. At Moser Insurance Group Inc, we help individuals and families in the Triad Area navigate insurance and retirement planning decisions with clear, pressure-free guidance. Whether you're evaluating annuities alongside Medicare options or coordinating life insurance with retirement strategies, our team provides personalized support tailored to your unique situation. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your retirement and insurance needs with experienced professionals who prioritize education and understanding.
Recent Comments