

Life insurance decisions shape financial security for decades. When families in Greensboro, Kernersville, High Point, and Winston Salem explore coverage options, they frequently encounter Mutual of Omaha as a trusted carrier with over a century of experience. Understanding what this company offers, how their policies work, and whether their products align with your family's needs requires careful examination of product lines, financial stability, and customer experience. This comprehensive guide walks through everything you need to know about mutual of omaha life insurance in 2026, from policy types to claims processes.
Understanding Mutual of Omaha's Market Position
Mutual of Omaha has operated in the insurance industry since 1909, building a reputation as one of America's most recognizable life insurance providers. The company specializes in individual life insurance, Medicare supplement coverage, and various financial products designed for long-term security.
The carrier maintains strong financial strength ratings from multiple independent agencies. AM Best assigned Mutual of Omaha an A+ (Superior) rating, the second-highest designation in their scale, indicating excellent ability to meet ongoing insurance obligations. This financial stability matters significantly when purchasing life insurance, as policies often span decades or entire lifetimes.
Financial Strength in Context
Independent rating agencies evaluate insurers on multiple factors:
- Claims-paying ability based on reserves and capital
- Business diversification across product lines and markets
- Operating performance measured through profitability trends
- Enterprise risk management practices and governance
Mutual of Omaha's financial foundation provides peace of mind for policyholders who need assurance their beneficiaries will receive promised benefits when claims arise.
Core Life Insurance Products Offered
Mutual of omaha life insurance products span several categories, each designed for different financial goals and coverage needs. Understanding these distinctions helps families select appropriate protection.
Term Life Insurance Options
Term policies provide coverage for specific periods, typically 10, 15, 20, or 30 years. Mutual of Omaha structures term products with level premiums throughout the selected period, meaning your monthly payment remains consistent for the entire term.
Key features include:
- Coverage amounts ranging from $25,000 to $5 million
- Convertibility options allowing term-to-permanent policy switches
- Return of premium riders on select products
- Accelerated death benefit riders for qualifying terminal illnesses
Families in the Triad Area often choose term coverage to protect mortgages, replace income during working years, or cover children's education expenses. The affordability of term life insurance makes it accessible for young families establishing financial foundations.
Whole Life Insurance Policies
Permanent coverage through whole life insurance provides lifelong protection with additional benefits beyond a death benefit. These policies build cash value that grows on a tax-deferred basis, creating a living benefit accessible through loans or withdrawals.
| Feature | Guaranteed Universal Life | Traditional Whole Life | Universal Life |
|---|---|---|---|
| Coverage Duration | Lifetime (if premiums paid) | Lifetime | Flexible |
| Premium Structure | Fixed | Fixed | Adjustable |
| Cash Value Growth | Minimal/None | Guaranteed + Dividends | Variable |
| Premium Cost | Lower | Higher | Moderate |
Mutual of Omaha's whole life products appeal to individuals seeking predictable premiums, guaranteed cash value accumulation, and potential dividends. The Mutual of Omaha whole life options deserve consideration for those building long-term financial strategies beyond basic protection.
Universal Life Variations
Universal life insurance combines permanent coverage with flexible premiums and death benefits. Mutual of Omaha offers several universal life variations, including indexed universal life products that tie cash value growth to market index performance without direct market exposure.
Advantages of universal life include:
- Adjustable death benefit amounts as needs change
- Premium payment flexibility during different life stages
- Potential for competitive cash value growth
- Tax-advantaged retirement income strategies
These policies require more active management than whole life but provide greater customization potential for sophisticated planning needs.
Guaranteed Issue and Simplified Issue Products
Not everyone qualifies for traditional underwritten life insurance due to health conditions or age. Mutual of omaha life insurance addresses this gap through alternative products.
Guaranteed Acceptance Life Insurance
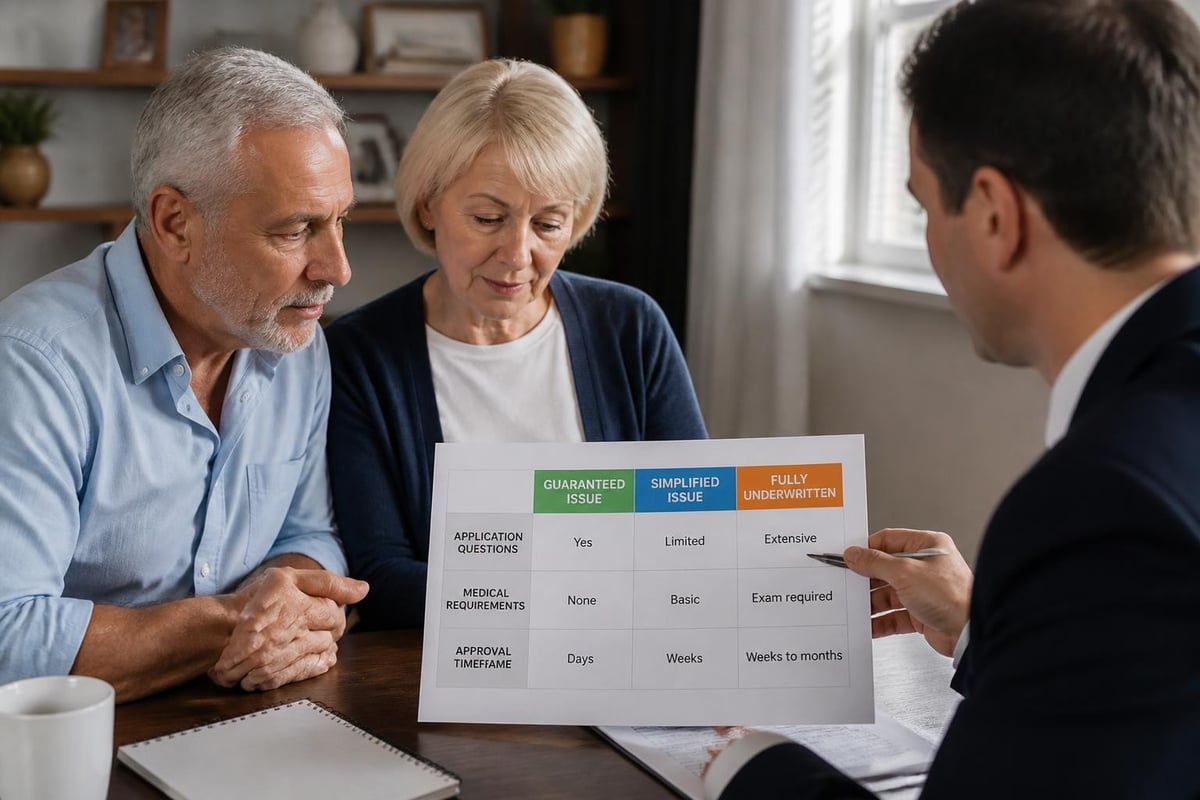
The guaranteed issue life insurance product accepts applicants ages 45-85 without medical exams, blood tests, or health questions. Approval is guaranteed regardless of health status.
Trade-offs include:
- Lower coverage amounts (typically $2,000-$25,000)
- Graded death benefits during initial policy years
- Higher premium costs relative to coverage amounts
- Immediate coverage for accidental death
This product serves seniors who cannot qualify for traditional policies or need small amounts of coverage for final expenses without lengthy underwriting processes.
Simplified Issue Coverage
Simplified issue policies require health questions but no medical examinations. Processing occurs faster than fully underwritten policies, with decisions often within days rather than weeks.
The health questionnaire covers recent diagnoses, medications, and lifestyle factors. Applicants with manageable chronic conditions may qualify when traditional underwriting would decline them.
The Application and Underwriting Process
Obtaining mutual of omaha life insurance follows a structured process designed to assess risk and determine appropriate premium rates. Understanding each step helps applicants prepare properly and avoid delays.
Initial Application Steps
- Complete the application form with personal information, health history, and coverage preferences
- Authorize background checks including medical records, prescription databases, and motor vehicle reports
- Schedule medical examination if required for your coverage amount and age
- Review beneficiary designations ensuring proper legal structure
Applications for larger coverage amounts or older applicants typically require paramedical exams including height/weight measurements, blood pressure readings, blood tests, and urine samples.
Underwriting Review Timeline
Standard underwriting reviews take 4-6 weeks on average, though simplified and accelerated underwriting paths complete within 7-10 days. Delays occur when medical records require additional clarification or when applicants have complex health histories requiring physician statements.
During underwriting, Mutual of Omaha assigns risk classifications that determine premium rates:
- Preferred Plus/Elite: Excellent health, favorable family history
- Preferred: Very good health with minor issues
- Standard Plus: Average health for age group
- Standard: Some health concerns or lifestyle factors
- Substandard/Table Ratings: Significant health issues requiring premium adjustments
Applicants should provide complete, accurate health information. Omissions discovered later may result in claim disputes or policy rescission during contestability periods.
Claims Process and Beneficiary Support
Understanding how beneficiaries file claims provides important context when selecting life insurance. Mutual of Omaha's claims support process aims to deliver benefits promptly during difficult times.
Filing a Death Claim
Beneficiaries initiate claims by contacting Mutual of Omaha's claims department at 1-800-775-6000 or through their online portal. Required documentation includes:
- Certified death certificate from the issuing state
- Completed claim form with beneficiary information
- Policy documentation including policy number
- Proof of identity for beneficiaries
For policies past the two-year contestability period, claims processing typically completes within 7-14 business days after receiving complete documentation. Benefits can be paid as lump sums, annuity payments, or retained in interest-bearing accounts at beneficiary discretion.
Claim Denial Situations
While most legitimate claims pay without issue, certain circumstances may delay or deny claims:
- Material misrepresentation during application within contestability period
- Death resulting from policy exclusions (suicide during first two years, certain illegal activities)
- Lapsed policy due to non-payment of premiums
- Beneficiary disputes requiring legal resolution
Beneficiaries have appeal rights when claims are denied. Working with experienced insurance professionals during the application phase helps avoid documentation issues that complicate claims later. For personalized guidance on policy selection and claims support in Greensboro, High Point, Winston Salem, or Kernersville, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com.
Customer Experience and Satisfaction
Financial strength ratings tell only part of the story. Customer service quality, claims experience, and overall satisfaction provide essential context when evaluating mutual of omaha life insurance.
Industry Satisfaction Benchmarks
The American Customer Satisfaction Index tracks life insurance industry performance across multiple dimensions including policy offerings, billing, claims, and customer service. Life insurers as a category score moderately well compared to other financial services, though significant variation exists between carriers.
Mutual of Omaha receives mixed customer feedback across review platforms. Positive experiences highlight responsive service, straightforward claims processing, and competitive pricing for certain demographics. Negative reviews cite premium increases on some universal life products, customer service wait times, and occasional policy administration confusion.
Regulatory Complaint Data
State insurance departments track consumer complaints relative to market share, providing objective measures of customer issues. The Missouri Department of Insurance publishes complaint ratios and company details for Mutual of Omaha, allowing consumers to compare complaint volumes against the company's size.
Lower complaint ratios indicate better customer experience relative to business volume. Reviewing these state-level metrics adds important context beyond marketing materials and selected testimonials.
Comparing Mutual of Omaha to Market Alternatives
No single carrier excels for every customer. Evaluating mutual of omaha life insurance against alternatives helps identify the best fit for specific situations.
Pricing Competitiveness
Premium rates vary significantly based on age, health, coverage amount, and policy type. Mutual of Omaha often prices competitively for:
- Young, healthy applicants seeking term coverage
- Simplified issue products for older applicants
- Guaranteed issue final expense policies
However, comparison shopping remains essential. Some carriers offer better rates for specific health profiles, occupations, or lifestyle factors. Obtaining quotes from multiple highly-rated carriers ensures you're not overpaying for equivalent coverage.
Product Innovation and Features
Mutual of Omaha offers solid core products but doesn't always lead in product innovation compared to some competitors. Other carriers may provide:
- More aggressive accelerated underwriting (instant approvals without exams)
- Broader chronic illness and critical illness riders
- More flexible return of premium options
- Enhanced cash value growth opportunities
Evaluating which features matter most for your situation helps prioritize carriers during shopping. For families in the Triad Area seeking guidance on different types of life insurance, working with independent advisors provides access to multiple carrier options rather than single-company limitations.
Financial Strength Comparisons
While Mutual of Omaha maintains strong ratings, some carriers hold higher designations. Independent analyses from Weiss Ratings and other agencies offer different perspectives on financial stability using varying methodologies.
Top-tier rated carriers include:
- Northwestern Mutual (A++ from AM Best)
- Mass Mutual (A++ from AM Best)
- New York Life (A++ from AM Best)
- Guardian Life (A++ from AM Best)
These slightly higher ratings may justify premium differences for ultra-conservative buyers prioritizing maximum safety, though Mutual of Omaha's A+ rating represents excellent financial security for most policyholders.
Riders and Policy Customization Options
Mutual of omaha life insurance policies accept various riders that customize coverage to specific needs. Understanding available riders helps optimize policy design.
Common Rider Options
Accelerated Death Benefit Rider: Allows access to death benefit proceeds if diagnosed with qualifying terminal illness. Typically included at no additional cost on newer policies.
Waiver of Premium Rider: Continues coverage without premium payments if you become totally disabled before age 60 or 65. Premium waivers prevent policy lapses during income loss periods.
Child Term Rider: Adds coverage for dependent children under a single rider, typically providing $10,000-$25,000 per child at minimal cost.
Accidental Death Benefit Rider: Pays additional benefit if death results from covered accident. Generally cost-effective but adds limited value since accidents represent small percentage of deaths.
| Rider Type | Typical Cost | Primary Benefit | Best For |
|---|---|---|---|
| Accelerated Death Benefit | Included | Terminal illness access | Everyone |
| Waiver of Premium | 5-10% of base premium | Disability protection | Income earners |
| Child Term | $50-100/year | Children's coverage | Parents |
| Accidental Death | 10-15% of base premium | Accident benefit double | High-risk occupations |
Long-Term Care Hybrid Riders
Some Mutual of Omaha products offer chronic illness or long-term care acceleration riders, allowing policyholders to access death benefits for qualifying care needs. These hybrid long-term care insurance approaches leverage life insurance for dual purposes.
Benefits accelerate monthly (typically 2-4% of death benefit per month) when you cannot perform two or more activities of daily living or require cognitive impairment supervision. This provides care funding without purchasing separate long-term care insurance while maintaining death benefit if care is never needed.
Policy Maintenance and Long-Term Management
Purchasing life insurance marks the beginning, not the end, of policy management. Proper maintenance ensures coverage remains aligned with changing needs and circumstances.
Premium Payment Management
Missing premium payments triggers grace periods (typically 30-31 days) before policies lapse. Mutual of Omaha sends multiple notices before termination, but maintaining current contact information and payment methods prevents accidental lapses.
Payment options include:
- Monthly bank drafts
- Annual or semi-annual premium payments (often discounted)
- Credit card automatic payments
- Direct bill with paper invoices
Permanent policies with cash value may support automatic premium loans, borrowing against cash value to cover missed payments and prevent lapses.
Beneficiary Updates
Life changes require beneficiary updates to ensure benefits reach intended recipients. Common trigger events include:
- Marriage or divorce
- Birth or adoption of children
- Death of named beneficiary
- Significant wealth changes affecting estate planning
Outdated beneficiary designations create complications during claims. Review designations every 2-3 years or after major life events. Contingent beneficiaries provide backup if primary beneficiaries predecease policyholders.
Policy Reviews and Adjustments
Annual policy reviews ensure coverage remains adequate as financial circumstances evolve. Growing families may need coverage increases, while empty nesters may reduce coverage or shift strategies.
Convertibility features on term policies allow switching to permanent coverage without new medical underwriting, preserving insurability despite health changes. Understanding conversion windows (typically available through age 65-70 or until age 70) prevents losing this valuable option.
Special Considerations for Different Age Groups
Mutual of omaha life insurance needs vary significantly across life stages. Tailoring coverage to specific demographics optimizes protection and value.
Coverage for Young Families
Parents in their 30s and 40s typically need maximum coverage at minimum cost to protect young children and mortgages. Term insurance provides the highest death benefit per premium dollar, making 20-30 year term policies popular choices.
Coverage amount calculations for young families should consider:
- Outstanding mortgage balance
- Income replacement for 15-20 years
- College funding for all children
- Final expenses and estate settlement costs
Many families in Kernersville and surrounding Triad communities select term coverage between $500,000-$1,000,000 during child-rearing years, supplemented with smaller permanent policies for lifelong coverage.
Pre-Retirees Approaching 50-65
This demographic transitions from accumulation to preservation. Priorities shift toward:
- Converting expiring term policies before age limits
- Establishing permanent coverage for estate liquidity
- Funding final expenses without burdening children
- Maximizing cash value growth for supplemental retirement income
Whole life or guaranteed universal life products appeal to this age group seeking certainty in premium costs and death benefit guarantees.
Seniors Over 65
Older applicants face higher premiums due to mortality risk but still access mutual of omaha life insurance through simplified and guaranteed issue products. Common uses include:
- Covering final expenses ($10,000-$25,000)
- Equalizing inheritances among children
- Paying estate taxes or settlement costs
- Funding charitable legacies
Seniors should compare burial insurance costs against pre-need funeral plans, ensuring the most cost-effective final expense coverage. Understanding how burial insurance works helps make informed decisions.
Integration with Broader Financial Planning
Life insurance functions as one component within comprehensive financial strategies. Understanding how mutual of omaha life insurance integrates with other planning elements maximizes overall effectiveness.
Estate Planning Coordination
Life insurance death benefits pass to beneficiaries outside probate, providing immediate liquidity for estate settlement costs, taxes, and support needs. Proper policy ownership and beneficiary structuring prevents unintended tax consequences.
Estate planning considerations include:
- Irrevocable life insurance trusts for estate tax exclusion
- Business succession funding for partnership agreements
- Generation-skipping strategies for wealth transfer
- Charitable giving through beneficiary designations
Coordination between insurance advisors, estate attorneys, and tax professionals ensures policies support overall estate objectives.
Retirement Income Strategies
Permanent life insurance cash values create tax-advantaged retirement income sources through policy loans and withdrawals. This strategy works best when policies remain in force through life expectancy, preserving death benefits for beneficiaries.
Cash value access strategies complement other retirement accounts, providing tax diversification since policy loans aren't reported as taxable income when structured properly. However, excessive loans or withdrawals may cause policies to lapse, creating unexpected tax liabilities.
Coordination with Employer Benefits
Most employees receive group term life insurance through employers, typically one to two times annual salary. This base coverage rarely provides sufficient protection for families with children and mortgages.
Individual mutual of omaha life insurance supplements employer coverage with:
- Portability: Coverage continues regardless of employment changes
- Higher limits: Individual policies access multi-million dollar coverage
- Customization: Riders and features unavailable in group plans
- Permanent options: Cash value accumulation beyond basic protection
Maintaining both employer and individual coverage provides comprehensive protection while employed, with individual policies continuing after retirement or job changes.
Making Your Decision: Key Evaluation Criteria
Selecting appropriate life insurance requires methodical evaluation across multiple dimensions. Use this framework when considering mutual of omaha life insurance or alternatives.
Financial Strength Assessment
Verify current ratings from AM Best, Moody's, and Standard & Poor's rather than relying on marketing materials. The detailed AM Best assessment provides comprehensive financial analysis updated regularly.
Companies maintain ratings for decades, but periodic review ensures ongoing stability, particularly for long-term permanent policies that may span 40-50 years.
Price Comparison Methodology
- Obtain quotes from 4-6 highly-rated carriers for identical coverage amounts and terms
- Compare total cost over policy duration rather than just monthly premiums
- Evaluate guaranteed versus non-guaranteed elements in permanent policies
- Consider premium stability and potential for future increases
Term insurance comparisons focus on premium guarantees and conversion features. Permanent policy comparisons require analysis of cash value projections, dividend histories, and policy loan provisions.
Product Feature Analysis
Beyond price, evaluate which features matter most for your situation:
- Conversion options and windows on term policies
- Cash value growth potential and guarantees
- Rider availability and costs
- Premium payment flexibility
- Death benefit adjustment capabilities
No policy excels in every category. Identifying your top three priorities helps narrow options to best-fit products.
Service and Support Expectations
Consider how much hand-holding you need throughout the policy lifecycle. Some policyholders prefer direct carrier relationships, while others value ongoing advisor support for beneficiary updates, policy reviews, and claims assistance.
Independent advisors like Moser Insurance Group Inc provide ongoing service across multiple carriers, while captive agents represent single companies. Choose the service model matching your comfort level and support needs. Visit moserinsurancegroup.com or call 336-862-1763 to discuss options serving the Greensboro, Winston Salem, High Point, and Kernersville communities.
Tax Implications and Benefits
Life insurance enjoys favorable tax treatment under current federal law, creating valuable planning opportunities through mutual of omaha life insurance products.
Income Tax Advantages
Death benefits: Beneficiaries receive death benefit proceeds entirely income tax-free under IRC Section 101(a)(1), regardless of benefit amount. This tax-free transfer makes life insurance highly efficient for wealth transfer compared to other assets triggering capital gains or ordinary income taxes.
Cash value growth: Permanent policy cash values grow tax-deferred, similar to retirement accounts. Unlike retirement accounts, properly structured policies allow tax-free access through loans that don't trigger income recognition.
Policy loans: Borrowing against cash value doesn't create taxable events provided policies remain in force through death. Outstanding loans reduce death benefits but beneficiaries still receive proceeds tax-free.
Estate Tax Considerations
Life insurance death benefits are included in the deceased's taxable estate when they maintain ownership or control. For 2026, federal estate tax exemptions sit at $13.61 million per individual ($27.22 million for married couples), meaning most families avoid federal estate tax.
High-net-worth individuals use irrevocable life insurance trusts (ILITs) to exclude death benefits from taxable estates, preserving exemptions for other assets. This advanced strategy requires careful legal structuring but provides significant tax savings for multi-million dollar estates.
Gift Tax Planning
Annual premium payments to ILITs may utilize annual gift tax exclusions ($18,000 per recipient in 2026), allowing tax-free wealth transfer during life. Properly documented Crummey powers ensure premiums qualify for annual exclusions rather than consuming lifetime exemption amounts.
These sophisticated strategies require coordination with qualified estate planning attorneys and tax advisors to ensure compliance and optimize benefits.
Mutual of omaha life insurance provides solid coverage options backed by strong financial ratings and over a century of experience. Whether you need affordable term protection for young children, permanent coverage for lifelong security, or guaranteed issue products despite health challenges, understanding product features, pricing structures, and company stability helps you make confident decisions. Moser Insurance Group Inc serves families throughout the Triad Area with personalized guidance on life insurance, Medicare, and health coverage options without sales pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to explore how the right coverage can protect your family's financial future.
Recent Comments