
Choosing life insurance has traditionally meant scheduling medical exams, waiting weeks for approval, and navigating complex paperwork. Ethos life insurance represents a shift toward streamlined, technology-driven coverage that eliminates many of these traditional barriers. This digital-first approach has made securing term life insurance faster and more accessible for families across the United States, including those in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem. Understanding how ethos life insurance works can help you determine whether this modern approach aligns with your family's protection needs.
What Makes Ethos Life Insurance Different
Ethos life insurance operates as a direct-to-consumer platform that leverages technology to simplify the application process. Instead of requiring in-person medical examinations, the company uses advanced algorithms and data analytics to assess risk and provide instant coverage decisions for many applicants.
The application process takes place entirely online, typically requiring only 10-15 minutes to complete. Applicants answer health and lifestyle questions through a digital questionnaire, and the system evaluates eligibility using publicly available data and predictive models. This approach has proven particularly appealing to younger families and professionals who value convenience and transparency.
No Medical Exam Coverage Options
One of the defining features of ethos life insurance is the availability of policies without mandatory medical examinations. For coverage amounts up to certain limits, applicants can receive approval based solely on their application responses and algorithmic risk assessment.
Key benefits of this approach include:
- Immediate coverage decisions for qualifying applicants
- No need to schedule appointments or take time off work
- Privacy for those uncomfortable with traditional medical exams
- Faster policy issuance, often within days instead of weeks
This streamlined process particularly benefits individuals with straightforward health profiles who don't have complex medical histories requiring detailed evaluation. For those seeking higher coverage amounts or with specific health conditions, the company may request additional medical information or examinations.
Understanding Ethos Life Insurance Policy Options
Ethos life insurance primarily offers term life insurance policies with coverage periods ranging from 10 to 30 years. Term coverage provides death benefit protection for a specified period, making it an affordable option for families who need substantial coverage during their peak financial responsibility years.
| Coverage Duration | Best For | Typical Use Cases |
|---|---|---|
| 10-Year Term | Short-term obligations | Paying off specific debts, covering education costs |
| 20-Year Term | Growing families | Mortgage protection, income replacement during child-rearing years |
| 30-Year Term | Long-term security | Extended income replacement, comprehensive family protection |
The coverage amounts available through ethos life insurance typically range from $100,000 to $1,500,000, though limits vary based on age, health status, and underwriting criteria. This range accommodates various financial situations, from basic final expense coverage to comprehensive income replacement strategies.
Pricing Structure and Premium Considerations
Premium costs for ethos life insurance policies depend on multiple factors including age, gender, health status, lifestyle habits, and coverage amount. According to industry analyses of Ethos’s pricing structure, younger applicants in excellent health can secure substantial coverage at competitive rates.
The company provides instant quotes during the application process, offering transparency before applicants commit to the policy. This upfront pricing allows families to make informed decisions and compare coverage options effectively. For those exploring various types of life insurance policies, understanding how term insurance pricing differs from permanent options helps clarify long-term financial planning.
The Application Experience
Applying for ethos life insurance begins with visiting their website and entering basic information such as age, gender, and desired coverage amount. The system generates an initial quote, and applicants can proceed to the full application if the pricing aligns with their budget.
The application process follows these steps:
- Complete the health questionnaire covering medical history, medications, and lifestyle factors
- Answer questions about family medical history and occupational hazards
- Review and confirm application details
- Receive instant decision or notification of additional requirements
- Sign policy documents electronically
- Activate coverage once approved
Most applicants with straightforward health profiles receive instant decisions. Those requiring additional review may need to provide medical records or complete a brief phone interview. Customer experiences documented in reviews indicate that even cases requiring additional information typically conclude within one to two weeks.
Health Questionnaire Requirements
The health assessment component asks detailed questions about current medications, diagnosed conditions, surgical history, and family health patterns. Honesty during this process remains critical, as inaccurate information can lead to claim denials or policy cancellations.
Common health topics covered include cardiovascular health, diabetes, mental health conditions, cancer history, and substance use. The questionnaire also explores lifestyle factors such as tobacco use, alcohol consumption, participation in high-risk activities, and occupational hazards.
Comparing Ethos Life Insurance to Traditional Options
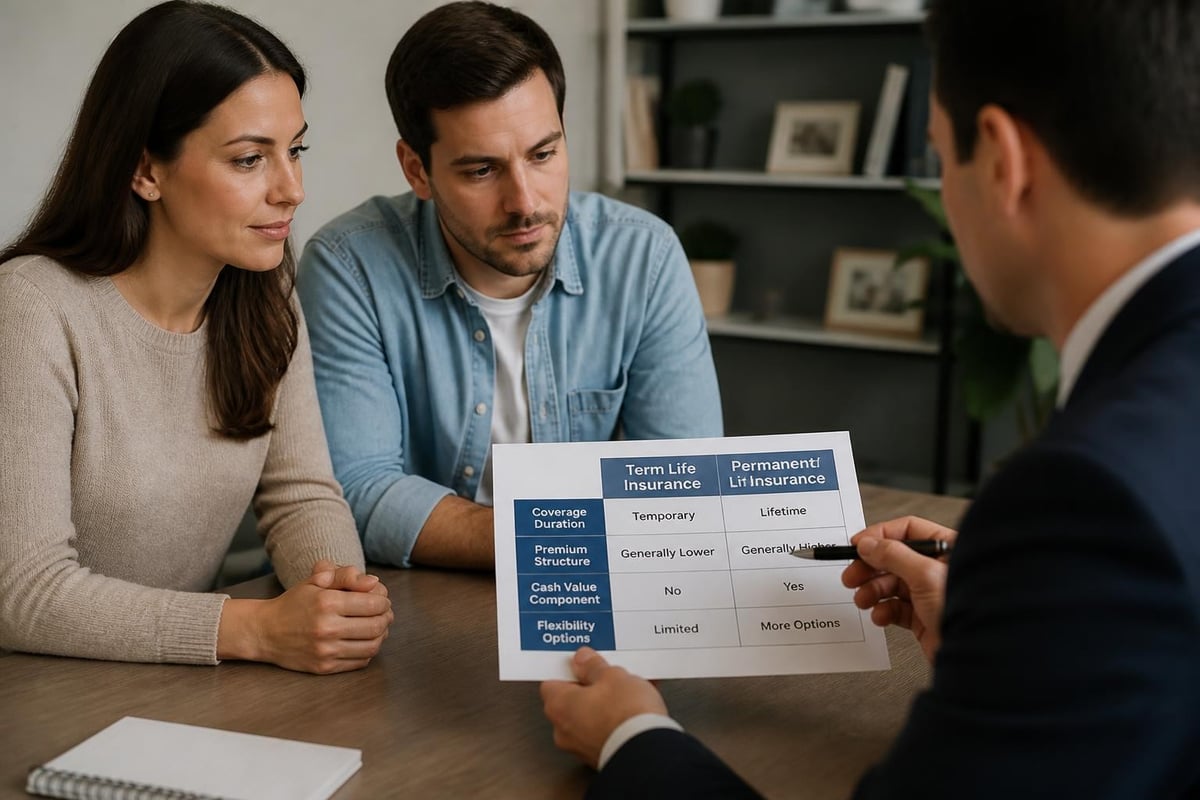
When evaluating ethos life insurance against traditional carriers, several distinctions emerge. Traditional insurers often require medical examinations, offer both term and permanent policies, and may provide additional riders and customization options not available through digital platforms.
The trade-off involves convenience versus comprehensiveness. While ethos life insurance excels at providing quick, straightforward term coverage, families needing permanent protection might explore options like universal life insurance, which combines lifetime coverage with flexible premiums and cash value accumulation.
| Feature | Ethos Life Insurance | Traditional Carriers |
|---|---|---|
| Application Speed | 10-15 minutes online | Multiple appointments over weeks |
| Medical Exam | Often not required | Typically required for larger policies |
| Policy Types | Primarily term life | Term, whole life, universal life, variable |
| Customization | Limited riders available | Extensive rider options |
| Customer Service | Digital-first, phone support | In-person agents, phone, online |
Customer Service and Policy Management
Ethos life insurance provides customer support through phone, email, and digital channels. Policyholders can manage their coverage through an online portal, accessing policy documents, updating beneficiary information, and reviewing coverage details.
According to analysis of the company’s customer service approach, response times and support quality receive generally positive feedback, though some customers prefer the personal relationship available through local insurance agents.
For families in the Triad Area including Greensboro, Kernersville, High Point, and Winston Salem, working with a local insurance professional provides personalized guidance beyond what digital platforms offer. Local agents can explain how life insurance fits within comprehensive financial planning that includes Medicare preparation, health insurance coordination, and retirement strategies.
Who Benefits Most from Ethos Life Insurance
Ethos life insurance serves specific demographics particularly well. Young families seeking affordable term coverage without the hassle of medical exams find the platform appealing. Professionals with busy schedules appreciate the ability to complete applications during evenings or weekends without appointment scheduling.
Ideal candidates for ethos life insurance include:
- Individuals aged 20-45 in good health seeking term coverage
- Families needing straightforward death benefit protection
- First-time life insurance buyers wanting a simple process
- Those uncomfortable with traditional medical examinations
- Budget-conscious consumers comparing multiple quotes quickly
However, this approach may not suit everyone. Individuals with complex health conditions often receive better rates through traditional underwriting with medical exams. Those wanting permanent coverage with cash value components need to explore whole life or universal life options not offered through ethos life insurance.
Understanding Policy Limitations and Exclusions
Like all life insurance policies, ethos life insurance includes specific exclusions and limitations. The suicide clause typically prevents death benefit payment if the insured dies by suicide within the first two years of policy activation. This standard industry practice protects insurers against adverse selection.
The contestability period allows the insurer to investigate claims and application accuracy during the first two years. If material misrepresentation is discovered, the company may deny claims or adjust benefits. This underscores the importance of providing accurate health information during the application process.
Coverage Restrictions for High-Risk Activities
Policies may include exclusions or premium surcharges for individuals engaging in high-risk activities such as aviation, scuba diving, rock climbing, or motor racing. Similarly, certain occupations involving elevated danger may result in higher premiums or coverage restrictions.
Reviewing policy documents carefully before finalizing coverage ensures understanding of all limitations. For those declined or offered unfavorable rates by ethos life insurance, working with an experienced local agent can identify alternative carriers with different underwriting guidelines. When considering how to cancel a life insurance policy if circumstances change, understanding policy provisions prevents unnecessary complications.
The Role of Technology in Modern Life Insurance
Ethos life insurance exemplifies how technology transforms insurance accessibility. Advanced algorithms analyze hundreds of data points to assess risk, often with accuracy comparable to traditional medical underwriting for healthy applicants.
This technological approach reduces administrative costs, allowing companies to offer competitive premiums while maintaining profitability. The efficiency gained through automation translates to faster policy issuance and lower operational overhead.
Technology benefits include:
- Instant quote generation based on real-time data
- Automated risk assessment using predictive analytics
- Streamlined document management and policy administration
- Enhanced fraud detection through data verification
- Improved customer experience through digital accessibility
While technology enhances convenience, it cannot replace the personalized guidance of experienced insurance professionals. Complex financial situations require human expertise to evaluate how life insurance integrates with broader planning objectives.
Evaluating Coverage Adequacy
Determining appropriate coverage amounts requires careful analysis of financial obligations and family needs. Common calculation methods include multiplying annual income by 10-15 times, though this simplified approach may not capture individual circumstances accurately.
A comprehensive needs analysis considers mortgage balances, outstanding debts, education funding goals, final expenses, and income replacement duration. For a family with a $300,000 mortgage, $50,000 in other debts, $100,000 in projected education costs, and $20,000 for final expenses, the baseline need approaches $470,000 before considering income replacement.
Adding income replacement for 10-20 years substantially increases coverage requirements. A primary earner making $75,000 annually might need $750,000 to $1,500,000 in coverage depending on replacement duration and investment return assumptions.
Alternative Considerations for Comprehensive Protection
While ethos life insurance provides accessible term coverage, comprehensive financial planning often requires multiple insurance components. Families approaching retirement age should explore how life insurance coordinates with Medicare preparation and health insurance strategies.
For those interested in permanent coverage with cash value accumulation, understanding universal life insurance reveals options for lifetime protection with flexible premium structures. These policies serve different purposes than term insurance, offering both death benefit protection and tax-advantaged cash value growth.
Medicare beneficiaries often need coverage for final expenses and estate planning purposes rather than income replacement. In these situations, smaller permanent policies or guaranteed issue products may better align with needs and budget constraints.
Working with Insurance Professionals
Despite the convenience of digital platforms like ethos life insurance, working with knowledgeable insurance professionals provides significant advantages. Local agents understand state-specific regulations, coordinate multiple coverage types, and offer ongoing service as circumstances change.
For families in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, connecting with experienced advisors ensures comprehensive coverage evaluation. Professional guidance helps identify coverage gaps, coordinate beneficiary designations, and integrate life insurance within broader financial strategies.
Contact information for personalized assistance:
- Phone: 336-862-1763
- Email: moserinsurancegroup@gmail.com
- Website: moserinsurancegroup.com
Independent agents represent multiple carriers, allowing them to compare options across various companies rather than limiting recommendations to a single provider. This marketplace approach often identifies more competitive rates and better policy features than direct-to-consumer platforms alone.
Policy Conversion and Future Flexibility
Many term life insurance policies, including some offered through ethos life insurance, include conversion privileges allowing policyholders to convert term coverage to permanent insurance without medical underwriting. This feature provides valuable flexibility as needs evolve.
Conversion options typically expire before the term period ends, often around age 65-70 or at specific policy anniversaries. Understanding these provisions when purchasing coverage ensures future options remain available if circumstances change.
| Conversion Feature | Benefit | Limitation |
|---|---|---|
| No medical exam required | Guaranteed acceptance regardless of health changes | Must convert before deadline |
| Locks in insurability | Preserves coverage even if uninsurable later | Permanent policy premiums higher than term |
| Maintains death benefit | Can keep same or lower coverage amount | May not allow coverage increases |
Reviewing conversion provisions before term expiration prevents losing this valuable option. For those exploring 20-year term life insurance options, understanding conversion rights adds important future flexibility.
Financial Strength and Company Stability
When purchasing life insurance, carrier financial strength determines whether death benefits will be paid decades later. Comprehensive reviews of Ethos’s backing and stability reveal the company partners with established insurers holding strong financial ratings.
Ethos life insurance operates as a platform connecting applicants with underwriting carriers rather than serving as the direct insurer. This model means the backing insurance company's financial strength ratings determine claim-paying ability. Reviewing the specific carrier underwriting your policy provides clarity on financial security.
Major rating agencies including A.M. Best, Moody's, and Standard & Poor's evaluate insurance companies' financial health. Policies backed by carriers rated A or higher from these agencies generally demonstrate strong stability and claim-paying capability.
Making Informed Decisions About Coverage
Selecting life insurance requires balancing immediate affordability with long-term protection needs. Ethos life insurance provides accessible term coverage for many families, particularly those valuing convenience and speed over extensive customization.
Before finalizing any coverage decision, consider these essential questions:
- Does term coverage align with my protection timeline, or do I need permanent insurance?
- Will my coverage needs extend beyond the available term lengths?
- Am I comfortable with a digital-only application process, or do I prefer personal guidance?
- Have I compared rates from multiple carriers to ensure competitive pricing?
- Do I understand all policy limitations, exclusions, and conversion options?
Taking time to answer these questions thoroughly prevents purchasing inappropriate coverage or paying more than necessary. For complex situations involving estate planning, business succession, or coordinated family coverage strategies, professional guidance proves invaluable.
Regulatory Oversight and Consumer Protection
Life insurance companies operate under state insurance department regulation, providing consumer protection and ensuring financial solvency standards. Ethos life insurance and its partner carriers maintain required state licenses and comply with applicable consumer protection laws.
State insurance departments handle consumer complaints, investigate company practices, and enforce regulatory compliance. Before purchasing coverage, verifying a company's licensing status and complaint history through your state insurance department website provides additional assurance.
Understanding your rights as a life insurance consumer includes knowing about:
- Free look periods allowing policy cancellation with full refund
- Grace periods for late premium payments
- Requirements for clear policy disclosure
- Claim filing procedures and timeframes
- Appeal processes for denied claims
Finding the right life insurance solution means understanding your options and working with professionals who prioritize education over pressure. Whether ethos life insurance or traditional carriers better suit your needs depends on your unique circumstances, health profile, and coverage objectives. Moser Insurance Group Inc helps families in the Triad Area navigate these decisions with clear guidance and personalized support, ensuring you understand how life insurance fits within your comprehensive protection strategy. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your coverage needs without obligation.
Recent Comments