

Guaranteed whole life insurance represents one of the most straightforward forms of permanent life insurance available to individuals and families seeking predictable, lifelong protection. Unlike term policies that expire after a specific period, this coverage type offers peace of mind through guaranteed premiums, guaranteed death benefits, and simplified underwriting that often requires no medical exam. For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understanding how this insurance works can help you make confident decisions about protecting your family's financial future. Whether you're planning for final expenses, leaving a legacy, or ensuring your loved ones have financial support, guaranteed whole life insurance delivers certainty in an uncertain world.
What Makes Guaranteed Whole Life Insurance Different
Guaranteed whole life insurance stands apart from other life insurance products through its emphasis on simplicity and certainty. This policy type features fixed premiums that never increase, a death benefit that remains level throughout your lifetime, and approval processes designed to accept most applicants regardless of health status.
The "guaranteed" aspect refers to multiple elements of the policy. First, your acceptance is typically guaranteed if you fall within the age limits, usually between 40 and 85 years old. Second, your premiums are guaranteed never to rise above the stated amount. Third, your death benefit is guaranteed to be paid to your beneficiaries as long as premiums are maintained.
Core Features and Benefits
These policies come with several distinguishing characteristics that appeal to specific situations:
- No medical exams required for approval
- Fixed premiums that remain constant for life
- Guaranteed acceptance within age parameters
- Immediate coverage that begins upon approval
- Cash value accumulation that grows over time
- Tax-deferred growth on the cash value component
Most guaranteed whole life insurance policies offer coverage amounts between $5,000 and $25,000, though some carriers extend higher limits. This makes them particularly suitable for covering final expenses, outstanding debts, or leaving a modest inheritance to loved ones.
How Guaranteed Issue Policies Work
The underwriting process for guaranteed whole life insurance differs significantly from traditional policies. Instead of extensive medical questionnaires, lab work, and doctor visits, carriers typically ask only basic information such as age, gender, and tobacco use status. According to Cornell Law School’s insurance overview, whole life insurance creates a contract that provides certainty for both the insurer and policyholder.
The Graded Death Benefit Period
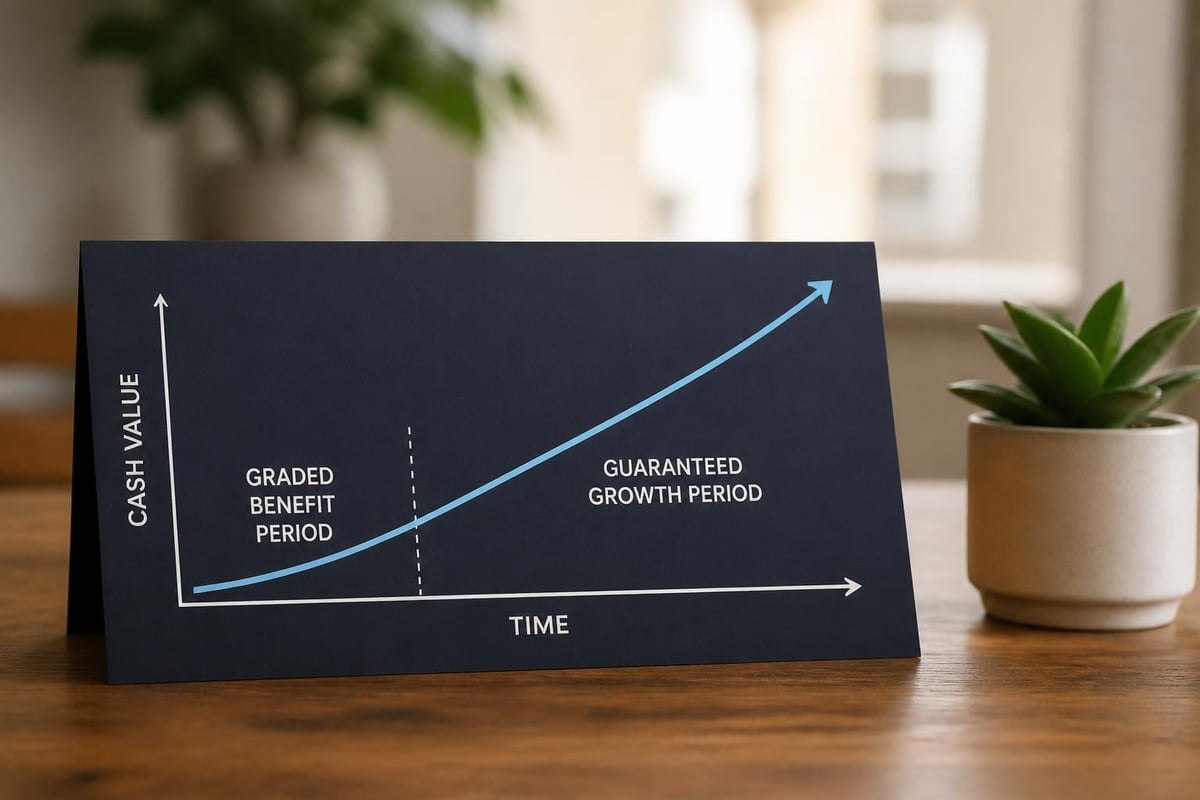
Most guaranteed issue policies include a graded death benefit period, usually lasting two to three years from the policy start date. During this waiting period, if you pass away from natural causes, your beneficiaries receive a return of premiums paid plus interest rather than the full death benefit.
However, the full death benefit becomes payable immediately if death occurs due to an accident during this graded period. After the waiting period expires, the full death benefit is paid regardless of the cause of death.
| Time Period | Death from Natural Causes | Death from Accident |
|---|---|---|
| Years 1-2 | Return of premiums + interest | Full death benefit |
| Year 3+ | Full death benefit | Full death benefit |
This structure protects insurance carriers from adverse selection while still providing meaningful coverage from day one. For families in Winston Salem and surrounding communities, understanding this graded benefit helps set realistic expectations about coverage timing.
Premium Structures and Payment Options
Guaranteed whole life insurance premiums are calculated based on your age at the time of application, gender, tobacco use, and the death benefit amount selected. Once established, these premiums remain fixed for the duration of the policy.
Payment frequencies typically include monthly, quarterly, semi-annual, or annual options. Many carriers offer slight discounts for annual payments since it reduces their administrative costs. For someone purchasing coverage at age 60 with a $10,000 death benefit, monthly premiums might range from $45 to $85 depending on gender and health factors.
Premium Comparison by Age
Understanding how age affects pricing helps with planning:
- Age 50: Lower monthly premiums, longer payment period
- Age 60: Moderate premiums, balanced approach
- Age 70: Higher premiums, shorter payment period
- Age 80: Highest premiums, limited payment years
Working with experienced professionals at Moser Insurance Group Inc helps Greensboro area residents compare options and understand how different purchase ages affect long-term costs. You can reach them at 336-862-1763 or moserinsurancegroup@gmail.com for personalized guidance.
Cash Value Accumulation Explained
One advantage of guaranteed whole life insurance over term coverage involves the cash value component. A portion of each premium payment goes toward building cash value within the policy, which grows at a guaranteed rate specified in your contract. The Washington State Office of the Insurance Commissioner provides detailed explanations of how different cash value policies function.
This cash value grows tax-deferred, meaning you don't pay taxes on the gains as long as they remain inside the policy. Over time, this account can be accessed through policy loans or withdrawals, though doing so reduces the death benefit if not repaid.
Accessing Your Cash Value
Policyholders have several options for utilizing accumulated cash value:
- Policy loans: Borrow against the cash value at interest rates specified in the contract
- Withdrawals: Remove cash directly, permanently reducing the death benefit
- Paid-up insurance: Use cash value to purchase a smaller amount of coverage with no further premiums
- Surrender: Cancel the policy and receive the cash surrender value
Most guaranteed issue policies build cash value more slowly than traditional whole life insurance due to the graded death benefit period and higher risk profile. However, the guaranteed growth rate provides certainty that appeals to conservative planners.
Who Benefits Most from Guaranteed Coverage
Guaranteed whole life insurance serves specific needs better than other insurance types. This product makes the most sense for individuals who face obstacles obtaining traditional coverage or who prioritize simplicity over maximum death benefit.
Ideal Candidates Include
People with pre-existing health conditions that would result in declined applications or extremely high premiums for traditional whole life coverage find guaranteed issue policies accessible. Seniors who missed the opportunity to purchase life insurance earlier in life can secure coverage despite advancing age or health concerns.
Those seeking modest coverage amounts for specific purposes, such as final expense planning, often find guaranteed whole life insurance perfectly suited to their needs. Residents throughout High Point and Kernersville frequently use these policies to ensure funeral costs, outstanding medical bills, or small debts don't burden their families.
| Candidate Profile | Why Guaranteed Whole Life Fits |
|---|---|
| Health issues | No medical exam requirement |
| Advanced age | Acceptance up to age 85 |
| Budget-conscious | Predictable, fixed premiums |
| Simple needs | Straightforward coverage |
Individuals who value certainty and dislike complexity appreciate the straightforward nature of guaranteed whole life insurance. There are no investment decisions to make, no variable rates to track, and no renewal concerns as with term policies.
Comparing Guaranteed vs. Traditional Whole Life
While both policy types provide permanent coverage and cash value, significant differences exist between guaranteed issue and traditional whole life insurance. Understanding these distinctions helps you choose the appropriate product for your situation.
Traditional whole life insurance typically requires medical underwriting, including exams, blood work, and detailed health questionnaires. This process can take several weeks but often results in lower premiums for healthy applicants. According to Guardian Life’s explanation of whole life insurance, traditional policies offer larger death benefits and faster cash value accumulation.
Key Differences at a Glance
Underwriting Process
- Guaranteed: Simplified questions, no medical exam
- Traditional: Full medical underwriting with exams
Death Benefit Amounts
- Guaranteed: Typically $5,000 to $25,000
- Traditional: Often $50,000 to $5 million or more
Premium Costs
- Guaranteed: Higher cost per dollar of coverage
- Traditional: Lower cost for healthy applicants
Cash Value Growth
- Guaranteed: Slower accumulation, guaranteed rates
- Traditional: Faster accumulation, higher guaranteed rates
For families in the Triad Area evaluating life insurance options, Moser Insurance Group Inc provides clear comparisons between different policy types without pressure. Their approach focuses on education, helping clients understand which coverage best fits their unique circumstances.
Tax Advantages and Estate Planning Benefits
Guaranteed whole life insurance offers several tax benefits that enhance its appeal for estate planning purposes. The death benefit passes to beneficiaries income-tax-free, providing full value without tax erosion. This contrasts with many other assets that may face income or capital gains taxes.
Cash value growth within the policy accumulates on a tax-deferred basis, similar to retirement accounts. You pay no taxes on gains as long as the money remains in the policy. When properly structured, policy loans can provide tax-free income during retirement without triggering taxable events.
Estate Planning Applications
Small guaranteed whole life insurance policies serve multiple estate planning functions. They can cover final expenses, preventing your estate from being diminished by funeral costs, probate fees, and final medical bills. For estates approaching federal or state estate tax thresholds, life insurance death benefits may help cover tax obligations.
The guaranteed nature of these policies makes them particularly useful for irrevocable life insurance trusts (ILITs) when the insured has health issues preventing traditional coverage. While smaller coverage amounts limit some estate planning strategies, the certainty of approval enables planning that would otherwise be impossible. Resources from NerdWallet’s whole life insurance guide provide additional perspective on using whole life insurance in financial planning.
Understanding Policy Riders and Additional Features
Many guaranteed whole life insurance policies offer optional riders that enhance coverage for additional premium costs. These endorsements customize the policy to better match your specific needs and circumstances.
Common Riders Include:
- Accidental death benefit: Doubles the death benefit if you pass away from an accident
- Waiver of premium: Continues coverage without premium payments if you become disabled
- Accelerated death benefit: Allows early access to death benefit if diagnosed with terminal illness
- Guaranteed insurability: Permits purchasing additional coverage at specific ages without medical underwriting
Not all carriers offer every rider for guaranteed issue policies, and availability varies by state and age. The accidental death benefit rider proves particularly valuable during the graded benefit period since it provides full death benefit from day one for accidental deaths.
Evaluating Rider Value
When considering riders, evaluate whether the additional premium cost justifies the benefit. A waiver of premium rider might add $5 to $15 monthly but could save thousands in premiums if you become disabled. An accelerated death benefit rider typically carries no additional cost but provides invaluable access to funds if you face terminal illness.
For residents throughout Greensboro seeking to understand rider options, speaking with knowledgeable professionals helps clarify which endorsements make sense for your situation. Call 336-862-1763 to discuss your specific needs and learn how riders can strengthen your guaranteed whole life insurance coverage.
Application Process and What to Expect
Applying for guaranteed whole life insurance takes significantly less time than traditional policies. Most applications can be completed in 15 to 30 minutes, either over the phone, online, or in person with an agent.
The typical application asks for basic information:
- Personal details: Name, address, date of birth, Social Security number
- Contact information: Phone number, email address
- Beneficiary designation: Who receives the death benefit
- Coverage amount: How much death benefit you want
- Payment method: How you'll pay premiums
Some carriers ask a few health questions even for guaranteed issue policies, but these are typically limited to whether you're currently hospitalized or receiving hospice care. These questions help carriers screen out applicants in immediate medical crisis while still accepting people with chronic conditions.
Timeline from Application to Coverage
Most guaranteed whole life insurance policies issue within 24 to 48 hours of application submission. This rapid approval process contrasts sharply with traditional policies that may take four to six weeks for complete underwriting.
Coverage typically begins immediately upon approval and first premium payment. Your policy documents arrive by mail within 7 to 10 business days, containing all contract details, premium schedules, and beneficiary information.
Making Informed Decisions About Guaranteed Coverage
Choosing guaranteed whole life insurance requires honest assessment of your needs, health situation, and financial goals. This coverage type excels in specific scenarios while other options might better serve different circumstances.
Consider guaranteed issue policies when:
- Your health conditions prevent traditional coverage approval
- You need coverage quickly without lengthy underwriting
- You seek modest death benefits for final expenses
- You prioritize guaranteed acceptance over premium costs
- You're past the age limits for many traditional policies
Alternative options may be better if:
- You're in good health and can qualify for traditional coverage
- You need larger death benefit amounts
- You want maximum cash value accumulation
- Premium cost efficiency is your primary concern
Policygenius’s whole life insurance overview offers additional context for comparing different policy types. For personalized guidance specific to your situation in High Point, Winston Salem, or throughout the Triad Area, consulting with experienced professionals ensures you make the choice that best protects your family.
Common Misconceptions and Clarifications
Several misunderstandings surround guaranteed whole life insurance that can lead to poor decisions or unrealistic expectations. Clearing up these misconceptions helps you approach this coverage type with accurate information.
Misconception: "Guaranteed means I'm covered immediately for any amount."
Reality: While acceptance is guaranteed, coverage amounts are limited and graded death benefits apply initially.
Misconception: "These policies are too expensive to be worthwhile."
Reality: When traditional coverage is unavailable, guaranteed issue policies provide value despite higher per-dollar costs.
Misconception: "The cash value grows as quickly as traditional whole life."
Reality: Cash value accumulation is slower due to graded benefits and higher risk factors.
Setting Realistic Expectations
Understanding what guaranteed whole life insurance can and cannot do helps you set appropriate expectations. These policies excel at providing certainty and accessibility, ensuring your family receives a guaranteed benefit when you pass away. They don't compete with traditional policies on cost efficiency or maximum coverage amounts.
The peace of mind from knowing you have coverage in place, despite health challenges that might otherwise disqualify you, often outweighs the premium difference. For final expense planning specifically, guaranteed whole life insurance frequently represents the most practical solution for individuals with health conditions.
Reviewing and Maintaining Your Policy
Once your guaranteed whole life insurance policy is in force, certain maintenance steps ensure it continues serving your needs effectively. Unlike term policies that require renewal decisions, whole life coverage remains active as long as premiums are paid.
Annual Policy Reviews
Even though the policy terms remain constant, your life circumstances change. Annual reviews help ensure your coverage still aligns with your needs:
- Verify beneficiary designations remain current
- Confirm contact information is updated
- Review cash value accumulation progress
- Assess whether additional coverage is needed
- Evaluate if riders should be added or removed
Changes in marital status, births, deaths, or divorces may necessitate beneficiary updates. Keeping beneficiary designations current ensures the death benefit reaches the intended recipients without complications.
Premium Payment Management
Missing premium payments can cause policy lapses, potentially forfeiting years of cash value accumulation and coverage. Setting up automatic payments from checking accounts prevents missed payments due to oversight. Most carriers offer 30-day grace periods if payments are late, but relying on grace periods creates unnecessary risk.
If financial difficulties make premium payments challenging, contact your carrier immediately. Options might include using accumulated cash value to pay premiums temporarily, reducing the death benefit to lower premiums, or converting to paid-up insurance with a smaller benefit amount.
Regional Considerations for Triad Area Residents
Residents throughout Greensboro, Kernersville, High Point, and Winston Salem face unique considerations when purchasing guaranteed whole life insurance. North Carolina specific regulations and regional cost-of-living factors influence policy decisions.
North Carolina has specific insurance regulations that protect consumers while ensuring carrier stability. The state's Department of Insurance oversees all life insurance sales, requiring carriers to meet financial standards and maintain claims-paying ability. This regulatory oversight provides confidence that your guaranteed whole life insurance benefits will be paid when needed.
Local Planning Factors
Average funeral costs in the Triad Area typically range from $7,000 to $12,000, influencing the death benefit amount many residents choose for final expense coverage. Understanding local costs helps you select appropriate coverage levels that actually meet your family's needs.
Many Greensboro area residents balance guaranteed whole life insurance with other financial planning tools. Medicare coverage handles many healthcare costs during retirement years, but final expenses, outstanding debts, and legacy planning still require dedicated solutions. For comprehensive guidance on both Medicare and life insurance needs, visiting moserinsurancegroup.com provides access to educational resources specific to Triad Area residents.
Guaranteed whole life insurance provides accessible, permanent coverage with predictable premiums and guaranteed benefits that serve specific planning needs effectively. Understanding how these policies work, their advantages and limitations, and how they fit within your broader financial picture enables confident decision-making. Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate insurance options with clear explanations and personalized support, ensuring you understand guaranteed whole life insurance without pressure or confusion. Contact them at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss how guaranteed whole life insurance might fit your family's protection plan.
Recent Comments