

Understanding the relationship between Medicare, UnitedHealthcare, and AARP can feel overwhelming when you're approaching Medicare eligibility or looking to change your current coverage. The medicare uhc aarp partnership represents one of the most recognized Medicare plan options in the United States, serving millions of beneficiaries through Medicare Advantage, Part D prescription drug plans, and Medigap supplement insurance. Whether you live in the Triad Area, Greensboro, Kernersville, High Point, or Winston Salem, understanding how these plans work and what they offer can help you make an informed decision about your healthcare coverage. This guide breaks down the essential information you need to know about medicare uhc aarp plans, including coverage options, costs, enrollment periods, and how to determine which plan type best fits your healthcare needs and budget.
What Is the Medicare UHC AARP Partnership
The medicare uhc aarp relationship is a collaboration between UnitedHealthcare, one of the nation's largest health insurance companies, and AARP (formerly the American Association of Retired Persons), an advocacy organization for Americans aged 50 and older. UnitedHealthcare administers and underwrites the insurance plans, while AARP provides brand endorsement and member benefits.
This partnership has existed for decades and offers three primary Medicare insurance products: Medicare Advantage plans (Part C), Medicare Part D prescription drug plans, and Medicare Supplement insurance (Medigap). Each product serves different purposes and works alongside Original Medicare in different ways.
Key distinctions include:
- Medicare Advantage replaces Original Medicare with private plan coverage
- Part D adds prescription drug coverage to Original Medicare
- Medigap supplements Original Medicare to cover out-of-pocket costs
AARP membership is not required to enroll in most medicare uhc aarp plans, though some plans may offer additional benefits or reduced premiums for AARP members. The membership fee for AARP is separate from any insurance premiums you pay.
Medicare Advantage Plans Through UHC AARP
AARP Medicare Advantage plans from UnitedHealthcare provide an alternative way to receive your Medicare benefits. Instead of having Original Medicare (Parts A and B) directly from the government, you receive all your Part A and Part B coverage through the private insurance plan.
Plan Types Available
UnitedHealthcare offers several Medicare Advantage plan types under the AARP brand:
- HMO (Health Maintenance Organization) plans require you to use network providers and get referrals for specialists
- PPO (Preferred Provider Organization) plans offer more flexibility to see out-of-network doctors at higher costs
- HMO-POS (Point of Service) plans combine HMO structure with some out-of-network coverage
- Special Needs Plans for people with specific chronic conditions or institutional care needs
Most medicare uhc aarp Medicare Advantage plans include prescription drug coverage (Part D) built into the plan, eliminating the need for a separate Part D policy. Many also offer extra benefits not covered by Original Medicare, such as dental care, vision services, hearing aids, fitness memberships, and over-the-counter allowances.
Costs and Coverage Details
Medicare Advantage plans have unique cost structures compared to Original Medicare. Understanding these differences helps you budget for healthcare expenses throughout the year.
| Cost Component | What You Pay |
|---|---|
| Monthly Premium | Plan premium + Part B premium (most pay $185 in 2026) |
| Deductible | Varies by plan; some have $0 deductible |
| Copays/Coinsurance | Set amounts for doctor visits, specialists, hospital stays |
| Out-of-Pocket Maximum | Annual limit protecting against catastrophic costs |
The out-of-pocket maximum is a critical protection feature. Once you reach this annual limit, the plan pays 100% of covered services for the rest of the year. This cap doesn't exist with Original Medicare alone, making Medicare Advantage particularly valuable for those with significant healthcare needs.
Medicare Part D Prescription Drug Plans
AARP’s Medicare Part D prescription drug plans offered through UnitedHealthcare provide coverage for medications when you have Original Medicare. If you choose a medicare uhc aarp Medicare Advantage plan with drug coverage, you won't need a separate Part D plan.
Part D plans use formularies, which are lists of covered medications organized into tiers. Each tier has different cost-sharing requirements:
- Tier 1 – Preferred generic drugs (lowest cost)
- Tier 2 – Generic drugs
- Tier 3 – Preferred brand-name drugs
- Tier 4 – Non-preferred brand-name drugs
- Tier 5 – Specialty medications (highest cost)
Understanding the Coverage Gap
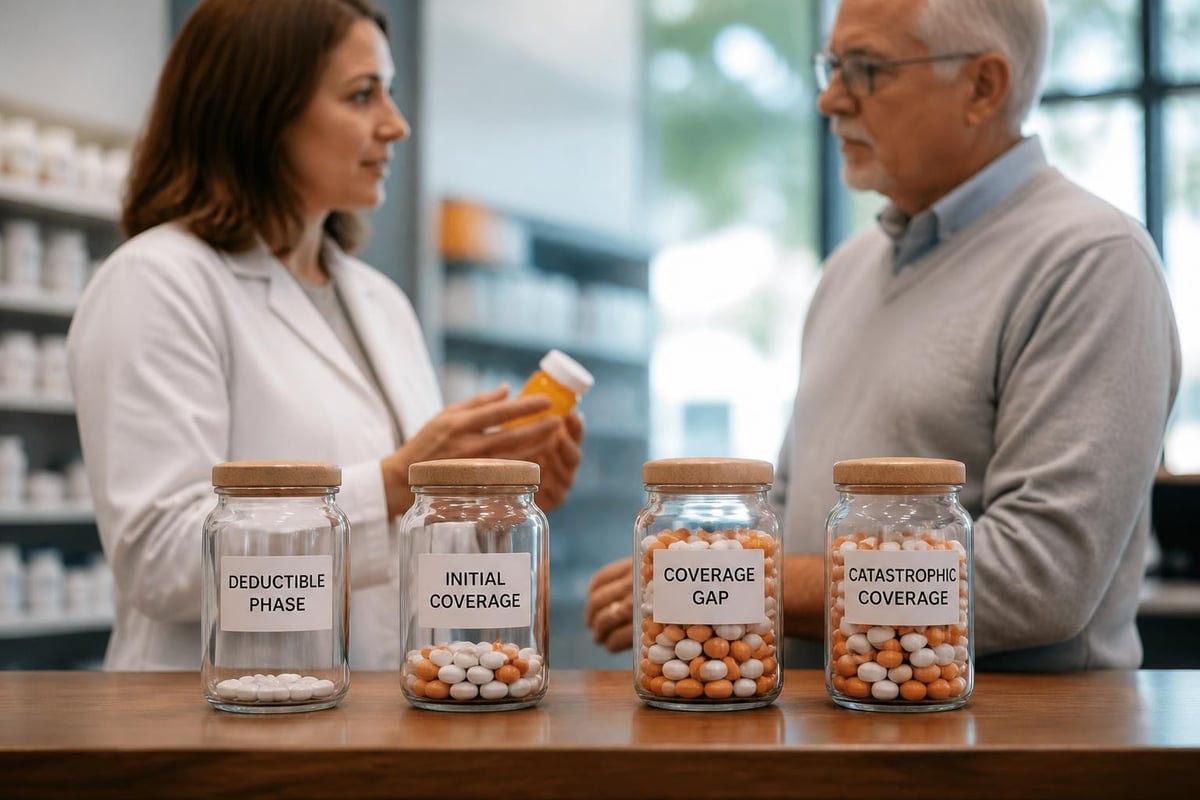
The Medicare Part D coverage gap, sometimes called the "donut hole," occurs after you and your plan have spent a certain amount on covered drugs ($5,300 in 2026). During this phase, you pay 25% of the cost for brand-name and generic drugs until you reach catastrophic coverage.
Important note: Not all medications count toward closing the coverage gap. Only your out-of-pocket costs and manufacturer discounts on brand-name drugs count toward the threshold.
Residents in areas like Greensboro and surrounding communities should review which pharmacies are in-network for their chosen Part D plan, as using out-of-network pharmacies typically results in higher costs or no coverage at all.
Medicare Supplement Plans (Medigap) from UHC AARP
AARP Medicare Supplement plans work fundamentally differently than Medicare Advantage. These plans supplement Original Medicare by helping pay for costs that Medicare doesn't cover, such as copayments, coinsurance, and deductibles.
With medicare uhc aarp Medigap coverage, you keep Original Medicare as your primary insurance and use the supplement plan to reduce out-of-pocket expenses. This gives you freedom to see any doctor or hospital that accepts Medicare nationwide, without network restrictions.
Available Medigap Plan Letters
Medicare Supplement plans are standardized by the federal government and identified by letters. UnitedHealthcare AARP offers several plan options:
- Plan G – Most comprehensive coverage; covers everything except Part B deductible
- Plan N – Lower premiums with modest copays for doctor and emergency room visits
- Plan F (only available if Medicare-eligible before 2020) – Covers all Medicare cost-sharing
- High Deductible Plan G – Lower monthly premiums with higher deductible before coverage begins
| Feature | Plan G | Plan N | High Deductible Plan G |
|---|---|---|---|
| Part A deductible | Covered | Covered | After deductible met |
| Part B deductible | Not covered | Not covered | After deductible met |
| Part B coinsurance | Covered | Copays apply | After deductible met |
| Monthly premium | Higher | Lower | Lowest |
Those exploring Medicare Supplement options should note that Medigap plans don't include prescription drug coverage. You'll need a separate Part D plan if you want prescription coverage with a Medicare Supplement policy.
Comparing Medicare Advantage vs Medicare Supplement
Choosing between a medicare uhc aarp Medicare Advantage plan and a Medicare Supplement plan represents one of the most significant decisions you'll make regarding Medicare coverage. Each approach has distinct advantages and limitations.
Medicare Advantage advantages:
- Often lower monthly premiums (some $0 premium plans available)
- Built-in prescription drug coverage on most plans
- Extra benefits like dental, vision, and fitness programs
- Out-of-pocket maximum provides financial protection
- All-in-one coverage simplicity
Medicare Advantage considerations:
- Network restrictions may limit provider choices
- Referrals often required for specialists
- Coverage varies by geographic area
- Plan benefits can change annually
Medicare Supplement advantages:
- Freedom to see any Medicare-accepting provider nationwide
- Predictable costs with minimal out-of-pocket expenses
- No referrals needed for specialists
- Guaranteed renewable coverage
- Benefits don't change from year to year
Medicare Supplement considerations:
- Higher monthly premiums than many Medicare Advantage plans
- No prescription drug coverage included
- No extra benefits like dental or vision
- No out-of-pocket maximum (though total costs are typically lower)
Your healthcare needs, budget, and lifestyle preferences should guide your decision. People who travel frequently or want provider flexibility often prefer Medicare Supplement plans, while those seeking comprehensive coverage with lower premiums may choose Medicare Advantage.
Enrollment Periods and Eligibility
Understanding when you can enroll in medicare uhc aarp plans prevents coverage gaps and potential penalties. Several enrollment periods govern Medicare plan selection.
Initial Enrollment Period
Your Initial Enrollment Period begins three months before you turn 65, includes your birth month, and extends three months after. This seven-month window is your first opportunity to enroll in Medicare and choose a UnitedHealthcare AARP plan.
Timeline breakdown:
- Three months before your 65th birthday – enrollment opens
- Your birthday month – prime enrollment time
- Three months after – enrollment window closes
Missing this window can result in late enrollment penalties for Part B and Part D that last your lifetime.
Annual Enrollment Period
The Annual Enrollment Period (AEP) runs from October 15 through December 7 each year. During this time, anyone with Medicare can:
- Switch from Original Medicare to Medicare Advantage
- Change from one Medicare Advantage plan to another
- Drop Medicare Advantage and return to Original Medicare
- Add, drop, or change Part D prescription drug plans
Changes made during AEP take effect January 1 of the following year.
Special Enrollment Periods
Certain qualifying events trigger Special Enrollment Periods outside the standard timeframes:
- Moving outside your current plan's service area
- Losing employer-sponsored coverage
- Moving into a nursing home
- Qualifying for Medicaid or Extra Help
- Plan contract termination by Medicare
For those in the Triad Area who need guidance on Medicare help and enrollment timing, understanding these periods ensures you don't miss critical deadlines.
Costs Associated with UHC AARP Medicare Plans
Medicare costs extend beyond monthly premiums. Understanding the full financial picture helps you choose the right medicare uhc aarp plan and budget appropriately.
Premium Costs
Monthly premiums vary significantly based on plan type and location. Medicare Advantage premiums can range from $0 to over $200 per month, while Medicare Supplement premiums typically range from $100 to $300+ monthly depending on the plan letter, your age, and location.
You'll also pay:
- Part B premium ($185 for most people in 2026)
- Part D premium (if you have a standalone drug plan)
- AARP membership fee (if required or desired for additional benefits)
Additional Cost-Sharing
Beyond premiums, expect to pay cost-sharing when you receive healthcare services:
- Deductibles – Amount you pay before coverage begins
- Copayments – Fixed dollar amounts for specific services
- Coinsurance – Percentage of costs you share with the plan
Medicare Advantage plans have annual out-of-pocket maximums, while Medicare Supplement plans minimize cost-sharing but lack this cap. If you're exploring Medicare Advantage in the Triad, compare the total annual costs including premiums and expected out-of-pocket expenses.
Extra Benefits and Member Perks
One advantage of medicare uhc aarp plans is the range of extra benefits many plans include. These go beyond what Original Medicare covers and can provide significant value.
Health and Wellness Benefits
Common additional benefits include:
- Dental coverage for preventive care and sometimes major services
- Vision benefits including eye exams and eyewear allowances
- Hearing aid coverage and audiology services
- Fitness memberships at participating gyms and YMCAs
- Over-the-counter product allowances for health items
Telehealth and Digital Services
Many plans now emphasize virtual care options, including 24/7 telehealth access, virtual visits with doctors, and online health management tools. The MyAARPMedicare member portal provides digital access to plan information, claims, and provider directories.
Care Coordination Services
Some medicare uhc aarp Medicare Advantage plans offer care coordination support, particularly Special Needs Plans. These services may include:
- Nurse hotlines for medical questions
- Care management for chronic conditions
- Medication therapy management
- Home health coordination
- Transition of care support after hospital discharge
Provider Networks and Coverage Areas
Network adequacy is crucial when evaluating Medicare Advantage plans. UnitedHealthcare AARP maintains extensive provider networks across the country, but coverage specifics vary by location and plan type.
Finding In-Network Providers
Before enrolling in a medicare uhc aarp Medicare Advantage plan, verify that your current doctors and preferred hospitals participate in the plan's network. UnitedHealthcare's online provider directory allows you to search by:
- Provider name
- Specialty
- Facility type
- Location (zip code or city)
HMO plans typically require you to stay in-network except for emergencies, while PPO plans allow out-of-network care at higher costs. Residents throughout High Point, Winston Salem, and surrounding communities should confirm local provider participation before selecting a plan.
Prescription Drug Coverage Networks
Part D plans and Medicare Advantage plans with drug coverage also use pharmacy networks. Preferred pharmacies offer lower copays than standard network pharmacies, and mail-order options often provide 90-day supplies at reduced costs.
Check whether your current pharmacy participates in the plan's network and at what tier (preferred, standard, or out-of-network) to accurately estimate your prescription costs.
How to Choose the Right Medicare UHC AARP Plan
Selecting the appropriate medicare uhc aarp plan requires evaluating your healthcare needs, financial situation, and personal preferences. A systematic approach ensures you choose coverage that serves you well.
Assess Your Healthcare Needs
Start by documenting your current healthcare utilization:
- List all doctors and specialists you see regularly
- Document current medications and dosages
- Note any planned procedures or surgeries
- Consider your typical healthcare spending patterns
- Evaluate your geographic flexibility needs
Compare Total Annual Costs
Don't focus solely on monthly premiums. Calculate estimated total annual costs including:
- Monthly premiums (×12 months)
- Plan deductibles
- Expected copays for regular doctor visits
- Prescription drug costs at each plan's pricing
- Potential out-of-pocket maximum if you have significant health needs
Use this formula:
Total Cost = (Monthly Premium × 12) + Deductible + Expected Copays/Coinsurance + Prescription Costs
Review Plan Ratings
Medicare.org provides plan ratings based on quality measures, member satisfaction, and plan performance. Medicare assigns star ratings from 1 to 5 stars, with higher ratings indicating better plan quality.
Plans with 4 stars or higher generally demonstrate strong performance in areas like customer service, preventive care, and chronic condition management.
Common Questions About Medicare UHC AARP Plans
Do I Need AARP Membership
While AARP endorses these plans, membership is not required for most medicare uhc aarp plan types. Some plans may offer premium discounts or enhanced benefits for AARP members, but membership is optional. The annual AARP membership fee is minimal (currently around $16) compared to potential savings.
Can I Keep My Current Doctors
With Medicare Supplement plans, you can see any doctor or facility that accepts Medicare anywhere in the United States. With Medicare Advantage plans, staying in-network typically provides the best value, though PPO plans allow out-of-network care at higher costs. Always verify provider participation before enrolling.
What Happens If I Move
If you move outside your Medicare Advantage plan's service area, you qualify for a Special Enrollment Period to choose a new plan available in your new location. Medicare Supplement plans provide nationwide coverage, so geographic moves don't affect your coverage. However, moving may trigger the ability to change Medigap plans without underwriting in some circumstances.
Can I Switch Plans
You can change Medicare Advantage and Part D plans during the Annual Enrollment Period each fall. Medicare Supplement plans can be changed at any time, but if you're past your Medigap Open Enrollment Period, you may face medical underwriting and potentially higher premiums or coverage denial.
Getting Professional Guidance
Navigating medicare uhc aarp plan options can be complex, especially when comparing multiple plan types, understanding coverage details, and projecting annual costs. Professional guidance ensures you make an informed decision that aligns with your healthcare needs and financial goals.
Independent insurance advisors provide personalized support without the pressure of sales quotas. They can explain plan differences, help you compare options from multiple carriers, and walk you through the enrollment process.
For personalized assistance, contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your Medicare options with experienced professionals who understand the local healthcare landscape in Kernersville and surrounding areas.
Choosing the right Medicare coverage requires understanding how medicare uhc aarp plans work, comparing your options, and selecting coverage that meets your specific needs. Whether you opt for Medicare Advantage, Medicare Supplement, or Part D prescription drug coverage, the decision should reflect your healthcare utilization, budget, and preferences. Working with experienced professionals who can provide clear guidance without pressure makes the process much simpler. Moser Insurance Group Inc helps individuals and families throughout the Triad Area understand their Medicare options with personalized support, ensuring you make confident insurance decisions. Reach out today at 336-862-1763 to get started with your Medicare planning.
Recent Comments