

Understanding health insurance Medicare options becomes essential as you approach age 65 or qualify through specific disabilities. Medicare provides vital healthcare coverage for millions of Americans, but navigating its different parts, enrollment periods, and supplemental options can feel overwhelming without clear guidance. This comprehensive guide breaks down everything you need to know about Medicare coverage in 2026, helping you make informed decisions about your healthcare future.
Understanding the Foundation of Medicare Coverage
Medicare serves as the primary health insurance program for Americans aged 65 and older, along with certain younger individuals with disabilities or specific conditions. The program divides into distinct parts, each covering different healthcare services and carrying unique costs.
Part A covers hospital insurance, including inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services. Most people pay no premium for Part A because they or their spouse paid Medicare taxes while working. However, deductibles and coinsurance still apply.
Part B provides medical insurance that covers doctor visits, outpatient care, preventive services, durable medical equipment, and some home health services. Unlike Part A, Part B requires a monthly premium that varies based on income level. In 2026, the standard Part B premium reflects annual adjustments tied to healthcare costs.
How Medicare Part C and Part D Complete the Picture
Part C, known as Medicare Advantage, represents an alternative way to receive Medicare benefits through private insurance companies approved by Medicare. These plans include all Part A and Part B coverage, and most include prescription drug coverage as well.
Part D specifically addresses prescription drug coverage. If you choose Original Medicare (Parts A and B), you'll need to add a standalone Part D plan to get medication coverage. Medicare Advantage plans typically bundle this coverage into a single policy.
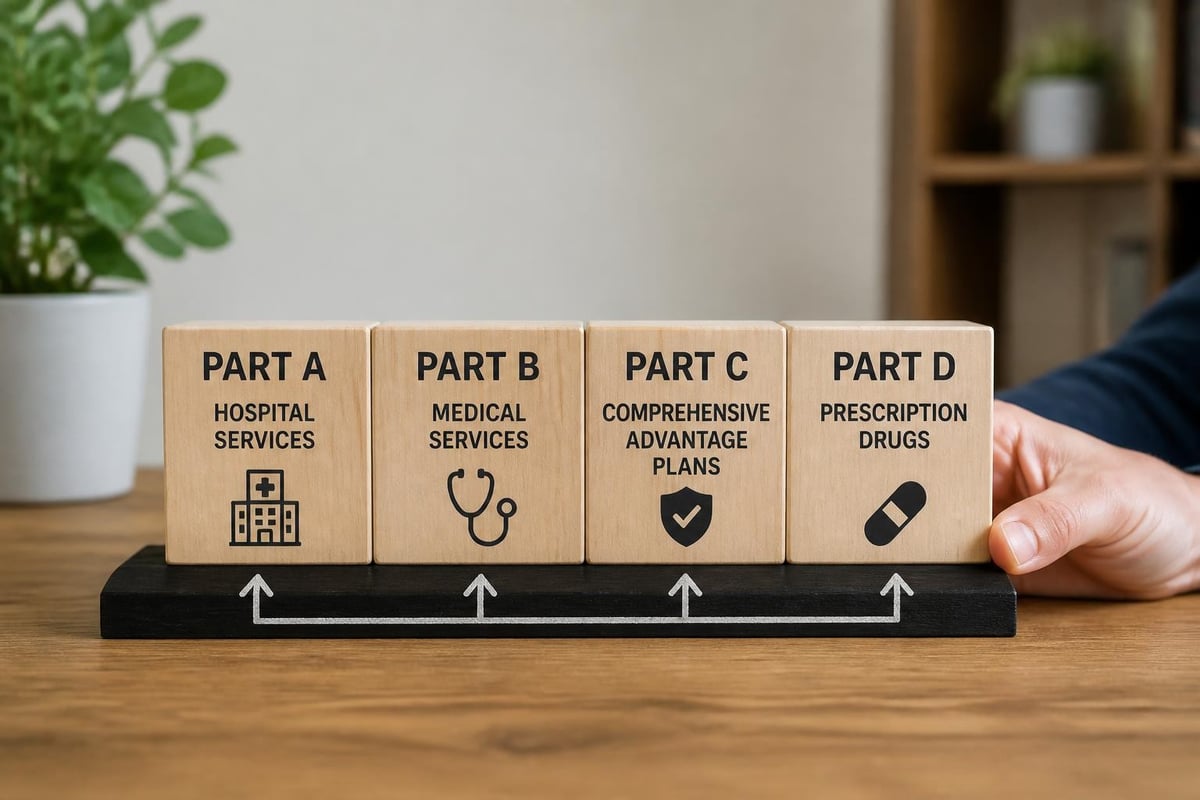
| Medicare Part | What It Covers | Monthly Premium | How You Get It |
|---|---|---|---|
| Part A | Hospital, skilled nursing, hospice | Usually $0 | Automatic at 65 if eligible |
| Part B | Doctor visits, outpatient care | Standard amount (income-based) | Must enroll during period |
| Part C | All A & B benefits plus extras | Varies by plan | Choose private plan |
| Part D | Prescription medications | Varies by plan | Add to Original or in Advantage |
Enrollment Periods and Critical Timing Decisions
Your Initial Enrollment Period spans seven months, starting three months before your 65th birthday month, including that month, and extending three months after. Missing this window can result in permanent late enrollment penalties that increase your premiums for life.
The Annual Enrollment Period runs from October 15 through December 7 each year. During this time, you can switch between Original Medicare and Medicare Advantage, change Medicare Advantage plans, or modify your Part D prescription drug coverage. Changes take effect January 1 of the following year.
Special Enrollment Periods apply in specific situations:
- Moving outside your plan's service area
- Losing employer-based coverage
- Qualifying for Medicaid
- Moving into or out of a skilled nursing facility
- Experiencing certain other qualifying life events
Understanding how Medicare enrollment works helps you avoid costly gaps in coverage or unnecessary penalties that impact your budget for years to come.
Comparing Original Medicare With Medicare Advantage Plans
Original Medicare (Parts A and B) offers nationwide coverage and freedom to see any doctor or specialist who accepts Medicare without referrals. You pay 20% coinsurance for most Part B services after meeting the annual deductible, and there's no annual out-of-pocket maximum.
Medicare Advantage plans work differently. These plans contract with specific networks of doctors and hospitals, similar to employer health insurance. Most require you to choose primary care physicians and get referrals for specialists.
Key Advantages of Medicare Advantage Plans
- Bundled coverage that includes medical, hospital, and usually prescription drugs in one plan
- Annual out-of-pocket maximums that cap your yearly healthcare spending
- Extra benefits like dental, vision, hearing, fitness memberships, and over-the-counter allowances
- Lower or $0 premiums in many markets, though you still pay the Part B premium
Medicare Advantage trade-offs include network restrictions, prior authorization requirements for certain services, and geographical limitations. If you travel frequently or spend winters in another state, these factors become particularly important considerations. Exploring top Medicare Advantage plans available in your area helps you compare specific benefits and costs.
What Original Medicare Doesn't Cover
Traditional Medicare leaves significant gaps that surprise many new beneficiaries. Understanding these limitations helps you plan for additional coverage needs.
Original Medicare doesn't cover:
- Routine dental care, dentures, or dental surgery
- Eye examinations for prescription glasses or contact lenses
- Hearing aids or hearing examinations
- Long-term care or custodial care in nursing homes
- Most care received outside the United States
- Cosmetic surgery
- Acupuncture (except for chronic lower back pain)
- Routine foot care
Prescription drug coverage also remains absent from Original Medicare unless you add a Part D plan. Without drug coverage, you face potential late enrollment penalties and pay full retail prices for medications.
Medicare Supplement Plans Fill the Gaps
Medicare Supplement insurance, also called Medigap, works alongside Original Medicare to cover costs like deductibles, coinsurance, and copayments. Private insurance companies sell these standardized plans, labeled with letters like Plan G, Plan N, and Plan F (available only to those eligible for Medicare before 2020).
Plan G represents the most comprehensive option available to new Medicare beneficiaries in 2026. After you pay the annual Part B deductible, Plan G covers virtually all other out-of-pocket costs, including:
- Part A deductibles and coinsurance
- Part B coinsurance and copayments
- First three pints of blood
- Skilled nursing facility coinsurance
- Part B excess charges
- Foreign travel emergency coverage up to plan limits
Medicare Supplement Plans provide predictable healthcare budgeting since you know your premium and understand your minimal out-of-pocket exposure. However, you must purchase a separate Part D plan for prescription coverage.
Calculating Your Total Medicare Costs
Health insurance Medicare expenses extend beyond premiums. Creating a complete cost picture requires understanding all potential charges.
Your monthly premium costs include:
- Part B premium – standard amount adjusted annually based on income
- Part D premium – varies by plan selection
- Medigap premium – if choosing supplemental coverage (varies widely by age, location, and plan type)
- Medicare Advantage premium – often $0 but varies by plan and region
Additional costs depend on your coverage choice:
- Deductibles – annual amounts before coverage begins
- Copayments – fixed amounts per service or prescription
- Coinsurance – percentage of costs you pay after deductibles
Income-Related Monthly Adjustment Amounts (IRMAA) increase Part B and Part D premiums for individuals earning above certain thresholds. In 2026, these adjustments apply to Medicare beneficiaries with modified adjusted gross incomes exceeding $103,000 (individual) or $206,000 (married filing jointly), based on tax returns from two years prior.
| Income Level (Individual) | Part B Monthly Surcharge | Part D Monthly Surcharge |
|---|---|---|
| $103,000 or less | $0 | $0 |
| $103,001–$129,000 | Additional amount | Additional amount |
| $129,001–$161,000 | Higher additional amount | Higher additional amount |
| $161,001–$193,000 | Even higher amount | Even higher amount |
| $500,000 or more | Maximum surcharge | Maximum surcharge |
Choosing Between Medicare Advantage and Original Medicare Plus Medigap
This decision represents the most significant health insurance Medicare choice you'll make. Neither option proves universally superior-the right choice depends on your specific circumstances, health status, budget, and preferences.
Consider Medicare Advantage if you:
- Prefer comprehensive coverage bundled in one plan with predictable copays
- Want dental, vision, and hearing benefits included
- Don't mind network restrictions and referral requirements
- Live in one area year-round without extensive travel
- Appreciate out-of-pocket maximum protection
- Have limited prescription drug needs
Choose Original Medicare with Medigap if you:
- Value complete freedom to see any Medicare-accepting provider nationwide
- Want minimal out-of-pocket costs beyond premiums
- Travel extensively or split time between multiple states
- Prefer simplicity without prior authorization requirements
- Have complex health conditions requiring specialist access
- Don't need dental and vision coverage or can purchase it separately
Special Situations That Affect Medicare Coverage
Working past age 65 with employer coverage creates unique decisions. If your employer has 20 or more employees, your group health insurance typically serves as primary coverage, and you can delay Part B enrollment without penalties. You'll sign up during a Special Enrollment Period when employment ends or coverage terminates.
Employers with fewer than 20 employees require Medicare as primary coverage at 65. Delaying Part B enrollment in this situation results in coverage gaps and late enrollment penalties.
Veterans with VA benefits maintain those services alongside Medicare. VA coverage doesn't satisfy Medicare requirements, so most veterans benefit from Medicare enrollment even with existing VA access. The programs work together, with Medicare often covering services closer to home or from civilian providers.
End-stage renal disease and ALS (Lou Gehrig's disease) qualify individuals for Medicare regardless of age. These conditions trigger specific enrollment rules and timing that differ from standard age-based eligibility.
Prescription Drug Coverage Strategies
Part D prescription drug plans vary significantly in premiums, deductibles, covered medications (formularies), and pharmacy networks. Reviewing your plan annually during the Annual Enrollment Period ensures your coverage still matches your medication needs.
Each Part D plan organizes medications into tiers:
- Tier 1: Preferred generic drugs (lowest cost)
- Tier 2: Generic drugs
- Tier 3: Preferred brand-name drugs
- Tier 4: Non-preferred brand-name drugs
- Tier 5: Specialty medications (highest cost)
Your out-of-pocket costs depend on which tier contains your medications. Plans that look inexpensive based on premium alone might prove costly if your specific drugs fall into higher tiers or require prior authorization.
The Part D coverage gap, historically called the "donut hole," has closed significantly through recent reforms. In 2026, you pay 25% of the price for brand-name and generic drugs during the coverage gap phase, with manufacturer discounts and Medicare contributions covering the remaining costs.
Preventive Care and Wellness Benefits
Medicare covers numerous preventive services at no cost when you use providers who accept Medicare assignment. These benefits help detect health issues early when treatment proves most effective.
Covered preventive services include:
- Annual wellness visits and personalized prevention plan services
- Cardiovascular disease screening
- Diabetes screening and diabetes self-management training
- Mammograms and Pap tests
- Prostate cancer screening
- Colorectal cancer screening including colonoscopies
- Bone mass measurements
- Pneumococcal, influenza, and hepatitis B vaccines
- Depression screening
- Nutrition therapy services for diabetes and kidney disease
Medicare Advantage plans often expand these offerings with additional wellness programs, fitness memberships, telehealth services, and care coordination support. Understanding Medicare basics helps you maximize these valuable preventive benefits.
Making Informed Coverage Decisions
Selecting the right health insurance Medicare plan requires evaluating your current health status, prescription medications, preferred doctors and hospitals, budget constraints, and future healthcare expectations.
Start by creating a comprehensive list of:
- All current prescription medications with dosages
- Doctors and specialists you regularly visit
- Planned surgeries or treatments in the coming year
- Medical equipment needs
- Dental, vision, or hearing care requirements
Use the Medicare Plan Finder tool on Medicare.gov to compare specific plans available in your ZIP code. Enter your medications and preferred pharmacies to see actual cost estimates rather than general plan features.
Request information from multiple insurance carriers. While Medicare Supplement plans are standardized (Plan G from one company offers identical coverage to Plan G from another), premiums vary significantly between companies. Comparing quotes saves hundreds of dollars annually.
Consider working with an independent insurance agent who represents multiple carriers. Unlike captive agents who sell for one company, independent agents compare options across the market to find plans matching your specific needs and budget. Many North Carolina residents appreciate getting Medicare help from local experts familiar with regional plan options and provider networks.
Understanding Coordination With Other Insurance
If you maintain employer coverage past 65, understanding coordination of benefits prevents claim denials and coverage gaps. Primary coverage pays first, then secondary coverage addresses remaining eligible expenses according to coordination of benefits rules.
Medicare becomes secondary to employer coverage when you work at companies with 20+ employees. Your group plan pays first, Medicare pays second on covered services. This arrangement often provides excellent comprehensive coverage since Medicare fills many employer plan gaps.
When employer coverage ends, you have eight months to enroll in Part B without penalties through a Special Enrollment Period. Document your coverage end date carefully, as proof is required to avoid late enrollment penalties.
COBRA continuation coverage doesn't count as employer coverage for Medicare purposes. If you elect COBRA after leaving employment, you should enroll in Medicare when first eligible rather than waiting until COBRA expires, as COBRA becomes secondary to Medicare.
Health insurance from the marketplace (ACA plans) doesn't coordinate with Medicare. Once you become eligible for Medicare, you typically cannot maintain marketplace coverage or receive premium tax credits. Attempting to keep both results in the marketplace plan terminating when Medicare eligibility is discovered.
Assessing Medicare Advantage Plan Quality
Medicare rates all Medicare Advantage and Part D plans using a star rating system from 1 to 5 stars. These ratings measure quality and performance across multiple categories including member satisfaction, staying healthy, managing chronic conditions, and member experience with the plan.
Plans earning 4 stars or higher receive recognition as high-performing plans. These ratings update annually and appear on Medicare.gov plan comparison tools.
Key quality indicators beyond star ratings include:
- Network adequacy: Sufficient doctors, specialists, and hospitals in your area
- Prior authorization requirements: How often the plan requires approval before services
- Appeals and grievances data: How frequently members dispute coverage decisions
- Member retention rates: Percentage of members who keep the plan year-over-year
- Customer service responsiveness: Call wait times and issue resolution
Reading actual member reviews provides insights into real-world experiences with plan administration, claim payments, and customer service quality. State Health Insurance Assistance Programs (SHIP) offer free, unbiased counseling to help evaluate plan quality and suitability.
Regional Variations in Medicare Options
Health insurance Medicare choices vary dramatically by geographic location. Urban areas typically offer dozens of Medicare Advantage plans with competitive benefits and premiums, while rural regions might have limited options.
Provider networks also differ by region. A Medicare Advantage plan with excellent doctors and hospitals in one county might offer poor network access in a neighboring county despite being available in both locations.
Medigap premiums fluctuate significantly based on where you live. The same Plan G coverage might cost $125 monthly in one state and $200 monthly in another due to state regulations, competition levels, and regional healthcare costs.
Part D prescription drug plans similarly vary by region. Medicare divides the country into 34 prescription drug regions, and available plans differ by region. A plan with excellent coverage and low costs in one region might not even be available in another.
Before moving to a new area, research Medicare options in your destination. Medicare Advantage plans generally don't cover non-emergency care outside their service areas, creating potential coverage gaps if you relocate.
Navigating health insurance Medicare options requires understanding multiple coverage types, costs, and enrollment rules that impact your healthcare access and financial security for years to come. Working with knowledgeable professionals who explain your choices without pressure helps you select coverage matching your unique health needs and budget. Moser Insurance Group Inc specializes in guiding individuals and families through Medicare decisions with clear education and personalized support, helping you approach Medicare with confidence rather than confusion.
Recent Comments