

Life insurance decisions can feel overwhelming, especially when you're trying to balance protection for your family with making smart financial choices. A term insurance plan with return of premium has emerged as a middle ground between traditional term policies and permanent coverage, offering death benefit protection while promising to refund your premiums if you outlive the policy. This hybrid approach appeals to people in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, who want life insurance protection without feeling like they're throwing money away. Understanding how these policies work, what they cost, and whether they align with your financial goals requires careful consideration of several factors.
Understanding Term Insurance Plans With Premium Return Features
A term insurance plan with return of premium combines the affordable protection of traditional term coverage with a savings component. Unlike standard term policies that simply expire after the coverage period ends, these plans return 100% of your paid premiums if you survive the term.
The mechanics are straightforward: you select a coverage amount and term length (typically 20 or 30 years), pay higher premiums than standard term insurance, and receive all your premiums back if you're alive when the policy ends. This feature transforms what many perceive as a pure expense into a forced savings vehicle with built-in life insurance protection.
Key Differences From Traditional Term Coverage
When comparing these policies to standard term insurance, the premium difference stands out immediately. Return of premium riders typically cost 30% to 50% more than comparable term policies without this feature, according to term life insurance experts.
Traditional term policies offer:
- Lower monthly premiums
- Pure death benefit protection
- No cash value or refund
- Expiration at term end without payout
Return of premium policies provide:
- Higher monthly premiums
- Death benefit protection during the term
- Full premium refund if you survive
- Potential partial refunds for early cancellation
The choice between these options depends largely on your financial priorities and whether you value the refund feature enough to pay significantly higher premiums throughout the policy term.
How Premium Refunds Work in Practice
The refund mechanism in a term insurance plan with return of premium operates on a straightforward timeline. During the coverage period, you pay premiums just like any other life insurance policy. If death occurs during the term, your beneficiaries receive the full death benefit, just as they would with traditional term coverage.
The distinguishing factor emerges at the end of the term. If you're alive when the policy expires, the insurance company returns every dollar you paid in premiums. This creates a "breakeven" scenario where you received decades of life insurance protection at no net cost.
Partial Refund Provisions
Many return of premium policies include partial refund options if you cancel before the term ends. These provisions vary significantly between carriers, with some offering:
| Years Completed | Typical Refund Percentage |
|---|---|
| 5-10 years | 0-20% of premiums paid |
| 11-15 years | 30-50% of premiums paid |
| 16-20 years | 60-80% of premiums paid |
Some insurers structure their policies with no partial refunds, while others provide graduated schedules that increase refund percentages as you approach the end of the term. Reading the policy details carefully before purchasing helps you understand exactly what you'll receive if circumstances change.
Financial Analysis: Is the Higher Cost Worth It?
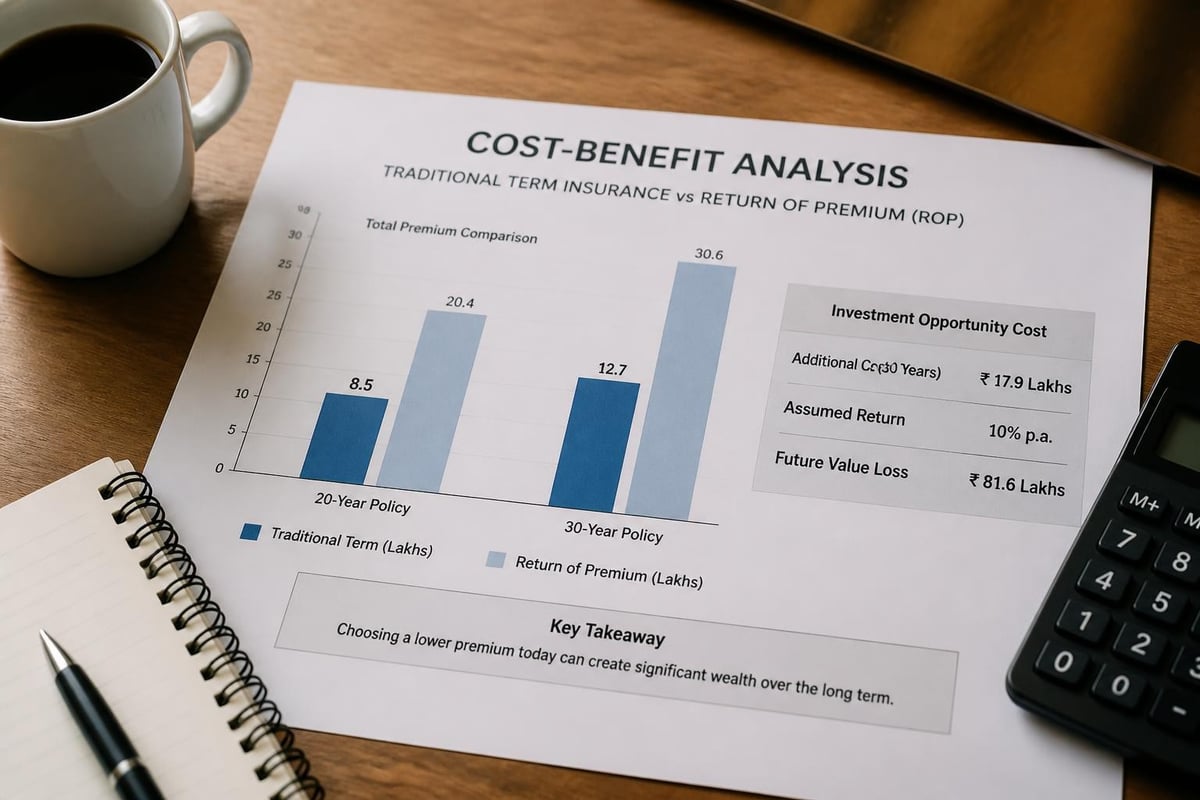
Determining whether a term insurance plan with return of premium makes financial sense requires comparing the total premium difference against what you could earn by investing that money elsewhere. This opportunity cost calculation reveals whether the guaranteed refund beats alternative strategies.
Consider a 40-year-old purchasing $500,000 in coverage for 30 years. A standard term policy might cost $60 monthly ($720 annually), while a return of premium version could cost $95 monthly ($1,140 annually). Over 30 years, you'd pay $21,600 for traditional term versus $34,200 for return of premium.
The Investment Comparison
The $420 annual difference between these policies represents money you could invest independently. If invested at a 6% average annual return for 30 years, that $420 yearly would grow to approximately $35,200. This exceeds the $34,200 you'd receive back from the return of premium policy.
However, this calculation assumes disciplined investing behavior that many people struggle to maintain. The guaranteed refund from a term insurance plan with return of premium provides forced savings that some individuals prefer over self-directed investment strategies.
Factors that favor return of premium:
- Guaranteed refund regardless of market performance
- Built-in discipline for those who struggle to save
- No investment knowledge required
- Tax-free premium return
- Peace of mind from knowing you'll recoup costs
Factors that favor traditional term with separate investing:
- Potentially higher returns through market investments
- Greater liquidity and access to funds during the term
- Lower initial premium commitment
- Flexibility to adjust savings rate based on circumstances
Different providers offer varying premium structures, as detailed by carriers like HDFC Life and Kotak Life, making comparison shopping essential.
Tax Implications and Considerations
The tax treatment of a term insurance plan with return of premium adds another layer to the decision-making process. Generally, the premium refund you receive at the end of the term is not taxable income because the IRS considers it a return of your own money rather than earnings.
Death benefits paid to beneficiaries remain tax-free regardless of whether you have a standard term or return of premium policy. This consistent treatment across policy types means tax considerations shouldn't heavily influence your choice between the two options.
Estate Planning Perspectives
For individuals concerned about estate planning, return of premium policies create an interesting dynamic. The refunded premiums become part of your estate if you survive the term, potentially subject to estate taxes if your total estate exceeds federal or state thresholds.
Some families incorporate these policies into broader financial strategies, planning to use the refunded premiums for retirement expenses, grandchildren's education, or other legacy goals. Working with financial advisors helps integrate these policies into comprehensive estate plans that address multiple generations' needs.
Who Benefits Most From Return of Premium Policies
A term insurance plan with return of premium appeals most strongly to specific demographic and psychological profiles. Understanding whether you fit these patterns helps determine if this coverage type aligns with your needs.
Young families purchasing life insurance often find return of premium attractive because they're looking at 20-30 year terms that will conclude around retirement age. The prospect of receiving a significant lump sum just as they're transitioning out of working years provides dual benefits: protection during child-rearing years and retirement boost if they survive.
Risk Tolerance and Savings Discipline
People with low risk tolerance frequently gravitate toward return of premium policies. The guaranteed refund eliminates the possibility of "wasting" premium dollars, providing certainty that appeals to conservative financial personalities.
Those who struggle with savings discipline also benefit significantly. The higher premiums function as forced savings that accumulate invisibly until the term ends. For individuals who might otherwise spend extra money rather than invest it, this structure creates wealth accumulation that wouldn't otherwise occur.
Ideal candidates include:
- Risk-averse individuals who dislike uncertainty
- People entering their 30s and 40s with long time horizons
- Families who want guaranteed protection plus savings
- Those with inconsistent savings habits
- Individuals who can comfortably afford higher premiums
Less suitable candidates include:
- Disciplined investors who can beat guaranteed returns
- Budget-conscious families needing maximum coverage per dollar
- Older applicants facing prohibitively expensive premiums
- People who may need to cancel policies early
- Those prioritizing coverage amount over refund features
Residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, face these same considerations when evaluating life insurance options.
Comparing Return of Premium to Cash Value Policies
Beyond choosing between standard term and return of premium, shoppers also compare these policies against permanent insurance with cash value components. Understanding these distinctions prevents confusion about different product categories.
Permanent policies like whole life or universal life build cash value that grows over time and remains accessible through loans or withdrawals. A term insurance plan with return of premium doesn't build cash value during the term and only provides the refund at term end if you survive.
| Feature | Return of Premium Term | Whole Life | Universal Life |
|---|---|---|---|
| Coverage Duration | Fixed term (10-30 years) | Lifetime | Lifetime |
| Premium Cost | Moderate | Highest | High-Moderate |
| Cash Access During Term | None | Loans/withdrawals | Loans/withdrawals |
| Refund at Term End | 100% of premiums | N/A | N/A |
| Death Benefit | Level | Level | Flexible |
| Investment Component | None | Fixed | Variable |
Permanent policies cost significantly more than even return of premium term insurance, but they provide lifetime coverage rather than expiring after a set term. This fundamental difference makes them suitable for different purposes, as explained in resources about various life insurance types.
Application Process and Underwriting Requirements
Applying for a term insurance plan with return of premium follows similar underwriting processes as standard term insurance. Insurers evaluate your health, lifestyle, occupation, and family medical history to determine eligibility and premium rates.
The medical examination typically includes blood work, urinalysis, height and weight measurements, and blood pressure readings. Some carriers offer simplified underwriting for smaller coverage amounts, while larger policies almost always require full medical exams.
Factors Affecting Premium Rates
Your premium cost depends on multiple risk factors that insurers assess during underwriting:
- Age: Younger applicants receive significantly lower rates
- Health status: Chronic conditions increase premiums or may cause denial
- Tobacco use: Smokers pay 2-3 times more than non-smokers
- Family history: Patterns of heart disease, cancer, or diabetes affect pricing
- Occupation: High-risk jobs result in higher premiums
- Hobbies: Dangerous activities like skydiving increase rates
- Driving record: Multiple violations suggest higher mortality risk
Given the higher base cost of return of premium policies, even small rating adjustments can significantly impact your total premium outlay over 20-30 years. Improving health markers before applying, like losing weight or quitting smoking, can save thousands of dollars throughout the policy term.
Alternatives and Hybrid Strategies
Not everyone needs to choose exclusively between traditional term and return of premium policies. Several hybrid strategies allow you to capture benefits from multiple approaches simultaneously.
One common strategy involves purchasing a smaller return of premium policy alongside a larger traditional term policy. This combination provides substantial death benefit protection at affordable rates while still guaranteeing some premium refund if you survive the term.
Laddering Term Policies
Laddering involves purchasing multiple term policies with staggered expiration dates. You might buy:
- $300,000 in 10-year traditional term
- $200,000 in 20-year return of premium
- $100,000 in 30-year traditional term
This structure matches decreasing coverage needs as children become independent and mortgages get paid down, while the return of premium policy provides a guaranteed refund at a strategic point in your financial timeline.
Some families working with advisors implement convertibility options, purchasing traditional term policies with riders allowing conversion to permanent coverage later without new medical underwriting. This preserves flexibility as financial situations evolve.
Major carriers including Tata AIA, Bajaj Life, and Axis Max Life offer various policy structures that support these customized strategies.
Making Your Decision: Questions to Ask
Before committing to a term insurance plan with return of premium, evaluate your situation by answering several critical questions that reveal whether this product aligns with your needs.
Can you comfortably afford the higher premiums for the full term? Life changes over 20-30 years, and premium increases from renewals, policy changes, or adding riders might strain your budget. Ensure you can maintain payments even if income decreases or expenses increase.
What would you do with the premium difference if you bought traditional term instead? If your honest answer is "probably spend it," return of premium might serve you better than traditional term. If you'd genuinely invest the difference, calculate whether your expected returns justify foregoing the guaranteed refund.
How important is flexibility to access your money before the term ends? Return of premium policies lock up premium dollars until term end (with limited exceptions). If you might need this money for emergencies, education expenses, or opportunities, the illiquidity could prove problematic.
Coverage Amount Prioritization
Perhaps most importantly: Would the premium difference allow you to buy significantly more coverage with traditional term? For many families, especially those in the Triad Area working with advisors at locations in Greensboro, Kernersville, High Point, and Winston Salem, maximizing death benefit protection takes precedence over refund features.
A $500,000 return of premium policy might cost the same as a $750,000 traditional term policy. If your family needs $750,000 to maintain their lifestyle and pay off debts, the smaller coverage with refund features creates dangerous gaps.
Consulting with experienced insurance professionals who understand both your immediate protection needs and long-term financial goals helps clarify which policy structure serves you best. Resources like those available at Bandhan Life provide additional perspective on policy features and benefits.
Common Misconceptions About Premium Refunds
Several myths surround term insurance plans with return of premium that lead to confusion and sometimes poor purchasing decisions. Clarifying these misconceptions helps you evaluate these policies more accurately.
Misconception: "Return of premium policies build cash value like whole life insurance."
Reality: These policies don't accumulate accessible cash value during the term. You only receive the refund at term end if you survive.
Misconception: "The refund includes interest or investment returns."
Reality: Most policies refund exactly what you paid in premiums, with no interest added. You're receiving your own money back, not investment growth.
Misconception: "You can borrow against your premiums before the term ends."
Reality: Unlike permanent policies with cash value, return of premium term insurance generally doesn't allow policy loans.
Misconception: "All return of premium policies refund 100% if you cancel early."
Reality: Surrender schedules vary widely, with many policies offering zero refunds in early years and only partial refunds mid-term.
Understanding the True Economics
The insurance company invests your higher premiums throughout the term, earning returns that fund both the death benefit risk and your eventual refund. This structure explains why return of premium costs more but doesn't provide investment returns to you directly.
You're essentially paying the insurance company to manage your savings while providing life insurance protection. For some people, this arrangement offers value through forced discipline and guaranteed outcomes. For disciplined investors, it represents opportunity cost from below-market returns.
Health Changes and Policy Performance
One often-overlooked advantage of a term insurance plan with return of premium involves health deterioration scenarios. If you develop serious health conditions during the policy term, you've locked in coverage that would be expensive or impossible to replace.
Consider someone who purchases a 30-year return of premium policy at age 35, then develops diabetes and high blood pressure at age 50. Traditional term insurance would leave them without coverage at age 65 when they might still need protection. The return of premium policy not only continues coverage through age 65 but also refunds their premiums if they survive.
This creates a "best of both worlds" outcome: protection continued despite uninsurable health status, plus premium refund despite having had decades of high-risk coverage. This scenario particularly benefits people with family histories of conditions that typically develop in middle age.
Comparing Reapplication Challenges
Trying to replace term insurance after developing health conditions typically results in:
- Substantially higher premiums (often 2-3x original rates)
- Reduced coverage amounts due to insurability limits
- Complete denial for certain serious conditions
- Exclusion riders that limit coverage for specific health issues
The guaranteed coverage and refund from an existing return of premium policy avoids these complications entirely, providing security that traditional term policies lack once they expire.
For individuals and families seeking comprehensive guidance on life insurance options beyond just term policies, resources available through Moser Insurance Group Inc can help evaluate multiple coverage types and strategies. You can reach us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your specific needs.
A term insurance plan with return of premium offers guaranteed life insurance protection with the certainty of premium refunds if you outlive the policy, making it an attractive middle ground between traditional term coverage and permanent insurance. Whether this option suits your needs depends on your financial discipline, risk tolerance, coverage requirements, and long-term goals. At Moser Insurance Group Inc, we help individuals and families throughout the Triad Area understand all their insurance options, including term, whole life, and other coverage types, so you can make confident decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss which life insurance strategy aligns best with your family's protection and financial objectives.
Recent Comments