
Choosing the right coverage for yourself or your family represents one of the most important financial and wellness decisions you'll make. Health plans come in many forms, each designed to address different needs, budgets, and life circumstances. Whether you're approaching Medicare eligibility, seeking coverage for your family, or navigating insurance options for the first time, understanding the landscape of available plans helps you make informed choices. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, finding personalized guidance can make the difference between confusion and confidence.
Understanding Different Types of Health Plans
Health plans vary significantly in structure, cost, and coverage scope. The most common categories include Medicare plans, employer-sponsored coverage, individual market plans, and government programs. Each category serves distinct populations with unique features.
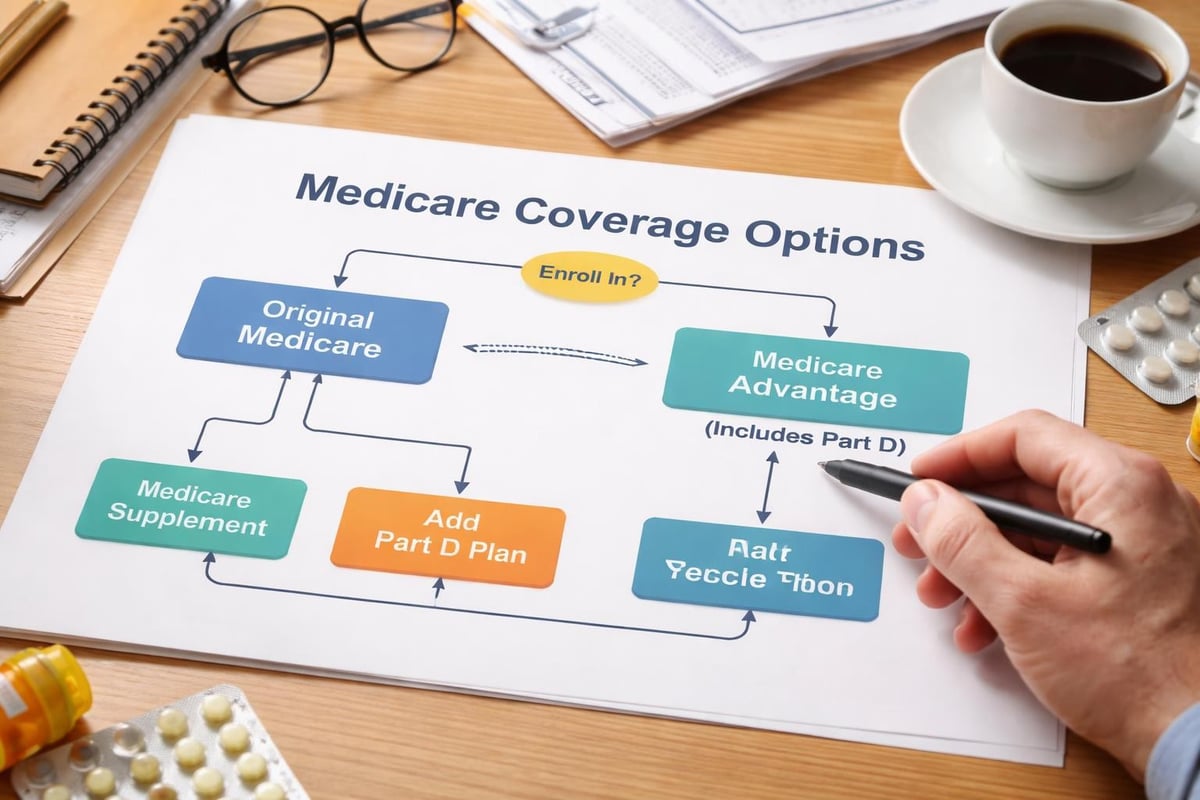
Medicare plans specifically serve individuals 65 and older, as well as certain younger people with disabilities. These include Original Medicare (Parts A and B), Medicare Advantage (Part C), and prescription drug coverage (Part D). Many beneficiaries in the Greensboro and Winston Salem areas benefit from understanding top Medicare Advantage plans that combine medical and prescription coverage.
Key Plan Categories
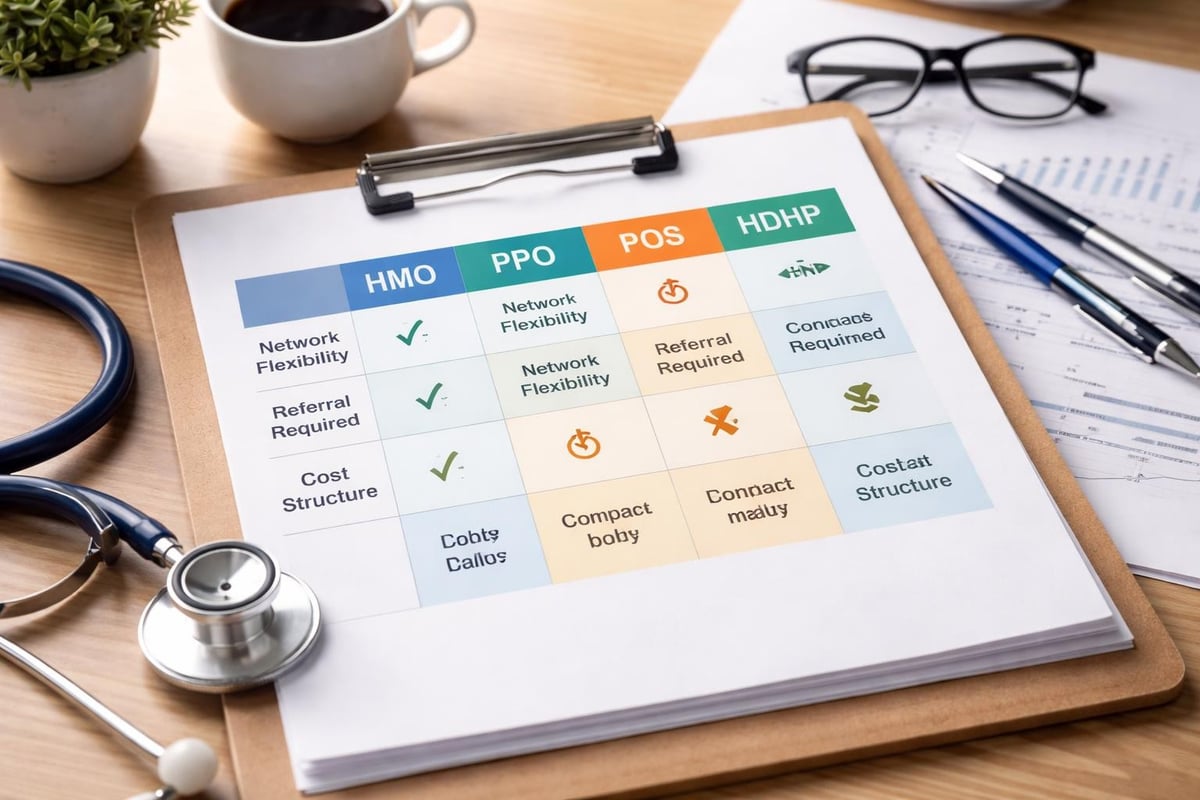
Different health plans offer varying levels of flexibility and cost structures:
- Health Maintenance Organizations (HMOs) require members to use network providers and obtain referrals for specialists
- Preferred Provider Organizations (PPOs) offer more flexibility but charge higher costs for out-of-network care
- Point of Service (POS) plans blend HMO and PPO features with partial out-of-network coverage
- High Deductible Health Plans (HDHPs) pair lower premiums with higher upfront costs and often include Health Savings Accounts
For Medicare beneficiaries, 5-star Medicare Advantage plans represent the highest-rated options based on quality and performance measures established by the Centers for Medicare and Medicaid Services.
Evaluating Coverage Options and Network Considerations
When comparing health plans, network adequacy plays a critical role in your experience and costs. Provider networks determine which doctors, hospitals, and specialists you can access at standard rates. Before enrolling, verify that your preferred providers participate in the plan's network.
Network accuracy remains a significant concern for consumers. According to recent Senate findings on mental health care barriers, "ghost networks" with outdated provider directories create substantial obstacles for patients seeking care. This underscores the importance of confirming provider participation directly.
| Coverage Factor | What to Verify | Why It Matters |
|---|---|---|
| Provider Network | In-network doctors and hospitals | Determines out-of-pocket costs |
| Prescription Coverage | Formulary and tier placement | Affects medication expenses |
| Service Area | Geographic coverage zones | Limits where you can receive care |
| Specialist Access | Referral requirements | Impacts care coordination |
Cost Structure Analysis
Understanding the financial components of health plans helps you budget effectively and avoid surprises. Premium costs represent just one element of your total healthcare expenses.
Key cost components include:
- Monthly premiums paid regardless of healthcare usage
- Annual deductibles you must meet before coverage begins
- Copayments for specific services like office visits
- Coinsurance percentages you pay after meeting deductibles
- Out-of-pocket maximums capping your annual expenses
For Medicare beneficiaries considering prescription coverage, exploring best Medicare Part D plans helps ensure medication needs align with formulary options and cost structures.
Medicare-Specific Health Plans
Medicare health plans deserve special attention given their unique enrollment periods, coverage rules, and eligibility requirements. Original Medicare provides a foundation, but many beneficiaries enhance coverage through supplemental options.
Medicare Advantage plans bundle hospital, medical, and often prescription coverage into single plans offered by private insurers. These plans may include additional benefits like dental, vision, and hearing coverage not available through Original Medicare. Research shows that Americans seek trustworthy health information sources when evaluating coverage options, emphasizing the value of working with knowledgeable local agents.
Medicare Supplement Insurance
Medigap policies fill coverage gaps in Original Medicare by paying some or all of the costs that Medicare doesn't cover. These standardized plans, labeled with letters (Plan A through Plan N), offer different benefit combinations.
Popular Medigap plans include:
- Plan G covering most out-of-pocket costs except the Part B deductible
- Plan N offering lower premiums with small copayments for certain services
- High-deductible Plan G providing catastrophic coverage at reduced premium costs
Understanding Medicare C and D options helps residents in High Point and surrounding communities navigate the relationship between Advantage plans and prescription coverage.
Selecting Health Plans Based on Individual Needs
Choosing appropriate health plans requires honest assessment of your medical needs, financial situation, and personal preferences. Generic recommendations rarely serve individuals well because healthcare needs vary dramatically across populations.
Families with young children typically benefit from plans offering comprehensive pediatric care, immunizations, and preventive services without high deductibles. Individuals managing chronic conditions need plans with strong specialist networks and reasonable medication costs for ongoing prescriptions.
For those approaching retirement age in Greensboro, Kernersville, and the broader Triad Area, transitioning from employer coverage to Medicare represents a significant milestone requiring careful planning and timing.
Special Enrollment Considerations
Health plans operate within defined enrollment periods that limit when you can join or change coverage. Missing these windows can result in gaps in coverage or late enrollment penalties.
| Enrollment Period | Who Qualifies | When It Occurs |
|---|---|---|
| Annual Enrollment | All Medicare beneficiaries | October 15 – December 7 annually |
| Initial Enrollment | New Medicare eligibles | 3 months before through 3 months after turning 65 |
| Special Enrollment | Qualifying life events | Within 60 days of triggering event |
| Open Enrollment | Individual market participants | November 1 – January 15 annually |
Planning ahead ensures you maximize coverage options and avoid unnecessary costs. Many residents discover that personalized support through local resources like Moser Insurance Group Inc simplifies this complex process.
Finding Reliable Information About Health Plans
The abundance of health plan information available online creates both opportunities and challenges. Knowing which sources provide accurate, unbiased guidance protects you from misleading claims and helps you make sound decisions.
Research indicates that Americans value certain characteristics in their health information sources, including transparency about funding, clear explanations of complex topics, and easy-to-understand presentation of data.
Trusted sources for health plan information include:
- Official government websites like Medicare.gov and Healthcare.gov
- Independent rating organizations such as the National Committee for Quality Assurance
- State insurance departments providing consumer protections
- Licensed insurance professionals offering personalized guidance
- Academic medical centers and libraries maintaining reputable health information guides
The Agency for Healthcare Research and Quality provides databases used to evaluate health plan performance, offering consumers objective metrics for comparison.
Evaluating Plan Performance and Quality
Quality ratings help distinguish between health plans beyond simple cost comparisons. Medicare uses a five-star rating system to assess Advantage and Part D plans based on dozens of performance measures.
Quality measures typically evaluate:
- Customer service responsiveness and satisfaction scores
- Health outcomes for members with chronic conditions
- Preventive care delivery rates
- Medication adherence and management programs
- Appeals and grievance resolution efficiency
Working With Insurance Professionals
Navigating health plans independently proves challenging for many individuals given the complexity of coverage rules, plan options, and enrollment requirements. Licensed insurance agents provide valuable assistance without adding to your costs, as they receive compensation from insurance carriers.
Local expertise matters particularly when dealing with regional provider networks and area-specific plan availability. For residents throughout the Triad Area, working with professionals familiar with Greensboro, Winston Salem, High Point, and Kernersville healthcare systems ensures relevant recommendations.
Questions to Ask Your Insurance Agent
Productive conversations with insurance professionals begin with prepared questions addressing your specific concerns and circumstances. Understanding what information matters most helps you evaluate options efficiently.
Essential questions include:
- Which health plans include my current doctors and specialists in their networks?
- How do prescription drug costs compare across different plan formularies?
- What additional benefits beyond basic coverage does each plan offer?
- How do enrollment dates affect when coverage begins and premium obligations start?
- What happens if I need care outside the plan's service area?
Licensed agents help you understand nuances that aren't immediately apparent from plan materials. For example, Humana Medicare plans may offer different benefits and costs than other carriers even when covering similar services.
Understanding Plan Documents and Coverage Details
Health plans generate extensive documentation that many beneficiaries find overwhelming. Learning to navigate key documents helps you understand your coverage rights and responsibilities.
The Summary of Benefits and Coverage (SBC) provides standardized overviews of plan features in plain language, making comparisons easier. Evidence of Coverage (EOC) documents offer comprehensive details about what plans cover and exclude.
Reading Your Explanation of Benefits
Explanation of Benefits (EOB) statements arrive after receiving healthcare services, showing how claims were processed. These documents don't represent bills but rather account for how costs were allocated between you and your plan.
| EOB Component | What It Shows | Action Required |
|---|---|---|
| Service Date | When care was received | Verify accuracy |
| Provider Name | Who delivered services | Confirm correct provider |
| Amount Charged | Provider's standard fee | Review for errors |
| Plan Allowed | Contracted rate for service | Compare to charges |
| Plan Paid | Insurer's payment portion | Track toward deductible |
| You Owe | Your financial responsibility | Pay provider if billed |
Understanding these documents empowers you to identify billing errors, track deductible progress, and verify that providers charged appropriate amounts under network agreements.
Maximizing Value From Your Health Plan
Once enrolled in health plans, taking full advantage of included benefits ensures you receive maximum value for your premiums. Many plans offer preventive services, wellness programs, and additional benefits that members underutilize.
Medicare Advantage plans frequently include:
- Annual dental cleanings and exams
- Routine vision care with eyewear allowances
- Hearing aid benefits and examinations
- Fitness program memberships
- Over-the-counter medication allowances
- Telehealth services for convenient care access
Preventive care services covered at no cost help identify health issues early when they're most treatable. Annual wellness visits, cancer screenings, and cardiovascular disease prevention all fall under covered preventive services.
Utilizing Care Coordination Services
Many health plans employ care coordinators who help members navigate complex healthcare needs, especially when managing multiple chronic conditions. These professionals can assist with appointment scheduling, medication management, and connecting you with community resources.
For Winston Salem and High Point residents managing serious health conditions, care coordination simplifies the often-fragmented healthcare system and improves outcomes through better communication between providers.
Getting Help With Health Plan Questions
When questions arise about your coverage, multiple resources stand ready to assist. Starting with your plan's customer service department often resolves routine inquiries about benefits, claims, or provider networks.
For Medicare-specific questions, calling 1-800-MEDICARE (1-800-633-4227) connects you with representatives who can explain benefits, help compare plans, and provide enrollment assistance. State Health Insurance Assistance Programs (SHIPs) offer free local counseling on Medicare and related coverage issues.
Local insurance professionals provide personalized support tailored to your situation. Moser Insurance Group Inc serves residents throughout the Triad Area with expertise in Medicare, life insurance, and health coverage options. You can reach them at 336-862-1763, via email at moserinsurancegroup@gmail.com, or through their website at moserinsurancegroup.com.
According to Healthline’s guidance on reliable health information, working with licensed professionals helps verify that the information you receive is accurate and applicable to your specific circumstances.
Planning for Future Healthcare Needs
Health plans should evolve with your changing needs over time. What works well during healthy years may prove inadequate when chronic conditions develop or care needs intensify.
Regular plan reviews during annual enrollment periods ensure your coverage remains aligned with current circumstances. Major life changes triggering special enrollment opportunities include marriage, divorce, relocating outside your plan's service area, or losing other coverage.
Anticipating future needs helps you select health plans positioned to serve you well over multiple years. Consider factors like:
- Likelihood of needing specialized care based on family health history
- Prescription medication needs as conditions develop with age
- Preference for specific hospitals or medical systems
- Financial capacity to handle higher deductibles versus premium costs
- Travel patterns affecting where you might need coverage
Selecting appropriate health plans requires understanding coverage options, evaluating costs and benefits, and matching plans to your unique healthcare needs and budget. The complexity of modern insurance makes personalized guidance valuable for most individuals and families. Moser Insurance Group Inc helps residents throughout Greensboro, Kernersville, High Point, Winston Salem, and the Triad Area understand Medicare, life insurance, and health insurance options with clear explanations and individualized support. Contact them at 336-862-1763 or moserinsurancegroup@gmail.com to receive expert assistance making confident insurance decisions, or visit Moser Insurance Group Inc to learn more about available coverage options.
Recent Comments