

When planning for your family's financial future, few decisions carry more weight than choosing the right life insurance coverage. A 30 year term life policy offers one of the longest coverage periods available in term insurance, making it an attractive option for families with young children, new mortgages, or extended financial obligations. This comprehensive guide walks you through everything you need to know about this coverage option, from how it works to determining if it's the right fit for your specific situation in the Triad Area and beyond.
Understanding 30 Year Term Life Insurance
A 30 year term life policy provides coverage for three full decades at a locked-in premium rate. Unlike permanent insurance options, term life insurance focuses exclusively on providing a death benefit without accumulating cash value. This straightforward approach makes it significantly more affordable than permanent coverage options.
The mechanics are simple. You select a coverage amount based on your family's needs, typically ranging from $250,000 to $2 million or more. You pay a fixed monthly or annual premium throughout the 30-year period. If you pass away during those three decades, your beneficiaries receive the full death benefit tax-free. If you outlive the term, the policy expires without any payout.
Key Features That Set This Coverage Apart
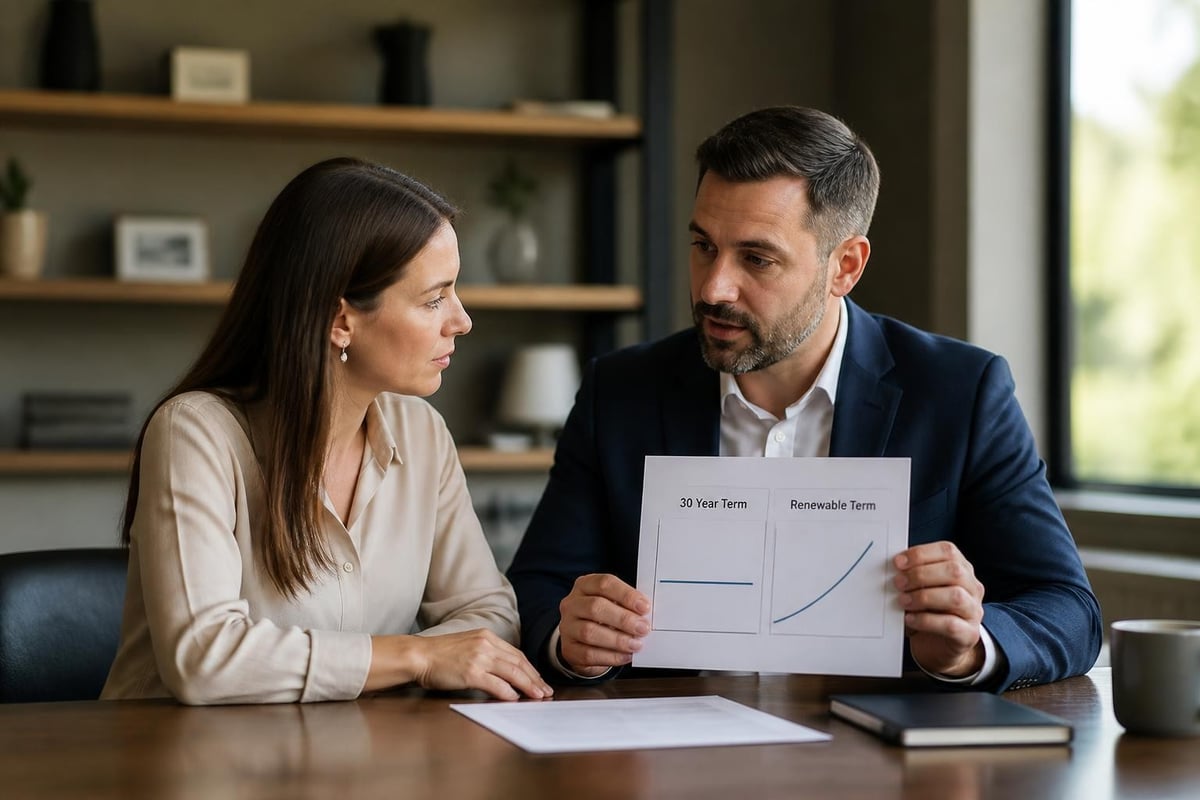
Premium stability stands as one of the most valuable aspects of 30 year term life insurance. Your rate remains constant for the entire period, protecting you from increases due to age or health changes. A policy purchased at age 35 maintains the same premium until age 65.
Consider these fundamental characteristics:
- Fixed death benefit that doesn't decrease over time
- Guaranteed renewability options at term end with most carriers
- Conversion privileges allowing you to switch to permanent coverage
- No cash value component, keeping premiums affordable
- Flexible coverage amounts based on your specific needs
The extended coverage period of a 30 year term life policy makes it particularly well-suited for parents who want protection lasting through their children's dependent years. A 35-year-old parent of a newborn, for example, secures coverage extending until the child reaches age 30 and is likely financially independent.
Who Benefits Most From 30 Year Coverage
Young families represent the primary demographic for 30-year term life insurance policies. Parents in their 30s or early 40s can secure coverage extending through their children's college years and beyond, ensuring educational expenses and daily living costs are covered regardless of what happens.
Homeowners with new mortgages find this coverage duration aligns perfectly with typical loan terms. A 30-year mortgage paired with matching life insurance coverage ensures your family can keep the home even if you're not there to make payments.
Specific Scenarios Where This Term Length Excels
Career professionals in their peak earning years use 30 year term life policies to replace decades of future income. If you're 35 and earning $80,000 annually, a $1.5 million policy provides approximately 20 years of income replacement for your dependents.
Business owners often select this extended term to:
- Cover business loan obligations lasting 15-30 years
- Fund buy-sell agreements with business partners
- Protect against key person loss during critical growth periods
- Ensure succession plans remain funded
Stay-at-home parents deserve equal consideration when evaluating coverage needs. The economic value of childcare, household management, and family support easily justifies substantial coverage, even without traditional employment income.
Residents in Greensboro, High Point, Winston Salem, and Kernersville increasingly recognize that 30 year term life protection provides peace of mind during their most financially vulnerable decades. Term life insurance offers the protection families need at prices that fit within household budgets.
Cost Factors and Premium Determinants
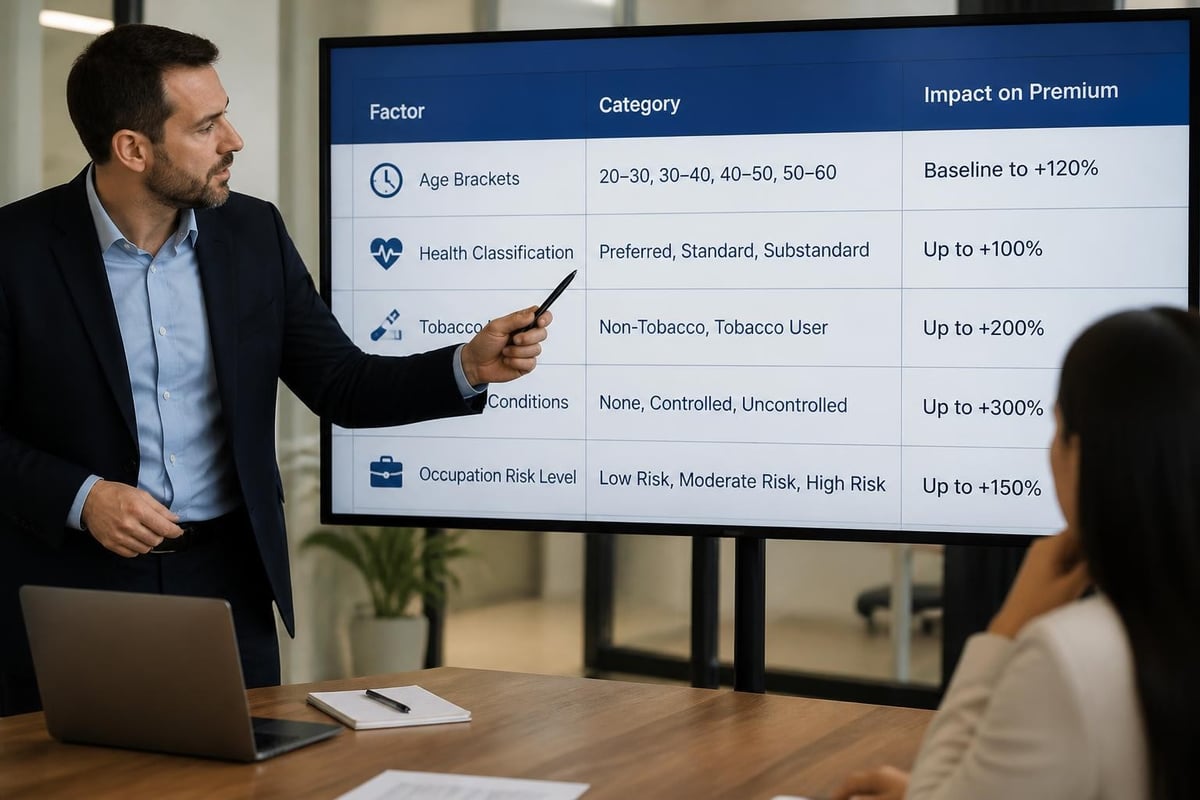
Age at application significantly impacts your premium for 30 year term life coverage. A healthy 30-year-old non-smoker might pay $30-50 monthly for $500,000 in coverage, while a 45-year-old in similar health could pay $80-120 monthly for the same amount.
| Age Range | $500K Coverage (Monthly) | $1M Coverage (Monthly) |
|---|---|---|
| 25-34 | $25-55 | $40-85 |
| 35-44 | $45-95 | $75-150 |
| 45-54 | $95-200 | $165-350 |
| 55-60 | $250-450 | $450-850 |
Health status creates the most dramatic premium variations. Insurers classify applicants into rating categories based on medical history, current health conditions, and lifestyle factors. Understanding these cost factors helps you anticipate what you'll actually pay.
Health and Lifestyle Impact
Tobacco use represents the single largest premium multiplier. Smokers typically pay 2-3 times more than non-smokers for identical coverage. Someone paying $50 monthly as a non-smoker might face $125-150 monthly rates if they use tobacco products.
Medical conditions affecting pricing include:
- High blood pressure or cholesterol levels
- Diabetes or pre-diabetic conditions
- Heart disease or family cardiac history
- Cancer history, even if in remission
- Obesity based on BMI calculations
- Sleep apnea or respiratory conditions
Gender differences also influence rates, with women generally receiving lower premiums than men of the same age and health status due to longer life expectancy statistics.
Your occupation and hobbies matter too. Pilots, construction workers, and those in hazardous professions may pay higher rates. Similarly, engaging in skydiving, scuba diving, or racing can trigger premium increases.
Comparing 30 Year Terms to Other Options
The 30-year term life policy occupies a specific niche within the life insurance landscape. Understanding how it compares to alternatives helps clarify whether this extended coverage period matches your needs.
20-year term policies cost less monthly but expire sooner. If you're 40 years old, a 20-year term ends at age 60, potentially leaving a coverage gap before retirement. A 30 year term life option extends protection to age 70, covering more of your working years.
Term Length Comparison
| Term Length | Best For | Premium Level | Coverage End |
|---|---|---|---|
| 10 Year | Short-term debts | Lowest | Quickest |
| 20 Year | Mid-career protection | Moderate | Age 55-65 typical |
| 30 Year | Long-term obligations | Higher | Age 60-75 typical |
Permanent insurance options like whole life insurance provide lifetime coverage with cash value accumulation, but premiums run 5-10 times higher than comparable term coverage. A 35-year-old might pay $60 monthly for $500,000 in 30 year term life coverage versus $400-600 monthly for a similar whole life policy.
The tradeoff centers on your priorities. Term insurance maximizes death benefit per dollar spent during your working years. Permanent insurance provides lifetime coverage and builds cash value but requires significantly larger premium commitments.
Renewable annual term policies offer maximum flexibility but create escalating costs. Each year your premium increases as you age, making long-term coverage prohibitively expensive. Locking in a 30 year term life rate protects you from these annual increases.
Application Process and Medical Underwriting
Securing a 30 year term life policy typically involves several steps, starting with determining your coverage amount and comparing carrier options. The process has become increasingly streamlined in 2026, with many insurers offering simplified applications for healthy applicants.
Initial application requires basic information including age, health history, lifestyle details, and financial information justifying your coverage amount. You'll also designate beneficiaries who receive the death benefit upon your passing.
Medical underwriting comes next for most applicants. This includes:
- Paramedical examination conducted at your home or office at no cost
- Blood and urine samples analyzing cholesterol, glucose, and other health markers
- Medical records review from your physicians
- Motor vehicle report checking your driving history
- Prescription database check verifying disclosed medications
Some insurers now offer accelerated underwriting for qualified applicants, eliminating the medical exam requirement. Healthy individuals under age 50 seeking moderate coverage amounts often qualify for these expedited programs, receiving approval within days instead of weeks.
Understanding Rate Classifications
Insurers assign you to a health class determining your actual premium. Standard classifications include:
- Preferred Plus (best rates, excellent health)
- Preferred (very good health, minor issues)
- Standard Plus (good health, some concerns)
- Standard (average health, manageable conditions)
- Substandard (significant health issues, rated premiums)
The difference between Preferred Plus and Standard rates can mean 30-50% more in premiums for identical coverage. Working with an experienced agent helps ensure you present your application in the most favorable light possible.
For residents throughout the Triad Area, scheduling your medical exam at a convenient time and location in Greensboro, Kernersville, or surrounding communities makes the process manageable. Most exams take 30 minutes or less.
Strategic Use Cases and Planning Applications
A 30 year term life policy serves multiple financial planning objectives beyond simple income replacement. Understanding these applications helps maximize the value of your coverage investment.
Mortgage protection represents one of the most common uses. According to detailed analysis of 30-year coverage, aligning your policy term with your mortgage ensures your family can maintain homeownership even if your income disappears. A $300,000 policy on a $250,000 mortgage provides coverage for the loan plus closing costs if the home needs to be sold.
Education Funding Strategies
Parents use 30 year term life coverage to guarantee children's educational opportunities remain funded. Calculate four years of college expenses, multiply by the number of children, and include that amount in your coverage calculation.
For example:
- Projected college cost in 2035: $120,000 for four years
- Two children: $240,000 total education funding
- Add this to other coverage needs for total death benefit
Business continuation planning leverages long-term coverage to protect commercial interests. Partners in an LLC might each carry 30 year term life policies with the business as beneficiary, funding buyout agreements if one partner dies.
Estate equalization for families with multiple children but illiquid assets like farms or businesses uses life insurance to provide inheritance equality. One child inherits the business while others receive life insurance proceeds of equivalent value.
Making the Coverage Decision
Determining if a 30 year term life policy fits your situation requires honest assessment of your financial obligations timeline. Map out major expenses and dependencies over the next three decades.
Calculate your coverage need using this simplified approach:
- Annual income × 10-15 years = income replacement
- Outstanding mortgage balance
- Other debts (car loans, personal loans, credit cards)
- College funding for all children
- Final expenses (funeral, estate settlement)
- Emergency fund for transition period
Add these components together for your target death benefit. Resources explaining term life insurance fundamentals can help refine these calculations based on your specific circumstances.
When Shorter Terms Make More Sense
A 20-year term might suffice if you're in your late 40s with teenagers who will soon be independent. Similarly, if you're aggressively paying down a 15-year mortgage, matching your coverage to that timeline could be more cost-effective.
Conversely, consider a 30 year term life option when:
- You have young children under age 10
- You recently purchased a 30-year mortgage
- You're the primary earner with a non-working spouse
- You have special needs dependents requiring lifetime care
- You want coverage extending into early retirement
Age limits vary by insurer, but most companies issue 30 year term life policies to applicants up to age 55-60. After that, shorter terms or permanent insurance become your only options.
Converting and Renewing Your Coverage
Most 30 year term life policies include conversion privileges allowing you to exchange term coverage for permanent insurance without new medical underwriting. This feature provides valuable flexibility as your circumstances change.
Conversion windows typically extend for the first 10-20 years of your term. During this period, you can convert some or all of your coverage to whole life or universal life insurance at rates based on your current age but without health questions or medical exams.
This matters most when health deteriorates. Someone diagnosed with a serious condition during year 15 of their term can still convert to permanent coverage, ensuring lifetime protection despite being uninsurable for new policies.
Renewal Considerations
When your 30-year term expires, most policies offer renewal options, though at significantly higher rates reflecting your advanced age. A policy ending at age 65 might renew annually with premiums 5-10 times higher than your original rate.
Better strategies for coverage continuation include:
- Converting before term end if permanent coverage is needed
- Purchasing new term insurance if you're still healthy and insurable
- Reducing coverage amounts to match decreased obligations
- Transitioning to final expense insurance for modest burial coverage
For many families in High Point, Winston Salem, and throughout North Carolina, careful planning eliminates the need for coverage beyond the original 30-year period. By that time, mortgages are paid, children are independent, and retirement savings provide financial security.
Common Mistakes to Avoid
Purchasing insufficient coverage ranks as the most frequent error with 30 year term life insurance. People underestimate their actual financial obligations or rely on outdated rules of thumb that don't reflect modern costs.
Waiting too long to purchase coverage costs you money. Every year you age, premiums increase. A healthy 32-year-old pays substantially less than the same person at 37, even with identical health status. Understanding cost factors and age impacts demonstrates the financial advantage of early purchase.
Coverage Gaps and Lapses
Allowing a policy to lapse by missing premium payments destroys your coverage and forces you to reapply at current age and health status. Modern payment options including automatic bank withdrawals virtually eliminate this risk.
Forgetting to update beneficiaries after major life changes creates legal complications and potential tax issues. Review and update beneficiary designations after:
- Marriage or divorce
- Birth or adoption of children
- Death of a named beneficiary
- Significant changes in family relationships
Misunderstanding policy features leads to surprises down the road. Know whether your policy includes:
- Waiver of premium riders for disability
- Accelerated death benefit provisions for terminal illness
- Guaranteed insurability options for future purchases
- Conversion privileges and their time limits
Working with knowledgeable professionals who explain these features clearly helps you maximize your coverage value. At Moser Insurance Group Inc, located in Kernersville and serving the entire Triad Area, we ensure clients fully understand their coverage before making decisions. You can reach us at 336-862-1763 or moserinsurancegroup@gmail.com for personalized guidance.
Riders and Additional Benefits
Standard 30 year term life policies can be enhanced with optional riders addressing specific concerns. While these additions increase premiums, they provide valuable protections for particular situations.
Accelerated death benefit riders allow you to access a portion of your death benefit if diagnosed with a terminal illness. Most policies now include this at no extra cost, providing 25-50% of the death benefit if you're expected to live less than 12-24 months.
| Rider Type | Purpose | Typical Cost |
|---|---|---|
| Waiver of Premium | Waives premiums if disabled | 5-10% of base premium |
| Accidental Death | Doubles benefit for accidental death | 10-15% addition |
| Child Term Rider | Covers all children | $50-100 annually |
| Guaranteed Insurability | Purchase more coverage later | 15-20% addition |
Disability waiver of premium becomes critical if you work in physically demanding fields. If you become totally disabled and unable to work, the insurance company pays your premiums, keeping your coverage in force without payments from you.
Children's term riders cover all your children under one addition to your policy, typically providing $10,000-25,000 per child. This proves more economical than purchasing separate policies for each child while they're young.
Tax Considerations and Beneficiary Planning
Life insurance death benefits pass to beneficiaries income tax-free under current federal law, making a 30 year term life policy an efficient wealth transfer vehicle. A $1 million death benefit delivers the full amount to your family without tax withholding.
Estate tax implications arise only for very large estates. In 2026, federal estate tax exemptions exceed $13 million per individual, meaning most families avoid estate tax entirely. However, if your total estate including life insurance proceeds exceeds exemption levels, specialized planning becomes necessary.
Proper beneficiary designation prevents unnecessary complications. Consider these best practices:
- Name both primary and contingent beneficiaries
- Use specific percentages if splitting among multiple people
- Avoid naming your estate as beneficiary when possible
- Consider trusts for minor children
- Review designations every 3-5 years
Per stirpes designations ensure that if a beneficiary predeceases you, their share passes to their children rather than other named beneficiaries. This proves particularly important for parents with multiple adult children.
Comparing Carriers and Finding the Best Rates
Not all 30 year term life policies offer identical value. Carrier financial strength, customer service quality, and actual pricing vary significantly across the insurance marketplace.
Financial strength ratings from agencies like A.M. Best, Moody's, and Standard & Poor's indicate an insurer's ability to pay claims decades into the future. Look for carriers rated A or better, ensuring they'll still be solvent when your beneficiaries need the death benefit.
Premium competitiveness shifts based on your specific profile. One carrier might offer the best rates for healthy 35-year-olds while another excels for applicants with controlled diabetes. Working with an independent agent accessing multiple carriers ensures you see the most competitive options for your situation.
Features Beyond Price
Consider these factors when comparing carriers:
- Conversion options quality and permanent policy choices
- Claims paying history and average settlement timeframes
- Customer service accessibility and support quality
- Online account management tools and mobile apps
- Additional riders available and their costs
Some insurers specialize in certain demographics or health profiles. Comparing 30-year coverage options across multiple carriers reveals price differences of 20-40% for identical coverage amounts and health classifications.
For residents throughout Greensboro and surrounding communities, local expertise matters. Understanding regional health trends, cost-of-living factors, and specific family needs in North Carolina helps match you with the most appropriate carrier and coverage design.
Visit moserinsurancegroup.com to explore your options or contact our team directly for personalized quotes reflecting your unique situation. We compare offerings from multiple highly-rated carriers to find your best match.
Living Benefits and Modern Policy Features
Today's 30 year term life policies include features unimaginable even a decade ago. Living benefits allow policyholders to access their death benefit under specific circumstances before death occurs.
Chronic illness riders permit benefit acceleration if you're unable to perform two or more activities of daily living and require ongoing care. This helps fund home health care, assisted living, or nursing facility costs without exhausting other assets.
Critical illness riders pay a lump sum upon diagnosis of covered conditions like heart attack, stroke, or organ transplant. While not standard on term policies, these additions bridge the gap between health insurance and financial protection during serious illness.
Return of premium options transform a traditional 30 year term life policy into a hybrid product. If you survive the full term, the insurer returns all premiums paid. This feature costs 30-50% more than standard term but appeals to those viewing life insurance as a "waste" if they don't die.
Modern policies also emphasize:
- Wellness programs with discounts for healthy behaviors
- Telemedicine access for quick medical consultations
- Identity theft protection services
- Will preparation assistance
- Grief counseling for beneficiaries
These value-adds differentiate carriers and enhance the overall ownership experience beyond basic death benefit protection.
Regional Considerations for North Carolina Residents
While life insurance principles remain consistent nationwide, specific factors affect residents in Greensboro, High Point, Winston Salem, Kernersville, and throughout the Triad Area.
Cost of living variations influence coverage amounts needed. Housing costs, education expenses, and general living costs in the Piedmont region require different death benefit calculations than expensive coastal markets or rural areas.
North Carolina's economic landscape features strong healthcare, education, manufacturing, and financial services sectors. Career professionals in these industries should ensure their coverage reflects income potential and family obligations specific to their field.
Healthcare Access and Planning
The Triad Area's robust healthcare infrastructure, including major medical centers and specialty facilities, means residents have excellent access to care. This affects insurance planning by:
- Enabling comprehensive medical underwriting with easy records access
- Supporting chronic condition management that improves insurability
- Providing resources for second opinions on serious diagnoses
State-specific regulations governing life insurance provide strong consumer protections. North Carolina requires free-look periods allowing you to cancel new policies within 10-30 days for full premium refunds if you change your mind.
Working with local professionals who understand regional factors ensures your coverage design reflects actual needs rather than generic national calculations. Moser Insurance Group Inc brings deep expertise in North Carolina insurance markets and family financial planning specific to Triad Area residents.
A 30 year term life policy provides affordable, long-term financial protection during your family's most vulnerable decades, ensuring your loved ones maintain their lifestyle and meet important obligations even if you're not there to provide for them. Whether you're a young parent in Greensboro, a professional in Winston Salem, or a growing family in Kernersville, finding the right coverage requires understanding your unique needs and comparing options from quality carriers. Moser Insurance Group Inc helps individuals and families throughout the Triad Area understand life insurance options with clear guidance and personalized support, ensuring you make confident decisions without pressure. Contact us today at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your 30 year term life insurance options and protect your family's financial future.
Recent Comments