

MetLife stands as one of the largest and most recognized life insurance providers in the United States, offering comprehensive term life insurance solutions that protect families and individuals during critical income-earning years. For residents in the Triad Area-including Greensboro, Kernersville, High Point, and Winston Salem-understanding how metlife term life insurance works can make the difference between adequate financial protection and leaving loved ones vulnerable. This guide explores coverage options, policy features, costs, and what makes MetLife's term offerings unique in the current insurance marketplace.
Understanding MetLife's Term Life Insurance Structure
MetLife provides term life insurance primarily through employer-sponsored group plans, though individual policies are available through specific channels. The company's approach focuses on accessibility and straightforward coverage that families can understand without complicated policy language.
Primary Coverage Categories
MetLife organizes its term life insurance products into three distinct categories that serve different needs and life stages:
Basic Group Coverage represents the foundation of MetLife's term offerings. This coverage typically comes through employer benefits packages at no cost or minimal cost to employees. Coverage amounts usually range from one to two times annual salary, providing baseline protection for families.
Supplemental Coverage allows employees to purchase additional term life insurance beyond their basic group policy. This option addresses the gap between employer-provided coverage and actual family needs. Most individuals require coverage equal to 8-10 times their annual income to adequately protect dependents.
Dependent Coverage extends protection to spouses and children through the employee's group plan. This category offers smaller coverage amounts specifically designed for dependent family members who may not have individual income protection needs.
Policy Term Lengths and Renewal Options
Unlike many individual term policies that offer fixed periods, group metlife term life insurance typically renews annually through the employer. This structure provides flexibility but comes with important considerations:
| Feature | MetLife Group Term | Traditional Individual Term |
|---|---|---|
| Term Length | Annual renewal (while employed) | Fixed 10, 20, or 30 years |
| Premium Stability | Increases with age | Locked for entire term |
| Portability | Limited conversion options | Fully portable |
| Medical Underwriting | Often simplified or waived | Required at application |
| Coverage Amounts | Based on salary multiples | Chosen amount ($100k-$5M+) |
The annual renewal structure means premiums adjust as you age, which can become expensive after age 50. According to detailed analyses of MetLife’s offerings, understanding these renewal implications is critical for long-term financial planning.
Coverage Amounts and Eligibility Requirements
MetLife structures coverage amounts differently based on whether you're applying through an employer group plan or seeking individual coverage. Most group plans offer coverage calculated as a multiple of your annual salary.
Standard Coverage Calculations
Salary Multiple Options typically include:
- 1x annual salary (basic coverage, often employer-paid)
- 2x annual salary
- 3x annual salary
- 4x annual salary
- 5x annual salary (maximum for most plans)
Some plans cap maximum coverage regardless of salary. For example, even if you earn $200,000 annually, your plan might limit coverage to $500,000 or $750,000 total.
Medical Underwriting and Approval Process
Group metlife term life insurance often features simplified underwriting, making it accessible to individuals who might struggle to qualify for individual policies. The approval process varies based on coverage amount:
Guaranteed Issue Amounts: Basic coverage up to 1-2x salary typically requires no medical questions or exams. You're automatically approved when you enroll during your employer's open enrollment period.
Limited Underwriting: Supplemental coverage between 2-4x salary usually requires a health questionnaire but no medical examination. MetLife reviews your answers to determine eligibility.
Full Underwriting: Higher coverage amounts (5x+ salary or amounts exceeding $500,000) may require phone interviews, medical records review, or paramedical examinations including bloodwork.
For families in Greensboro and the surrounding Triad Area seeking life insurance protection, comparing term life insurance options helps ensure you're getting both adequate coverage and competitive pricing for your specific situation.
Premium Costs and Payment Structure
Understanding what you'll pay for metlife term life insurance requires examining how group plans calculate premiums versus individual policy pricing. The cost structure significantly impacts your long-term financial commitment.
Age-Based Premium Calculations
MetLife's group term rates typically increase every five years based on your age bracket:
| Age Range | Average Monthly Cost per $100k Coverage |
|---|---|
| 25-29 | $4-$7 |
| 30-34 | $5-$9 |
| 35-39 | $7-$12 |
| 40-44 | $10-$18 |
| 45-49 | $16-$28 |
| 50-54 | $28-$45 |
| 55-59 | $48-$75 |
| 60-64 | $85-$140 |
These estimates represent non-tobacco users in good health. Tobacco users typically pay 2-3x these rates. As comprehensive reviews indicate, MetLife's group pricing remains competitive for younger employees but can become expensive as you approach retirement age.
Payroll Deduction Convenience
One advantage of employer-sponsored metlife term life insurance is automatic payroll deduction. Your premium comes directly from your paycheck before taxes (if structured as a Section 125 cafeteria plan), reducing your taxable income slightly while ensuring continuous coverage without manual payment management.
Tax Considerations: Employer-paid premiums for coverage up to $50,000 are tax-free. Coverage above $50,000 creates "imputed income" that appears on your W-2 as taxable compensation, though you're not actually receiving that money as cash.
Policy Features and Riders Available
MetLife enhances its basic term life insurance with several valuable features and optional riders that customize protection to individual circumstances.
Accelerated Death Benefit Provisions
Most metlife term life insurance policies include an accelerated death benefit rider at no additional cost. This feature allows you to access a portion of your death benefit while still living if diagnosed with a terminal illness (typically defined as life expectancy of 12 months or less).
How It Works:
- You're diagnosed with a qualifying terminal condition
- You submit medical documentation to MetLife
- Upon approval, you receive 25-50% of your death benefit
- The remaining benefit goes to beneficiaries upon death
- No additional premium is charged for this feature
This provision helps cover medical expenses, experimental treatments, or final arrangements without depleting family savings.
Waiver of Premium for Disability
Some MetLife group plans offer a waiver of premium rider that continues your coverage without premium payments if you become totally disabled and unable to work. Eligibility requirements typically include:
- Disability lasting at least six months
- Inability to perform the duties of your occupation
- Disability occurring before age 60 or 65
- Proof of disability through medical documentation
This rider ensures your family maintains protection even if your income stops due to disability.
Conversion Privileges
The conversion privilege represents one of the most valuable features of metlife term life insurance, particularly for group policies. This right allows you to convert your term coverage to a permanent policy (whole life or universal life) without providing evidence of insurability.
Key Conversion Details:
- Available when you leave your employer or when coverage reduces/terminates
- Must exercise within 31 days of qualifying event
- No medical exam or health questions required
- Premium based on your age at conversion
- Coverage amount cannot exceed original term policy amount
Understanding the differences between term and whole life insurance helps you determine whether conversion makes financial sense for your long-term planning needs.
Coverage Limitations and Exclusions
Every insurance policy contains specific limitations and exclusions that define when benefits won't be paid. MetLife's term life insurance includes standard industry exclusions plus some specific provisions you should understand before purchasing.
Standard Exclusion Periods
Suicide Clause: Like most life insurance policies, metlife term life insurance includes a two-year suicide exclusion. If the insured dies by suicide within the first two policy years, MetLife returns premiums paid but does not pay the death benefit. After two years, suicide is covered like any other cause of death.
Contestability Period: During the first two years of coverage, MetLife can investigate claims and potentially deny benefits if they discover material misrepresentation on the application. This applies primarily to individual policies rather than guaranteed-issue group coverage.
Activity and Circumstance Exclusions
Certain high-risk activities or circumstances may result in coverage exclusions or limitations:
- War or acts of war (military deployment to combat zones)
- Aviation exclusions (for non-commercial pilots or crew members)
- Hazardous occupations or hobbies
- Drug or alcohol-related deaths (during contestability period)
- Criminal activity resulting in death
Group policies through employers typically have fewer exclusions than individual policies, particularly for guaranteed-issue amounts. Detailed information about MetLife’s exclusions helps applicants understand their specific coverage parameters.
The Claims Process and Beneficiary Payouts
When a policyholder dies, beneficiaries must navigate the claims process to receive their death benefit. MetLife has established procedures designed to process legitimate claims efficiently while protecting against fraud.
Filing a Death Claim
The claims process follows these general steps:
- Notification: Beneficiaries contact MetLife by phone (often through the employer's HR department for group policies) or online through the claims portal
- Documentation Submission: Required documents include a certified death certificate, completed claim forms, and policy information
- Claim Review: MetLife reviews the submission, verifying coverage was active and no exclusions apply
- Additional Information: If needed, MetLife requests supplementary documentation such as medical records or police reports
- Benefit Payment: Upon approval, MetLife issues payment within 5-7 business days
Payment Options for Beneficiaries
MetLife offers several methods for receiving death benefits:
| Payment Method | Description | Best For |
|---|---|---|
| Lump Sum Check | Single payment of full benefit amount | Immediate needs, debt payoff |
| Electronic Transfer | Direct deposit to bank account | Faster access (2-3 days) |
| Retained Asset Account | Funds held in interest-bearing account with checkbook | Gradual access while earning interest |
| Structured Payments | Fixed installments over time | Income replacement, minor beneficiaries |
Most beneficiaries choose lump sum payment for maximum flexibility, though the retained asset account provides a brief period to make financial decisions without rushing.
Comparing MetLife to Other Term Life Insurance Providers
While metlife term life insurance offers solid coverage through employer groups, comparing it to other options helps ensure you're making the best choice for your family's protection needs.
Strengths of MetLife's Approach
Financial Stability: MetLife maintains strong financial ratings from major rating agencies (A+ from A.M. Best, AA- from S&P), indicating reliable ability to pay claims decades into the future.
Employer Integration: The seamless connection with employer benefits systems makes enrollment simple, and payroll deduction ensures you never miss a payment.
Simplified Underwriting: Group coverage often requires minimal or no medical underwriting, making it accessible to individuals with health conditions who might struggle to qualify for individual policies.
Considerations and Limitations
Portability Concerns: Group metlife term life insurance typically ends when you leave your employer, unless you exercise conversion rights. This creates vulnerability if you change jobs during a period of poor health when you can't qualify for new coverage.
Age-Based Premium Increases: Unlike traditional term life insurance with locked rates for 20-30 years, group coverage becomes progressively more expensive as you age.
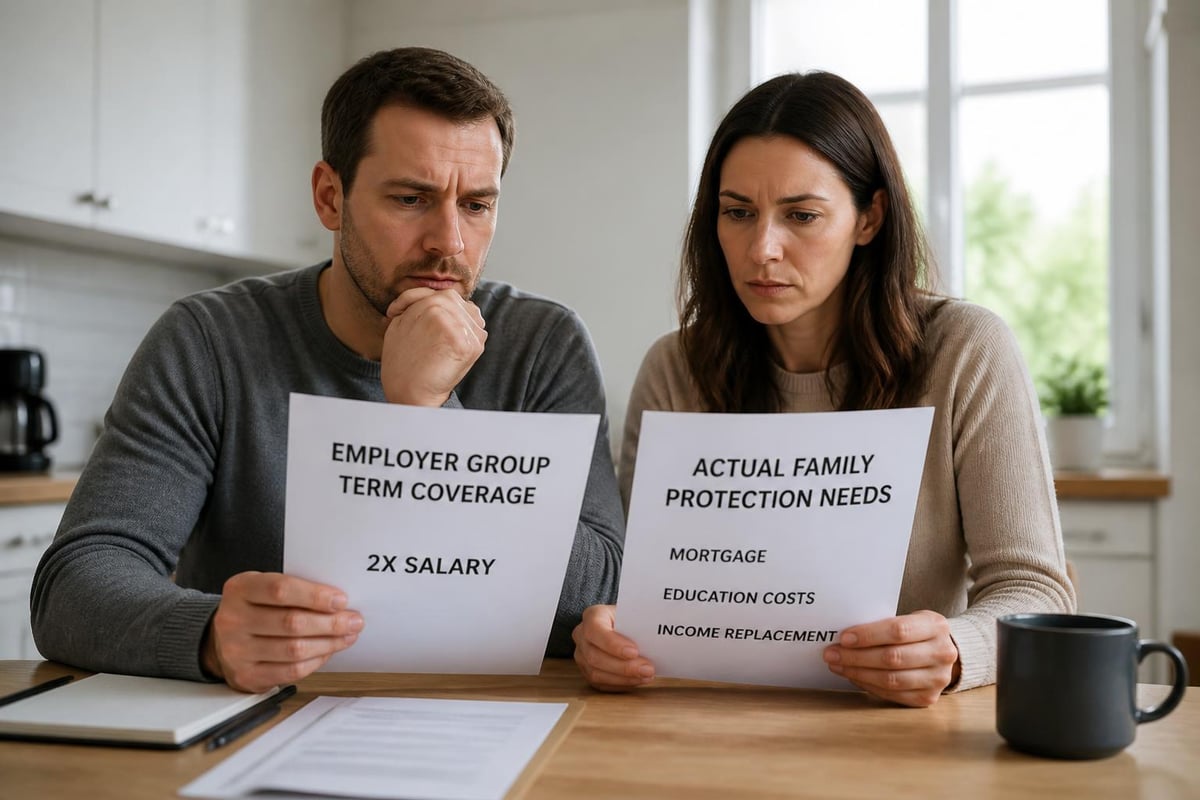
Coverage Caps: Salary-based calculations often provide insufficient coverage for families with multiple children, mortgages, or single-income households. Financial advisors typically recommend coverage equal to 8-10x annual income, which may exceed group plan maximums.
Integration with Comprehensive Financial Planning
For residents of the Triad Area including High Point and Winston Salem, metlife term life insurance represents one component of a comprehensive financial protection strategy that should include multiple insurance types and investment vehicles.
Coordinating With Other Coverage Types
Medicare Planning: As you approach age 65, coordinating your life insurance with Medicare coverage becomes important. Many people reduce life insurance needs after retirement, though understanding Medicare supplement options ensures healthcare costs don't deplete the assets you're trying to protect with life insurance.
Health Insurance Coordination: For those under 65, maintaining adequate health insurance prevents medical debt that could impact your family even with life insurance protection. The relationship between health coverage and life insurance protection creates a comprehensive safety net.
Retirement Asset Protection: Life insurance works alongside retirement accounts, providing liquidity if you die before accumulating significant retirement savings. This coordination ensures your family has immediate funds to cover expenses while retirement accounts transfer to beneficiaries.
Supplementing Group Coverage
Many financial professionals recommend purchasing individual term life insurance to supplement group coverage rather than relying exclusively on employer-provided policies. This strategy offers several advantages:
- Portable Protection: Individual policies stay with you regardless of employment changes
- Level Premiums: Lock in rates for 20-30 years instead of facing age-based increases
- Higher Coverage Amounts: Purchase exactly the coverage your family needs, not what your salary multiple provides
- Diverse Coverage: Split coverage between group and individual policies to maintain some protection even if one policy lapses
According to analyses of term insurance strategies, combining group and individual coverage often provides both cost efficiency and comprehensive protection.
Employer Plan Selection and Open Enrollment Strategies
Maximizing your metlife term life insurance benefits requires strategic thinking during your employer's annual open enrollment period. The decisions you make during this limited window affect your coverage and costs for the entire year.
Evaluating Your Coverage Needs
Before open enrollment begins, calculate your actual life insurance needs using this framework:
Income Replacement: Multiply your annual income by 8-10 to replace your earnings for your family
Debt Obligations: Add mortgage balance, car loans, credit cards, and other debts that would burden survivors
Education Funding: Include estimated college costs for each child ($100,000-$200,000 per child for public universities)
Final Expenses: Add $15,000-$25,000 for funeral, burial, and estate settlement costs
Existing Coverage: Subtract any individual policies or savings already in place
This calculation reveals your coverage gap-the amount of additional protection you need beyond existing resources.
Making Cost-Effective Enrollment Decisions
Maximize Employer-Paid Coverage: Always elect the maximum amount of coverage your employer pays for on your behalf. This free coverage provides baseline protection at no cost.
Consider Supplemental Limits: Evaluate the cost of supplemental coverage versus individual term policies. For younger employees (under 40), group supplemental coverage is often competitively priced. After age 45, individual policies frequently cost less for equivalent coverage.
Enroll Family Members: If your group plan offers dependent coverage at reasonable rates, this provides simple protection for spouses and children without separate underwriting.
Review Annually: Life changes-new children, home purchases, salary increases-require coverage adjustments. Open enrollment provides the opportunity to increase coverage without new medical underwriting.
Finding the Right Coverage for Your Situation
Selecting appropriate life insurance protection requires balancing coverage adequacy, cost efficiency, and long-term planning considerations specific to your family's situation in Greensboro, Kernersville, or the broader Triad Area.
When MetLife Term Life Insurance Makes Sense
Group metlife term life insurance serves as an excellent foundation when:
- You're in your 20s or 30s and coverage costs remain low
- You have existing health conditions that make individual coverage difficult to obtain
- You want immediate coverage without medical exams or waiting periods
- Your employer subsidizes a portion of the premium cost
- You're using it as supplemental coverage alongside individual policies
When Individual Coverage Provides Better Value
Consider purchasing individual term life insurance instead of or in addition to group coverage when:
- You're over 45 and group rates increase significantly
- You plan to stay with your current employer long-term and want locked premium rates
- You need coverage exceeding your employer's maximum (often $500,000-$750,000)
- You want portable protection that continues regardless of employment changes
- You're in excellent health and qualify for preferred rate classes
For personalized guidance on coordinating MetLife group coverage with individual policies, reaching out to local insurance professionals who understand the Triad Area market provides valuable perspective. You can contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com for educational consultations about your life insurance options.
Policy Maintenance and Long-Term Management
After enrolling in metlife term life insurance, proper policy maintenance ensures your coverage remains effective and your beneficiaries receive benefits without complications when needed.
Keeping Beneficiary Designations Current
One of the most overlooked aspects of life insurance management involves updating beneficiary designations as life circumstances change. Common situations requiring beneficiary updates include:
- Marriage or remarriage
- Birth or adoption of children
- Divorce or legal separation
- Death of a named beneficiary
- Significant family relationship changes
Most beneficiary disputes arise from outdated designations that don't reflect the policyholder's current wishes. Review your beneficiaries annually during open enrollment and update them through your employer's benefits portal or directly with MetLife.
Understanding Coverage Changes
Group term life insurance coverage changes in several situations:
Salary Increases: If your coverage amount is calculated as a multiple of salary, promotions or raises automatically increase your coverage (and premiums) for salary-based calculations.
Age Milestones: Premium rates typically increase at ages 30, 35, 40, 45, 50, 55, and 60. Budget for these increases to avoid canceling coverage when costs rise.
Employment Status Changes: Part-time status, leaves of absence, or transitions to contractor status may affect coverage eligibility. Understand your employer's specific rules.
Retirement: Most group policies terminate or reduce significantly upon retirement. Plan for this transition by securing individual coverage before leaving employment.
Preparing for Employment Transitions
When changing jobs or retiring, you have limited time to exercise conversion rights or secure replacement coverage:
- Request Conversion Forms: Contact MetLife or your HR department within 31 days of employment termination
- Compare Conversion Costs: Evaluate whether converting to permanent coverage or purchasing new individual term coverage provides better value
- Maintain Continuous Coverage: Ensure new coverage is approved before terminating group coverage to avoid gaps
- Consider Portability Options: Some employers offer portable group term that continues at group rates after employment ends
For those approaching retirement age in Winston Salem and surrounding areas, coordinating life insurance transitions with Medicare enrollment planning creates a comprehensive approach to your changing insurance needs.
Making Informed Decisions About Your Protection
MetLife term life insurance provides accessible, straightforward coverage for millions of employees nationwide, offering particular value through employer-sponsored group plans with simplified underwriting and payroll convenience. Understanding the structure, costs, benefits, and limitations of MetLife's offerings empowers you to determine whether group coverage alone provides adequate protection or whether supplementing with individual policies better serves your family's long-term security.
The coverage calculations, premium structures, and policy features outlined in this guide provide the foundation for evaluating your specific situation. Whether you're enrolling during your first open enrollment period or reassessing coverage after decades with the same employer, approaching life insurance decisions with clear information about your actual needs versus available options leads to confident choices that protect the people who depend on you.
For residents throughout the Triad Area-from Greensboro to Kernersville, High Point to Winston Salem-the intersection of employer benefits, individual coverage options, and long-term financial planning requires personalized evaluation. By understanding how metlife term life insurance functions within your broader financial picture, you can build a protection strategy that provides security today while adapting to your changing needs over time. Research from academic analyses of term insurance strategies demonstrates that optimizing coverage selection requires balancing immediate affordability with long-term adequacy.
The key to maximizing your metlife term life insurance value lies in viewing it as one component of comprehensive financial protection rather than your only safety net. Group coverage provides an accessible starting point, but most families benefit from supplementing employer-provided policies with individual coverage that offers portability, locked premiums, and coverage amounts tailored to actual financial obligations rather than salary multiples.
Understanding your life insurance options-whether through employer-sponsored MetLife plans or individual policies-provides the foundation for protecting your family's financial future. At Moser Insurance Group Inc, we help individuals and families throughout the Triad Area navigate insurance decisions with clear, educational guidance and no-pressure support. Whether you're evaluating your employer's term life offerings or exploring how life insurance coordinates with Medicare and health coverage, we're here to answer your questions. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to schedule a personalized consultation and gain confidence in your insurance decisions.
Recent Comments