
Selecting the right medigap insurance company represents one of the most important decisions Medicare beneficiaries make during their retirement planning. Medicare Supplement Insurance, commonly known as Medigap, helps cover the gaps in Original Medicare coverage, including copayments, coinsurance, and deductibles. With dozens of insurance carriers offering these standardized policies across North Carolina, including the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, understanding how to evaluate and compare providers becomes essential for finding the best coverage at competitive rates.
Understanding What a Medigap Insurance Company Offers
A medigap insurance company sells Medicare Supplement Insurance policies designed to work alongside Original Medicare Parts A and B. These policies help pay for out-of-pocket costs that Medicare doesn't cover, providing financial protection and predictability for healthcare expenses.
The coverage itself is standardized by federal law, meaning Plan G from one carrier offers the same benefits as Plan G from another. However, premiums, customer service quality, claims processing efficiency, and financial stability vary significantly between companies. This standardization simplifies comparison shopping while placing greater importance on the insurer's reputation and pricing strategy.
Key Services Provided by Medigap Companies
When you work with a medigap insurance company, you receive several essential services beyond the policy itself:
- Policy enrollment and application processing with guidance through eligibility requirements
- Premium billing and payment management through various convenient methods
- Claims coordination with Medicare to ensure seamless coverage
- Customer service support for policy questions and benefit explanations
- Annual rate notices with transparent communication about premium changes
Understanding how to compare Medigap policies ensures you evaluate both the plan type and the company offering it, creating a complete picture of your coverage experience.
Evaluating Medigap Insurance Company Financial Strength
Financial stability represents a critical factor when choosing a medigap insurance company. You need assurance that your insurer will remain solvent and able to pay claims for years or decades into the future.
Independent rating agencies like A.M. Best, Moody's, Standard & Poor's, and Fitch assess insurance companies' financial health. These ratings provide objective measures of an insurer's ability to meet ongoing policy obligations.
| Rating Agency | Highest Rating | Meaning | Minimum Recommended |
|---|---|---|---|
| A.M. Best | A++ | Superior | A- or higher |
| Moody's | Aaa | Exceptional | A3 or higher |
| Standard & Poor's | AAA | Extremely Strong | A- or higher |
| Fitch | AAA | Exceptionally Strong | A- or higher |
Look for companies with ratings of A- or better from at least two rating agencies. This indicates strong financial fundamentals and reduced risk of insolvency. While higher-rated companies sometimes charge slightly more, the security they provide justifies the difference for most beneficiaries.
Premium Pricing Methodologies
Every medigap insurance company uses one of three pricing methods that significantly impact your long-term costs:
Community-rated (no-age-rated) policies charge the same premium regardless of age. A 65-year-old pays the same as an 85-year-old, though prices still increase over time due to inflation and healthcare cost trends.
Issue-age-rated premiums are based on your age when you first purchase the policy. Your rate won't increase due to aging, only for general rate increases affecting all policyholders.
Attained-age-rated policies start with lower premiums but increase as you get older. These often appear most affordable initially but can become expensive over time.
Understanding these methodologies helps you project future costs and choose a sustainable option for your retirement budget.
Top Plan Options from Medigap Insurance Companies
Medigap insurance companies in 2026 offer ten standardized plan types, labeled A, B, C, D, F, G, K, L, M, and N. However, Plans C and F are no longer available to those who became Medicare-eligible after January 1, 2020.
Most Popular Medigap Plans
Plan G has emerged as the most popular choice among new Medicare beneficiaries. It covers everything except the Medicare Part B deductible ($257 in 2026), providing comprehensive coverage with predictable out-of-pocket costs.
Plan N offers a more budget-friendly alternative with slightly higher cost-sharing. You pay copayments of up to $20 for doctor visits and $50 for emergency room visits that don't result in admission, plus the Part B deductible.
High-deductible Plan G provides another cost-effective option. You pay a deductible of $2,800 (2026 amount) before coverage begins, but monthly premiums are significantly lower than standard Plan G.
| Plan Type | Monthly Premium Range | Best For | Cost Predictability |
|---|---|---|---|
| Plan G | $120-$200 | Comprehensive coverage seekers | Excellent |
| Plan N | $90-$150 | Budget-conscious with moderate healthcare use | Good |
| High-Deductible G | $30-$60 | Healthy individuals comfortable with risk | Moderate |
The differences in Medicare plans extend beyond Medigap to include Medicare Advantage options, which some beneficiaries prefer over traditional Medicare with supplements.
Medigap Insurance Company Customer Service Standards
Customer service quality separates exceptional carriers from mediocre ones. Since Medigap benefits are standardized, your experience with the company matters tremendously.
Response time for phone inquiries should average under five minutes during business hours. Top-tier companies provide 24/7 customer support lines, though not all inquiries require round-the-clock access.
Claims processing efficiency directly impacts your experience. Leading medigap insurance company providers process claims electronically within 14-30 days, with automated coordination between Medicare and the supplement carrier.
Questions to Ask During Research
Before committing to a medigap insurance company, gather specific information:
- What is your average claims processing time?
- Do you offer online account management and mobile apps?
- How often do premiums typically increase, and by what percentage?
- What is your complaint ratio with state insurance departments?
- Do you have local agents in the Triad Area for in-person support?
Researching illegal practices related to Medigap insurance helps you recognize red flags and avoid companies engaging in prohibited sales tactics.
Geographic Availability and State Regulations
Not every medigap insurance company operates in all states. Availability varies based on state regulations, company licensing, and market decisions.
In North Carolina, beneficiaries enjoy competitive markets in metropolitan areas like Greensboro, Winston Salem, High Point, and Kernersville, with numerous carriers competing for business. Rural areas may have fewer options, though guaranteed issue rights ensure access to coverage.
State insurance departments regulate medigap insurance company practices, approve rate increases, and handle consumer complaints. North Carolina requires insurers to justify rate increase requests with actuarial data, providing some protection against arbitrary premium hikes.
Open Enrollment and Guaranteed Issue Rights
Your Medigap open enrollment period begins when you're 65 or older and enrolled in Medicare Part B. During this six-month window, insurance companies cannot deny coverage or charge higher premiums based on health conditions.
Guaranteed issue rights apply in specific situations outside the open enrollment period:
- Your Medicare Advantage plan is leaving Medicare or stops providing coverage in your area
- You move outside your plan's service area
- Your employer or union discontinues coverage
- The company providing your coverage goes bankrupt
Understanding these rights protects you when changing coverage becomes necessary due to circumstances beyond your control.
Comparing Premium Costs Across Companies
Premium variation between medigap insurance company providers can be substantial, even for identical coverage. Shopping around saves hundreds or thousands of dollars annually.
For a 65-year-old female in Greensboro, North Carolina, Plan G monthly premiums in 2026 range from approximately $125 to $195, representing a potential annual difference of $840. Over ten years, choosing the lower-cost option saves $8,400 before accounting for rate increases.
Factors Influencing Premium Differences
Several elements contribute to premium variation among carriers:
- Administrative efficiency and operating cost management
- Claims experience with their existing policyholder base
- Marketing expenses and distribution channel costs
- Underwriting philosophy during the application process
- Profit margin targets set by company leadership
Household discounts of 5-12% apply when spouses both purchase policies from the same company. Some carriers also offer electronic funds transfer discounts or paid-in-full annual payment discounts.
The National Association of Insurance Commissioners provides comprehensive guidance on evaluating these cost factors when selecting a Medigap policy.
Working with Independent Agents vs. Direct Purchase
You can purchase Medigap coverage directly from a medigap insurance company or work with an independent insurance agent. Each approach offers distinct advantages.
Direct purchase provides a straightforward path when you've already researched your options thoroughly. You communicate directly with one insurer, potentially streamlining the application process. However, you only see one company's rates and may miss better options.
Independent agents represent multiple carriers, providing comparison shopping in a single conversation. Licensed agents understand state-specific regulations, company reputations, and can explain nuanced differences between similar plans.
At Moser Insurance Group Inc, we work with multiple medigap insurance company providers throughout the Triad Area to ensure clients access competitive rates and reliable coverage. You can reach our team at 336-862-1763 or moserinsurancegroup@gmail.com for personalized guidance.
Agent Compensation and Conflicts of Interest
Independent agents earn commissions from insurance companies, but ethical agents prioritize client needs over commission differences. Commission rates are generally similar across major carriers for the same plan type, reducing incentive to steer clients toward specific companies.
Ask your agent directly about commission structures and whether certain carriers pay higher rates. Transparency builds trust and helps you evaluate recommendations objectively.
Quality agents also provide ongoing service, helping with claims issues, rate increase questions, and coverage changes as your needs evolve. This relationship value extends beyond the initial sale.
Technology and Digital Tools Offered
Modern medigap insurance company providers offer digital platforms that enhance the customer experience and simplify policy management.
Online portals should provide:
- Premium payment processing with saved payment methods
- Digital policy documents and ID cards
- Claims status tracking and history
- Personal information updates
- Secure messaging with customer service
Mobile apps extend these capabilities to smartphones and tablets, allowing on-the-go access to policy information. Progressive carriers integrate with health tracking apps and provide educational resources through their platforms.
However, technology shouldn't replace human support. The best companies balance digital convenience with accessible phone representatives who can handle complex questions or situations requiring personal attention.
Rate Increase History and Transparency
While no medigap insurance company can guarantee future rates, examining historical rate increase patterns provides insight into pricing stability.
Request rate increase history for the past five years for your specific plan type. Companies with consistent, moderate increases (3-7% annually) demonstrate more stable pricing than those with erratic jumps or long periods of no increases followed by large adjustments.
Transparency in rate communications matters significantly. Reputable insurers explain the reasons for increases, whether driven by medical inflation, increased utilization, or regulatory changes. They provide advance notice (typically 60 days) and clearly outline your options if rates become unaffordable.
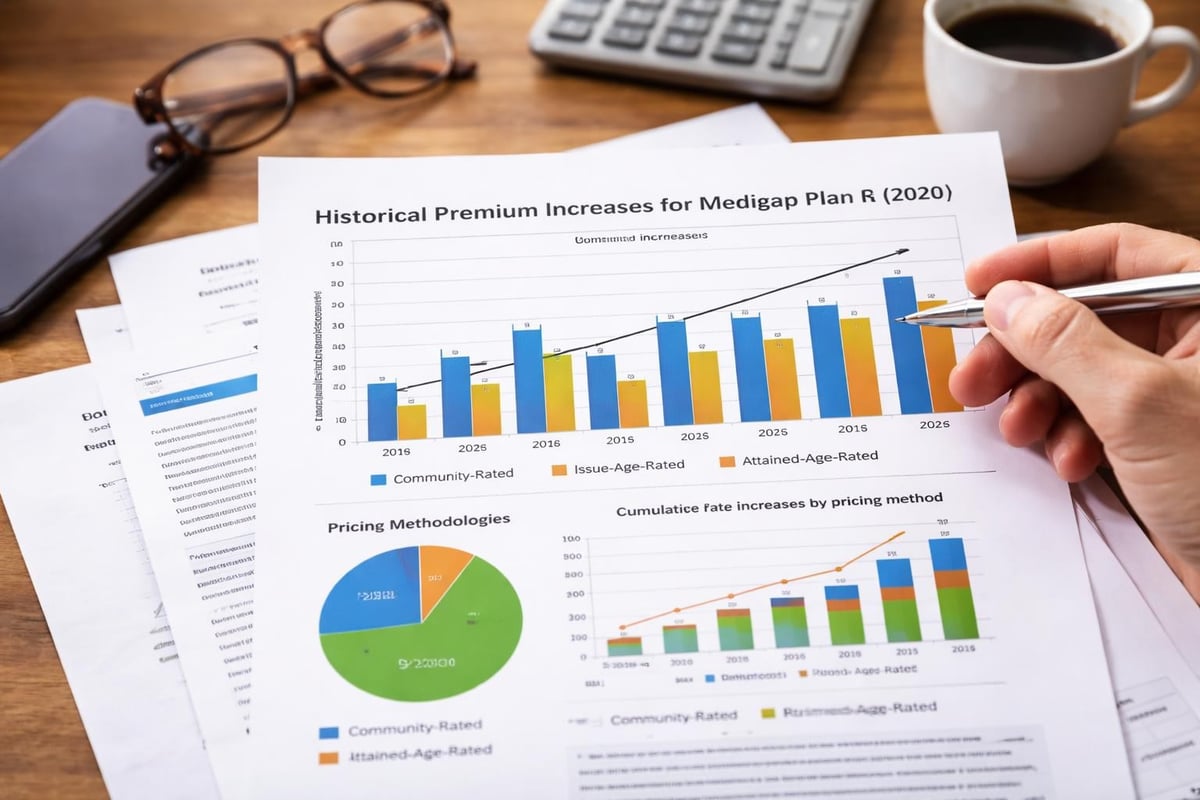
Research from the Kaiser Family Foundation on Medicare coverage sources demonstrates that Medigap enrollment patterns and premium trends vary significantly by geographic region and demographic factors.
Special Considerations for High-Risk Health Conditions
Your health status during the open enrollment period doesn't affect Medigap premiums or eligibility. However, outside this protected period, medical underwriting applies in most states.
Pre-existing condition waiting periods no longer apply to Medigap policies sold after 1990, but companies can deny coverage entirely based on health conditions when you apply outside guaranteed issue periods.
Some states offer additional consumer protections:
- Birthday rule states allow annual plan changes within 30 days of your birthday
- Anniversary rule states provide guaranteed issue rights on your policy anniversary
- Continuous coverage requirements in some states prevent denial if you're switching from another supplement
Understanding your state's specific rules helps you navigate coverage changes strategically.
Coordination with Other Coverage Types
A medigap insurance company policy works exclusively with Original Medicare Parts A and B. You cannot combine Medigap with Medicare Advantage plans, as these are different coverage approaches.
Employer or union coverage may provide similar benefits to Medigap. Before purchasing a supplement, verify whether your employer coverage is creditable. The CMS guidance on creditable coverage explains how to evaluate whether existing coverage meets Medicare standards.
Medicare Part D for prescription drug coverage operates independently from Medigap (except for Plans C and F, which include limited drug coverage for those grandfathered in). You'll need a separate Part D plan to cover prescription medications comprehensively.
Medicaid and Medigap Interaction
Dual-eligible beneficiaries qualifying for both Medicare and Medicaid typically don't need Medigap, as Medicaid covers most out-of-pocket costs. However, those just above Medicaid income limits may find Medigap provides essential financial protection.
Medicare Savings Programs help pay Medicare premiums, deductibles, and coinsurance for those with limited income. These state-administered programs can make Medigap more affordable by covering the monthly premium.
Switching Between Medigap Insurance Companies
You can change medigap insurance company providers anytime, though underwriting may apply outside guaranteed issue periods. Switching makes sense when you find significantly lower premiums for identical coverage.
Trial right provisions allow you to try a Medicare Advantage plan for up to 12 months and return to Medigap without medical underwriting. This applies only if you dropped Medigap to try Advantage and decide to switch back.
When switching carriers:
- Apply for the new policy before canceling your existing coverage
- Wait for written approval of your new policy
- Confirm the effective date of new coverage
- Only then cancel your previous policy to avoid coverage gaps
Never cancel existing coverage before securing new approval, as health changes could result in denial, leaving you without supplemental coverage.
For expert assistance with Medicare Supplement plans in Burlington NC and surrounding areas, professional guidance ensures smooth transitions between carriers.
Reading and Understanding Ratings Methodologies
Various organizations rate medigap insurance company providers, but understanding their methodologies ensures you interpret ratings accurately.
NerdWallet’s ratings methodology for Medicare Supplement Insurance considers financial strength ratings, complaint index scores from state regulators, plan availability, and premium competitiveness. Each factor receives different weighting in the overall score.
J.D. Power customer satisfaction surveys measure policyholder experiences across dimensions like claims processing, customer service, premium value, and communications. These ratings reflect actual user experiences rather than just financial metrics.
State insurance department complaint ratios compare the number of complaints against an insurer relative to their market share. A ratio above 1.0 indicates higher-than-expected complaint volume, suggesting potential service issues.
Weighting Different Rating Factors
When evaluating a medigap insurance company, balance multiple data points:
- Financial strength (40% weight): Ensures long-term stability
- Premium competitiveness (30% weight): Impacts affordability
- Customer satisfaction (20% weight): Reflects service quality
- Complaint ratios (10% weight): Indicates problem severity
This balanced approach prevents overemphasis on any single factor while ensuring all critical elements receive consideration.
Regional Carrier Options in North Carolina
North Carolina residents have access to numerous medigap insurance company options, with availability particularly strong in urban areas like Greensboro, Winston Salem, High Point, and Kernersville.
National carriers with significant North Carolina presence include companies known for competitive rates and strong customer service. Regional carriers sometimes offer advantages in local market knowledge and personalized service through area agents.
Local presence matters when you prefer face-to-face meetings or have complex questions requiring in-person assistance. While phone and digital support suffice for many beneficiaries, others value local office access.
Community involvement and reputation in specific regions like the Triad Area can indicate a company's commitment to serving local Medicare beneficiaries effectively. Long-standing regional presence often correlates with stable pricing and reliable service.
Attending Medicare seminars provides opportunities to learn about local options and ask questions in an educational setting without sales pressure.
Understanding Academic Research on Medigap
Academic studies examining Medigap markets provide valuable insights into pricing trends, coverage patterns, and policy implications.
Research on adverse selection and moral hazard in Medigap demonstrates that supplemental insurance influences healthcare utilization patterns. Beneficiaries with comprehensive Medigap coverage use more healthcare services on average than those with Original Medicare alone, as cost-sharing barriers are reduced.
Adverse selection occurs when individuals expecting higher healthcare needs are more likely to purchase comprehensive coverage. This can drive up premiums over time as the risk pool includes proportionally more high-cost beneficiaries.
Understanding these dynamics helps explain why Medigap premiums increase annually and why healthy individuals might consider high-deductible options to reduce monthly costs.
Policy Implications for Consumers
While academic research focuses on market-level trends, individual beneficiaries should focus on personal healthcare needs rather than population averages. Comprehensive coverage provides financial protection and peace of mind that often justifies higher premiums, especially for those with chronic conditions or frequent medical needs.
The relationship between a medigap insurance company and its policyholders remains fundamentally about managing financial risk while ensuring access to necessary healthcare services without catastrophic out-of-pocket expenses.
Making Your Final Decision
Choosing the right medigap insurance company requires balancing multiple factors aligned with your priorities, budget, and healthcare needs.
Create a comparison spreadsheet including:
- Monthly premium for your specific plan and age
- Financial strength ratings from multiple agencies
- Customer satisfaction scores
- Historical rate increase percentages
- Local agent availability
- Digital tool capabilities
Schedule consultations with top candidates, either directly or through an independent agent. Ask specific questions about scenarios relevant to your situation, such as claims processing for specialists you see regularly or coverage when traveling.
Trust your instincts about company responsiveness and transparency during the research process. How a medigap insurance company treats prospective customers often reflects how they'll treat policyholders.
For personalized assistance comparing options in the Greensboro, Winston Salem, High Point, or Kernersville areas, visit moserinsurancegroup.com to connect with experienced professionals who can guide your decision-making process.
Remember that while switching later is possible, selecting the right carrier initially saves time, reduces stress, and often results in better long-term value. Taking time to research thoroughly yields dividends throughout your Medicare years.
Selecting the right medigap insurance company provides financial security and healthcare peace of mind throughout your retirement years. By evaluating financial strength, premium competitiveness, customer service quality, and rate stability, you can identify carriers offering the best combination of value and reliability for your specific situation. Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate Medicare Supplement options with clear guidance and personalized support, ensuring you make confident insurance decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Medicare coverage needs with experienced professionals who prioritize education over sales tactics.
Recent Comments