
Managing healthcare costs becomes increasingly important as you approach Medicare eligibility, especially when living on a fixed income. A medicare savings plan offers crucial financial assistance to individuals who qualify based on income and resources, helping cover premiums, deductibles, and copayments that Medicare doesn't pay. For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, understanding these programs can mean the difference between struggling with medical bills and maintaining financial stability while receiving quality healthcare.
Understanding Medicare Savings Programs
The medicare savings plan consists of four distinct programs administered through state Medicaid offices, each designed to help Medicare beneficiaries with limited income and resources. These programs work alongside your existing Medicare coverage to reduce or eliminate the out-of-pocket costs that typically accompany Medicare Part A and Part B.
The Center for Medicare Advocacy provides comprehensive details about how these programs function as the bridge between Medicare and Medicaid, offering support to those who need it most. The programs don't replace Medicare but supplement it by covering expenses that would otherwise come directly from your budget.
The Four Program Types
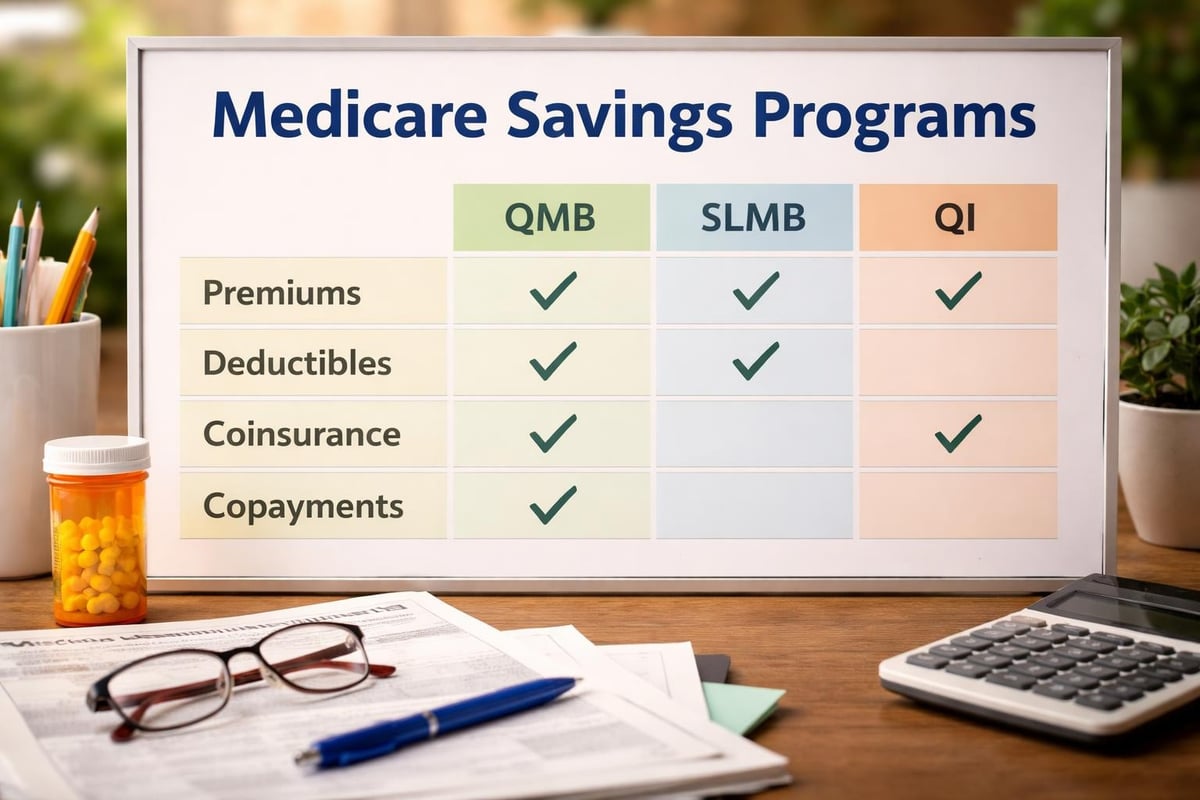
Understanding which medicare savings plan fits your situation requires knowing the differences between each program type:
| Program Type | What It Covers | Income Limit (2026) | Resource Limit |
|---|---|---|---|
| Qualified Medicare Beneficiary (QMB) | Part A & B premiums, deductibles, coinsurance, copayments | Up to 100% FPL | $9,430 individual / $14,130 couple |
| Specified Low-Income Medicare Beneficiary (SLMB) | Part B premiums only | 100-120% FPL | $9,430 individual / $14,130 couple |
| Qualifying Individual (QI) | Part B premiums only | 120-135% FPL | $9,430 individual / $14,130 couple |
| Qualified Disabled & Working Individuals (QDWI) | Part A premiums only | Up to 200% FPL | $4,000 individual / $6,000 couple |
The QMB program provides the most comprehensive coverage, making it particularly valuable for those with frequent medical needs. When you qualify for a medicare savings plan, you automatically receive Extra Help with prescription drug costs, which can save hundreds of dollars monthly on medications.
Eligibility Requirements and Income Guidelines
Qualifying for a medicare savings plan depends on meeting specific income and asset requirements that vary by program type. The Federal Poverty Level (FPL) serves as the benchmark for determining eligibility, with limits adjusted annually to reflect economic conditions.
For 2026, a single individual earning approximately $15,060 annually or less would qualify for QMB coverage, while a married couple with a combined income of $20,440 or less would meet the same threshold. These figures represent 100% of the federal poverty level and establish the foundation for all medicare savings plan calculations.
Countable Resources Explained
Resources include assets you own that could be converted to cash for living expenses. However, not everything counts toward your resource limit:
Excluded Resources:
- Your primary home and surrounding property
- One vehicle (regardless of value)
- Household goods and personal belongings
- Burial plots and certain burial funds
- Life insurance with face value under $1,500
- Property essential for self-support
Countable Resources:
- Bank accounts (checking, savings, CDs)
- Stocks, bonds, and mutual funds
- Second vehicles or recreational vehicles
- Additional property or real estate
- Cash value of life insurance exceeding limits
The QDWI program applies different resource limits because it serves working individuals with disabilities who need Part A coverage. Understanding these distinctions helps you prepare accurate documentation when applying for a medicare savings plan.
Financial Benefits and Cost Savings
The financial impact of enrolling in a medicare savings plan extends well beyond monthly premium assistance. For someone paying the standard Medicare Part B premium of $185 in 2026, SLMB or QI programs save $2,220 annually on that expense alone.
QMB participants enjoy even greater benefits. Consider someone hospitalized twice in one year. Without a medicare savings plan, they would face two separate Part A deductibles totaling $3,256, plus 20% coinsurance on all Part B services. QMB coverage eliminates these expenses entirely, potentially saving tens of thousands of dollars for individuals with significant healthcare needs.
Breaking Down Monthly Savings
Let's examine realistic savings scenarios for Triad Area residents:
Scenario 1: Single senior with diabetes
- Part B premium savings: $185/month
- Average copayments for office visits: $60/month
- Prescription copayment assistance: $150/month
- Total monthly savings: $395
Scenario 2: Married couple, one spouse with heart condition
- Part B premium savings (one person): $185/month
- Hospital deductible coverage: $271/year ($22.58/month average)
- Specialist visit copayments: $120/month
- Total monthly savings: $327.58
These savings compound over time, providing financial breathing room for other essential expenses like housing, food, and utilities. AARP’s overview of Medicare Savings Programs emphasizes how these benefits help seniors maintain independence while managing chronic conditions.
Application Process and Documentation
Applying for a medicare savings plan requires working with your state Medicaid office, not directly through Medicare or Social Security. In North Carolina, residents of Greensboro, Winston Salem, High Point, and Kernersville submit applications through the Department of Health and Human Services.
The application process typically takes 45 to 60 days from submission to approval, though this timeline varies by state and application volume. Starting your application three months before you need coverage ensures seamless financial protection when your medical expenses begin.
Required Documentation Checklist
Gathering documentation beforehand streamlines your medicare savings plan application:
- Proof of Medicare enrollment (Medicare card or award letter)
- Income verification for the past month (pay stubs, Social Security statements, pension documents)
- Bank statements showing balances for all accounts from the past three months
- Investment statements (stocks, bonds, mutual funds, retirement accounts)
- Property documentation (deed for home, vehicle registration, other real estate)
- Life insurance policies showing face value and cash value
- Burial fund documentation if applicable
For couples, both spouses must provide complete documentation even if only one person has Medicare. The combined household income and resources determine eligibility for a medicare savings plan, making transparency essential throughout the process.
Common Misconceptions and Program Facts
Many eligible individuals never apply for a medicare savings plan because of persistent myths about these programs. MACPAC’s analysis of Medicare Savings Programs reveals that millions of Americans qualify but remain unenrolled due to misinformation or lack of awareness.
Myth: You must be on Medicaid to qualify
This misconception prevents countless seniors from applying. While medicare savings plan programs are administered through state Medicaid offices, you don't need to receive Medicaid services to qualify. The programs have separate eligibility criteria focused solely on helping with Medicare costs.
Myth: Owning a home disqualifies you
Your primary residence never counts toward resource limits, regardless of its value. Even if you own a home worth $500,000, you can still qualify for a medicare savings plan if your other countable assets and income fall within program guidelines.
Myth: The application is too complicated
While the application requires documentation, assistance is available throughout the Triad Area. Insurance professionals can guide you through the process, ensuring you submit complete applications with proper documentation.
Facts About Program Flexibility
- Monthly premium reimbursement: Some states reimburse Part B premiums paid before QMB approval, potentially going back several months
- No copayments to providers: QMB beneficiaries cannot be billed for Medicare copayments or coinsurance under federal law
- Automatic Extra Help: Approval for any medicare savings plan automatically qualifies you for prescription drug cost assistance
- Annual recertification: You must reapply yearly, but the process becomes simpler once you're enrolled
Coordination with Other Medicare Benefits
Understanding how a medicare savings plan interacts with your other Medicare coverage maximizes your benefits while avoiding coverage gaps. If you're enrolled in a Medicare Advantage plan, your savings program still covers your share of costs according to the plan's structure.
For those comparing differences in Medicare plans, knowing your QMB or SLMB status influences which supplemental coverage makes sense. You may not need a Medigap policy if QMB already covers your deductibles and coinsurance, potentially saving additional money monthly.
Medicare Advantage Considerations
| Factor | With Medicare Savings Plan | Without Medicare Savings Plan |
|---|---|---|
| Plan premiums | Covered (if premium is just Part B amount) | Out-of-pocket expense |
| Copayments | Covered for QMB | Full copayment responsibility |
| Maximum out-of-pocket | Effectively $0 for QMB | Plan maximum (often $3,000-$8,000) |
| Drug coverage | Extra Help applies | Standard Part D costs |
The Medicare Shared Savings Program operates differently from medicare savings plan programs. While the Shared Savings Program focuses on provider efficiency and quality care delivery, state-administered savings programs directly reduce beneficiary costs based on financial need.
State-Specific Variations and North Carolina Programs
While federal guidelines establish baseline requirements for medicare savings plan eligibility, states implement these programs with some flexibility. North Carolina has worked to streamline enrollment processes and reduce administrative barriers for residents throughout the Triad Area.
Recent policy changes in North Carolina simplified asset verification requirements, making it easier for Greensboro, Winston Salem, High Point, and Kernersville residents to prove eligibility without extensive documentation of every minor asset. The state also extended the recertification period in some cases, reducing the frequency of paperwork submissions.
North Carolina Application Resources
- Online application: Available through ePASS (Electronic Prepared Application for Social Services)
- Phone assistance: County Departments of Social Services provide application help
- In-person support: Local DSS offices throughout the Triad Area accept walk-in appointments
- Community assistance: Nonprofit organizations and insurance advisors offer free application guidance
For personalized assistance with your medicare savings plan application, contact Moser Insurance Group Inc at 336-862-1763 or via email at moserinsurancegroup@gmail.com. Our team understands North Carolina's specific requirements and can verify your eligibility before you invest time in the formal application process.
Impact on Prescription Drug Costs
One of the most significant yet underappreciated benefits of qualifying for a medicare savings plan is automatic enrollment in Medicare's Extra Help program for prescription drugs. This coordination between programs creates comprehensive affordability across your entire healthcare spectrum.
Extra Help reduces Part D premiums to $0 or very low amounts, eliminates the coverage gap (donut hole), and caps copayments at $4.50 for generic drugs and $11.20 for brand-name medications in 2026. For someone taking multiple maintenance medications, these savings can exceed $3,000 annually.
Monthly prescription cost comparison:
-
Generic diabetes medication (no Extra Help): $45
-
Generic diabetes medication (with Extra Help): $4.50
-
Savings: $40.50 per medication
-
Brand-name cholesterol medication (no Extra Help): $380
-
Brand-name cholesterol medication (with Extra Help): $11.20
-
Savings: $368.80
Taking just these two medications, a QMB beneficiary saves approximately $409.30 monthly, or $4,911.60 yearly, on prescriptions alone. Combined with medicare savings plan coverage of premiums and copayments, total annual savings often exceed $8,000 for individuals with regular healthcare needs.
When Life Changes Affect Eligibility
Major life events can impact your medicare savings plan eligibility, requiring immediate notification to your state Medicaid office. Understanding these triggers helps you maintain benefits or reapply if circumstances change.
Changes Requiring Immediate Reporting
- Inheritance or receipt of lump-sum payments
- Sale of property or other assets
- Change in household composition (marriage, divorce, death of spouse)
- Increase in income (pension adjustments, Social Security raises)
- Return to work or change in employment status
- Relocation to a different state or county
Small annual increases like the Social Security cost-of-living adjustment (COLA) rarely disqualify current beneficiaries because income limits adjust proportionally. However, receiving a $50,000 inheritance would push most people over resource limits temporarily, requiring you to report the change within 10 days.
If you lose eligibility due to increased income or resources, you can reapply once your financial situation changes again. The programs are designed to provide assistance during periods of need, not to permanently exclude individuals who experience temporary improvements in their finances.
Working with Insurance Professionals
Navigating medicare savings plan eligibility, applications, and coordination with other coverage types can feel overwhelming. Working with experienced insurance advisors simplifies this process while ensuring you maximize all available benefits.
At Moser Insurance Group Inc, we help Triad Area residents understand how savings programs fit within their complete Medicare strategy. We can review your income and resources before you apply, helping you determine which program type suits your situation and what documentation you'll need.
Questions to Ask Your Insurance Advisor
- Based on my current income and assets, which medicare savings plan should I target?
- How will this program affect my current Medicare Supplement or Advantage plan?
- What happens to my coverage if I'm approved mid-year?
- Can you help me gather and organize the required documentation?
- What should I do if my application is denied?
Many people discover they qualify for programs they never knew existed. A comprehensive review of your Medicare options often uncovers multiple savings opportunities, from medicare savings plan enrollment to selecting the most cost-effective prescription drug plan or exploring priority health Medicare Advantage options in your area.
Special Enrollment Periods and Timing
While you can apply for a medicare savings plan anytime during the year, strategic timing can maximize your benefits and coordinate with other Medicare decisions. Understanding Special Enrollment Periods (SEPs) helps you align all your coverage changes efficiently.
If approved for a medicare savings plan, you gain a SEP allowing you to change Medicare Advantage or Part D prescription drug plans. This flexibility matters because your new QMB or SLMB status may make different plans more advantageous than what you originally selected.
Optimal application timing:
- Three months before Medicare eligibility: Ensures coverage starts simultaneously with your Medicare benefits
- During Medicare Annual Enrollment Period (October 15-December 7): Allows coordinated changes to all coverage types
- After major life changes: Apply within 30 days of events affecting household income
- Immediately upon learning of the program: Don't delay if you're struggling with Medicare costs
For residents preparing for their Initial Enrollment Period, reviewing resources about being new to Medicare alongside medicare savings plan information creates a comprehensive transition strategy. This dual preparation prevents coverage gaps and ensures maximum financial protection from day one.
Long-Term Planning and Financial Security
Enrolling in a medicare savings plan represents more than immediate cost relief. It's a long-term financial planning tool that preserves retirement savings, reduces stress about healthcare expenses, and allows you to focus on health rather than bills.
Consider the cumulative impact over a typical 20-year retirement period. A QMB beneficiary saving $6,000 annually in medical expenses preserves $120,000 in retirement assets that would otherwise go toward healthcare costs. This preserved capital generates investment returns, compounds over time, and remains available for other retirement needs or legacy planning.
Building Comprehensive Coverage
Your medicare savings plan forms one component of complete retirement healthcare planning:
- Medicare Part A and B: Hospital and medical insurance foundation
- Medicare Savings Program: Reduces or eliminates Part A/B out-of-pocket costs
- Part D coverage: Prescription drug insurance with Extra Help cost reduction
- Supplemental insurance: May be unnecessary with QMB coverage
- Long-term care planning: Separate consideration from Medicare benefits
For comprehensive guidance on coordinating all these elements, visit moserinsurancegroup.com or call 336-862-1763 to schedule a personal consultation. We'll review your complete financial picture and ensure you're leveraging every available program to minimize healthcare costs throughout retirement.
Advocacy and Appeals Process
Despite clear eligibility, some medicare savings plan applications are initially denied due to documentation issues, calculation errors, or misunderstanding of asset rules. Knowing your rights and the appeals process ensures you receive benefits you legally qualify for.
If your application is denied, you receive a written notice explaining the reason and outlining your appeal rights. You typically have 30 days from the denial date to request a hearing with your state Medicaid agency. Many denials are overturned when applicants provide additional documentation or clarify asset valuations.
Common Denial Reasons and Solutions
| Denial Reason | Solution Approach |
|---|---|
| Income over limit | Provide complete documentation; ensure calculation includes only countable income |
| Resources exceed threshold | Clarify which assets are excluded; provide proper home ownership documentation |
| Incomplete application | Submit missing documents promptly; work with advisor to ensure completeness |
| Missing verification | Obtain required statements from banks, employers, or government agencies |
| Household composition error | Clarify living situation and dependency relationships |
Policy options for increasing Medicare Savings Programs enrollment address systemic barriers that prevent eligible individuals from accessing benefits. Advocacy organizations continue working to simplify applications and increase awareness, particularly among communities with low enrollment rates despite high eligibility.
Technology and Online Resources
Modern technology has simplified medicare savings plan research, application, and management. North Carolina's ePASS system allows online applications from the comfort of your Greensboro, Winston Salem, High Point, or Kernersville home, with secure document uploads replacing mail or in-person delivery.
Several verification tools help you estimate eligibility before starting the formal application:
- Medicare.gov Plan Finder: Includes screening questions for savings programs
- State Medicaid websites: Provide eligibility calculators specific to your state
- Benefits Checkup (NCOA): Comprehensive screening for multiple assistance programs
- Insurance advisor software: Professional tools offering detailed eligibility analysis
While technology streamlines processes, human guidance remains valuable. Complex financial situations, unusual asset types, or confusion about documentation requirements benefit from experienced professional interpretation. Combining online resources with personalized advice from Moser Insurance Group Inc ensures accuracy while maintaining convenience.
Understanding how a medicare savings plan can reduce your healthcare costs provides financial relief and peace of mind throughout your retirement years. These programs help thousands of Triad Area residents maintain their health without sacrificing financial security, making quality medical care accessible regardless of income level. At Moser Insurance Group Inc, we specialize in helping individuals and families throughout Greensboro, Kernersville, High Point, and Winston Salem navigate Medicare options with clear, pressure-free guidance. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss how we can help you maximize your Medicare benefits while minimizing your out-of-pocket costs.
Recent Comments