
Understanding your healthcare options as you approach age 65 can feel overwhelming, especially when navigating the complexities of federal programs. Medicare Part A and B form the foundation of Original Medicare, providing essential coverage for hospital stays, doctor visits, and preventive services. For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, making informed decisions about these benefits can significantly impact both healthcare quality and financial security. This comprehensive guide explains what medicare part a and b cover, how much they cost, and how to enroll effectively.
What Medicare Part A Covers
Medicare Part A, often called hospital insurance, protects you when you need inpatient care. This coverage extends beyond simple overnight stays to include several critical healthcare situations.
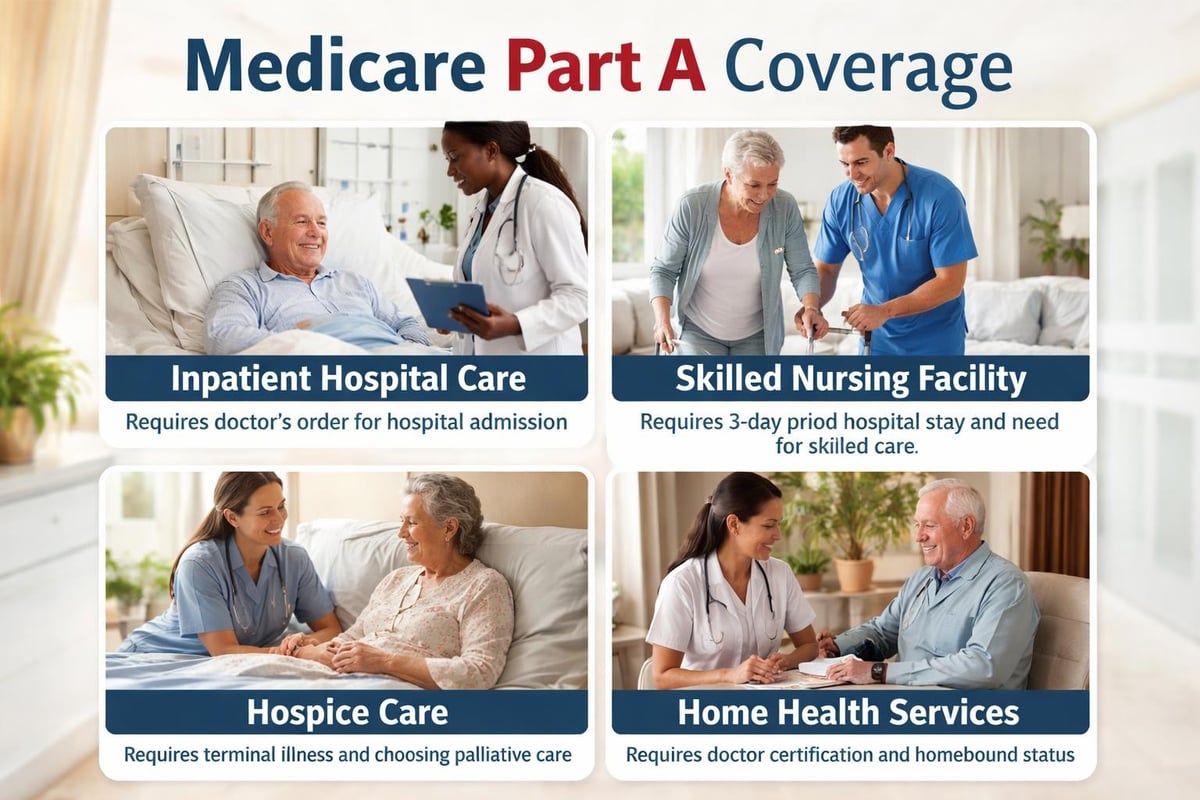
Inpatient Hospital Care represents the primary focus of Part A. When you require admission to a hospital for medical treatment, surgery, or observation, this coverage handles the costs associated with your room, meals, nursing care, and medications administered during your stay.
Skilled Nursing Facility Services
Part A also covers skilled nursing facility care, but only under specific conditions. You must have spent at least three consecutive days as an admitted hospital patient, and your doctor must certify that you need daily skilled care. This coverage applies to the first 100 days per benefit period, with different cost-sharing requirements at different intervals.
- Semi-private room accommodations
- Meals and dietary services
- Skilled nursing and rehabilitation services
- Physical therapy, occupational therapy, and speech-language pathology
- Medical supplies and equipment used in the facility
The distinction between skilled nursing care and custodial care matters significantly. Part A does not cover long-term custodial care where residents need help with daily activities but not medical treatment.
Hospice and Home Health Services
Hospice care receives coverage when a doctor certifies that a patient has a terminal illness with a life expectancy of six months or less. This benefit includes pain management, counseling, medications related to the terminal illness, and respite care for family caregivers.
Home health services qualify for Part A coverage when you are homebound and require intermittent skilled nursing care, physical therapy, or speech-language pathology services. Your doctor must order these services and create a care plan that a Medicare-certified agency follows.
Understanding Medicare Part B Coverage
Medicare Part B, known as medical insurance, addresses outpatient services and preventive care. This component of medicare part a and b handles doctor visits, diagnostic tests, and medical equipment that helps you maintain health outside hospital settings.
Doctor Services and Outpatient Care form the cornerstone of Part B benefits. Whether you visit your primary care physician in Winston Salem or see a specialist in High Point, Part B covers medically necessary services including examinations, diagnoses, and treatments.
Preventive Services and Screenings
Part B emphasizes prevention through comprehensive screening programs. Many preventive services come with no out-of-pocket costs when you use providers who accept Medicare assignment.
| Preventive Service | Frequency | Cost Sharing |
|---|---|---|
| Annual Wellness Visit | Once per year | $0 |
| Mammograms | Once per year | $0 |
| Colonoscopy Screening | Varies by risk | $0 (screening) |
| Diabetes Screening | Up to 2 per year | $0 |
| Cardiovascular Screening | Every 5 years | $0 |
| Bone Density Test | Once every 2 years | $0 |
The "Welcome to Medicare" preventive visit provides a baseline health assessment within the first 12 months of Part B enrollment. This comprehensive review creates a personalized prevention plan and serves as your foundation for ongoing care.
Medical Equipment and Supplies
Durable medical equipment (DME) receives coverage when deemed medically necessary. This category includes wheelchairs, walkers, hospital beds, oxygen equipment, and diabetic testing supplies. Your doctor must prescribe the equipment, and you typically need to use Medicare-approved suppliers.
Part B also covers outpatient mental health services, ambulance transportation when other transportation could endanger your health, and certain medications administered in a doctor's office.
Medicare Part A and B Cost Breakdown
Understanding the financial aspects of medicare part a and b helps you budget effectively for healthcare expenses. The costs include premiums, deductibles, and coinsurance that vary based on your situation.
Part A Costs and Premium-Free Benefits
Most people pay no premium for Part A because they or their spouse paid Medicare taxes while working. If you have 40 or more quarters of Medicare-covered employment, you qualify for premium-free Part A coverage.
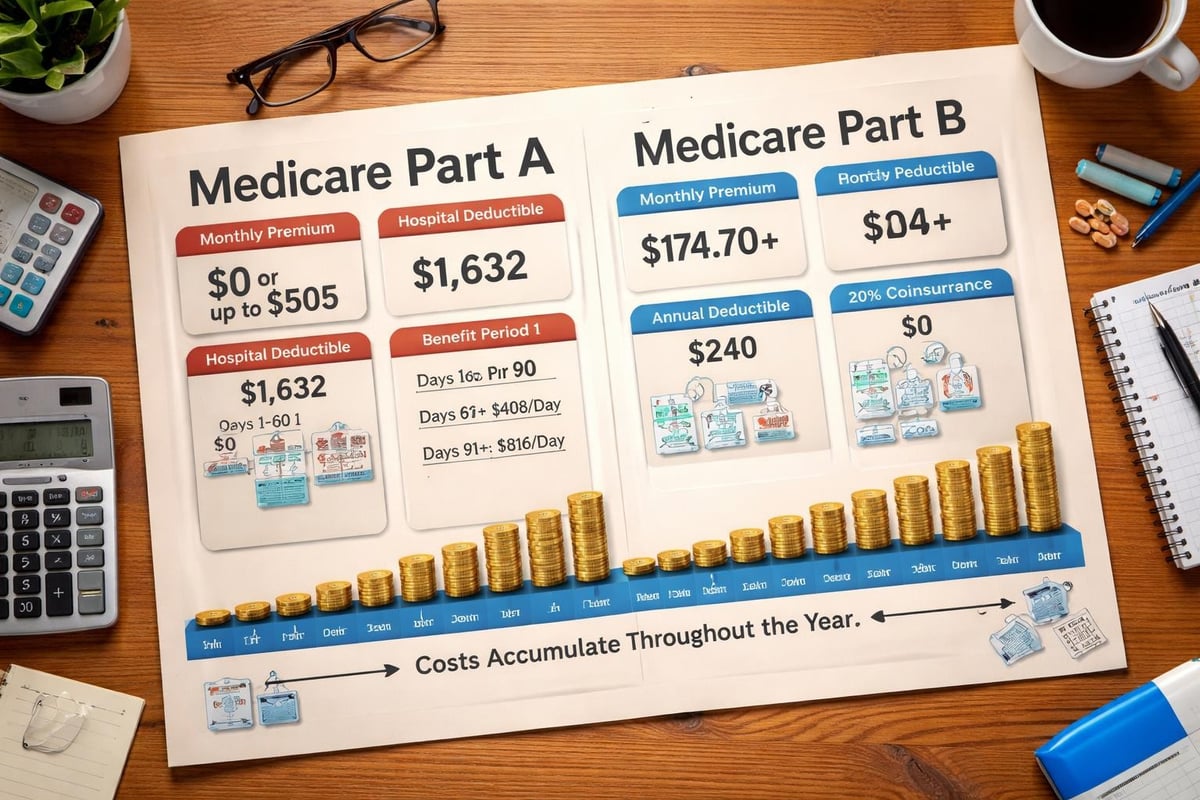
Those without sufficient work credits face monthly premiums in 2026. The costs associated with Medicare Parts A and B reflect annual adjustments based on inflation and healthcare spending trends.
Part A Cost Sharing for 2026:
- Deductible: Applies per benefit period for inpatient hospital stays
- Days 1-60: Deductible only
- Days 61-90: Daily coinsurance
- Days 91+: Lifetime reserve days with higher daily coinsurance
- Skilled nursing facility: $0 for days 1-20, daily coinsurance for days 21-100
A benefit period begins when you enter a hospital or skilled nursing facility and ends when you have not received inpatient care for 60 consecutive days. You can have multiple benefit periods in a year, each requiring a new deductible.
Part B Premium and Cost Structure
Unlike Part A, everyone pays a monthly premium for Part B coverage. The standard premium amount applies to most beneficiaries, but high-income earners pay Income Related Monthly Adjustment Amounts (IRMAA) surcharges based on tax returns from two years prior.
| Modified Adjusted Gross Income (Individual) | Monthly Premium |
|---|---|
| $106,000 or less | Standard amount |
| $106,001 – $133,000 | Standard + IRMAA tier 1 |
| $133,001 – $167,000 | Standard + IRMAA tier 2 |
| $167,001 – $200,000 | Standard + IRMAA tier 3 |
| Above $500,000 | Standard + IRMAA tier 4 |
Part B also includes an annual deductible that resets each January. After meeting this deductible, you typically pay 20% coinsurance for most covered services. Since Part B has no out-of-pocket maximum, some Greensboro and Kernersville residents choose supplemental coverage to protect against unlimited cost exposure.
Enrollment Periods and Deadlines
Timing your enrollment in medicare part a and b correctly prevents coverage gaps and potential penalties. Several enrollment windows exist, each with specific rules and implications.
Initial Enrollment Period
Your Initial Enrollment Period (IEP) spans seven months, beginning three months before your 65th birthday month, including that month, and extending three months after. If your birthday falls on the first day of a month, your IEP starts four months prior.
During this window, you can enroll in both Part A and Part B simultaneously. Missing this period without qualifying for a Special Enrollment Period results in delayed coverage and possible late enrollment penalties.
- Review your eligibility three months before turning 65
- Determine if you have creditable coverage through an employer
- Complete enrollment through Social Security online, by phone, or in person
- Confirm your effective dates to ensure continuous coverage
- Contact Moser Insurance Group Inc at 336-862-1763 for personalized guidance
Special and General Enrollment Periods
Special Enrollment Periods apply when you have qualifying events such as losing employer coverage, moving outside your plan's service area, or qualifying for Extra Help with prescription drug costs. These periods protect you from penalties when you delay enrollment due to creditable coverage.
The General Enrollment Period runs from January 1 through March 31 annually. If you missed your IEP and don't qualify for a Special Enrollment Period, you can enroll during this window, but coverage doesn't begin until July 1. Additionally, you may face late enrollment penalties.
Late Enrollment Penalties:
- Part A penalty: 10% premium increase for twice the number of years you were eligible but didn't enroll
- Part B penalty: 10% premium increase for each 12-month period you could have had Part B but didn't sign up
- Both penalties typically last as long as you have Medicare coverage
Residents throughout High Point and Winston Salem can avoid these penalties by understanding their enrollment rights and acting promptly. If you're still working past age 65 with employer coverage, document your creditable coverage carefully.
How Part A and Part B Work Together
Medicare part a and b function as complementary components rather than redundant coverage. Together, they create Original Medicare, addressing different aspects of healthcare needs across various settings.
Coordination of Benefits
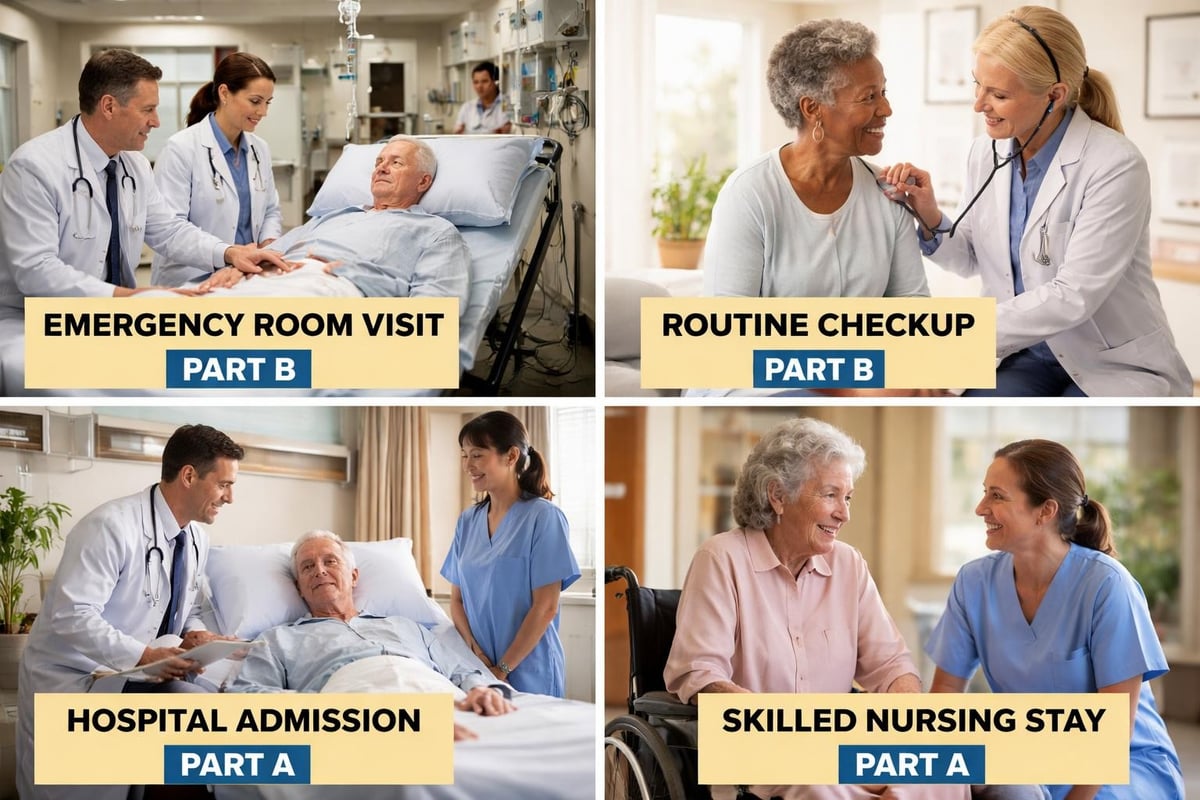
When you receive medical care, Part A and Part B determine coverage based on the setting and service type. Understanding which part applies helps you anticipate costs and select appropriate providers.
Hospital outpatient services fall under Part B, even though you're receiving care in a hospital building. The distinction between inpatient admission (Part A) and observation status (Part B) can significantly impact your out-of-pocket costs. Always verify your admission status if you spend time in a hospital.
Coverage Gaps and Supplemental Options
Original Medicare leaves certain gaps that affect beneficiaries financially. Neither Part A nor Part B covers routine dental care, vision services, hearing aids, or long-term custodial care. The 20% coinsurance for Part B services continues indefinitely without a cap.
Many Triad Area residents address these gaps through:
- Medicare Supplement (Medigap) policies that cover copayments, coinsurance, and deductibles
- Medicare Advantage plans that bundle Parts A and B with additional benefits
- Prescription drug coverage through Part D standalone plans or Medicare Advantage plans
Making informed decisions about supplemental coverage requires understanding your health needs, budget constraints, and preferred providers. Moser Insurance Group Inc provides personalized consultations to help Greensboro residents evaluate these options without pressure.
Making the Most of Your Medicare Benefits
Maximizing the value of medicare part a and b involves strategic planning and proactive healthcare management. Your approach to utilizing these benefits directly impacts both health outcomes and financial efficiency.
Choosing the Right Providers
Medicare accepts providers who meet specific certification standards, but not all certified providers accept Medicare assignment. Providers who accept assignment agree to charge only the Medicare-approved amount for services, limiting your out-of-pocket costs to the standard coinsurance percentage.
Using non-participating providers can increase your costs significantly. These providers may charge up to 15% above the Medicare-approved amount through balance billing, and you must pay the difference. When scheduling appointments in Kernersville or surrounding areas, always confirm that providers accept Medicare assignment.
Preventive Care Strategy
Take full advantage of the preventive services covered at no cost under Part B. These screenings detect health issues early when treatment is most effective and least expensive.
- Schedule your Annual Wellness Visit every year to update your prevention plan
- Complete recommended cancer screenings based on your age and risk factors
- Monitor chronic conditions through covered diabetes and cardiovascular screenings
- Receive vaccinations covered under Part B, including flu shots and pneumococcal vaccines
- Discuss any health concerns with your doctor during covered visits
Preventive care reduces the likelihood of expensive hospital stays and emergency interventions, making your Part A and Part B coverage work more efficiently.
Getting Personalized Help with Medicare Decisions
Navigating medicare part a and b becomes simpler with expert guidance tailored to your specific situation. Individual circumstances vary widely based on work history, income levels, existing health conditions, and family dynamics.
Moser Insurance Group Inc serves the Triad Area community by educating clients about their Medicare options without using high-pressure tactics. Whether you're approaching your Initial Enrollment Period or reconsidering your current coverage, personalized support helps you make confident decisions.
Resources Available to You:
| Resource Type | Description | Contact Method |
|---|---|---|
| Educational Seminars | Group presentations on Medicare basics | Medicare seminars |
| One-on-One Consultations | Personalized coverage reviews | Call 336-862-1763 |
| Email Support | Written answers to specific questions | moserinsurancegroup@gmail.com |
| Online Information | Articles, guides, and updates | moserinsurancegroup.com |
Local expertise matters when selecting Medicare coverage. Insurance professionals familiar with healthcare providers and facilities in Greensboro, High Point, Winston Salem, and Kernersville can recommend strategies that align with how you actually access care.
Common Medicare Part A and B Mistakes to Avoid
Even informed beneficiaries sometimes make errors that prove costly. Awareness of common pitfalls helps you navigate medicare part a and b successfully from the start.
Enrollment Timing Errors
Delaying enrollment without creditable coverage triggers late enrollment penalties that persist throughout your Medicare lifetime. Some people mistakenly believe they can wait until they need medical care to enroll, not realizing that enrollment periods have strict limitations.
If you're covered under a spouse's employer plan, verify whether that coverage qualifies as creditable. Group health plans from employers with fewer than 20 employees typically do not provide creditable coverage, requiring you to enroll in Medicare at age 65 regardless.
Misunderstanding Observation Status
Hospital observation status frequently confuses Medicare beneficiaries. You may spend several days in a hospital bed receiving care, assuming you're an admitted inpatient covered by Part A. If the hospital classifies you as under observation, Part B covers your stay instead, and you pay Part B coinsurance rather than the Part A deductible.
More critically, observation time doesn't count toward the three-day inpatient hospital stay required for skilled nursing facility coverage under Part A. Always ask your doctor about your admission status and request a change to inpatient status if your condition warrants it.
Assuming All Doctors Accept Medicare
While most physicians participate in Medicare, not all accept assignment. Some providers opt out of Medicare entirely, requiring you to pay the full cost upfront and seek reimbursement yourself. Before scheduling procedures or ongoing treatment, confirm that all providers involved accept Medicare assignment to avoid unexpected bills.
Coordinating Medicare with Other Coverage
Many beneficiaries maintain medicare part a and b alongside other insurance types. Understanding coordination of benefits rules ensures claims process correctly and you don't overpay for services.
Employer Coverage Coordination
If you continue working past age 65 with employer group health coverage, determine which insurance pays primary and which pays secondary. For employers with 20 or more employees, the employer plan typically pays first, and Medicare pays second. This arrangement allows you to delay Part B enrollment without penalty as long as you maintain the employer coverage.
Once you or your spouse stops working, you have an eight-month Special Enrollment Period to add Part B coverage. Notify Medicare promptly to avoid gaps between your employer coverage ending and Medicare beginning.
Veterans Benefits and Medicare
Veterans with VA healthcare benefits can use both systems, though neither pays for the other's services. VA benefits cover care received at VA facilities, while Medicare covers care from non-VA providers. Many veterans maintain both, using VA facilities for routine care and Medicare for emergencies or when VA appointments aren't timely.
Part A enrollment is typically free, so most veterans enroll even if they primarily use VA facilities. Part B requires a premium, leading some veterans to skip it initially. However, this decision should account for late enrollment penalties if you later want Part B coverage.
Regional Considerations for Triad Area Residents
Healthcare decisions in the Triad Area benefit from understanding local provider networks, facilities, and resources specific to Greensboro, Kernersville, High Point, and Winston Salem.
Local Healthcare Facilities
Major hospital systems throughout the region accept Medicare and provide comprehensive services covered under both Part A and Part B. Familiarity with facility locations, specialties, and quality ratings helps you plan care effectively.
Emergency situations require quick decisions, but for scheduled procedures and ongoing treatment, researching facility quality scores and patient satisfaction ratings optimizes outcomes. Medicare provides comparison tools that rate hospitals and nursing homes based on objective quality measures.
Community Resources and Support
Local organizations throughout the Triad Area offer Medicare counseling through State Health Insurance Assistance Programs (SHIP). These free services provide objective information about medicare part a and b options without selling insurance products.
Additionally, community centers and senior organizations frequently host educational events where you can learn about Medicare in group settings. These programs complement individualized advice from insurance professionals, giving you multiple perspectives on your choices.
For residents seeking comprehensive guidance that combines education with personalized plan selection, local agencies like Moser Insurance Group Inc offer the advantage of understanding both Medicare rules and regional healthcare landscapes. You can reach them at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation.
Medicare Part A and B provide the foundation for healthcare coverage as you age, but understanding their intricacies ensures you maximize benefits while minimizing costs. Whether you're approaching your Initial Enrollment Period or reviewing your current coverage options, informed decisions protect both your health and financial well-being. Moser Insurance Group Inc helps individuals and families throughout the Triad Area navigate Medicare choices with clear, personalized guidance. Visit Moser Insurance Group Inc to learn more about how we can support your Medicare journey without pressure, ensuring you make confident decisions that fit your unique needs.
Recent Comments