

Navigating the landscape of healthcare coverage as you approach or enter retirement can feel overwhelming. Medicare health plans represent one of the most significant decisions you'll make for your future wellbeing, impacting everything from routine doctor visits to prescription drug costs and hospital stays. Whether you're turning 65, retiring early, or helping a family member explore their options, understanding the full spectrum of Medicare coverage available in 2026 is essential. This comprehensive guide breaks down the critical components of Medicare health plans, helping residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, make informed choices about their healthcare future.
Understanding the Foundation of Medicare Health Plans
Medicare health plans come in several distinct forms, each designed to address different aspects of healthcare coverage. The program's structure can initially seem complex, but breaking it down into core components makes the decision-making process much more manageable.
Original Medicare forms the foundation of the program and consists of two primary parts:
- Part A (Hospital Insurance): Covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services
- Part B (Medical Insurance): Covers doctor visits, outpatient care, preventive services, medical equipment, and certain home health services
Most people don't pay a premium for Part A if they or their spouse paid Medicare taxes while working. Part B requires a monthly premium that varies based on income level.
The Centers for Medicare & Medicaid Services provides comprehensive information about how Medicare Advantage organizations operate within the broader Medicare framework, ensuring beneficiaries receive quality care.
Medicare Advantage: An Alternative Approach
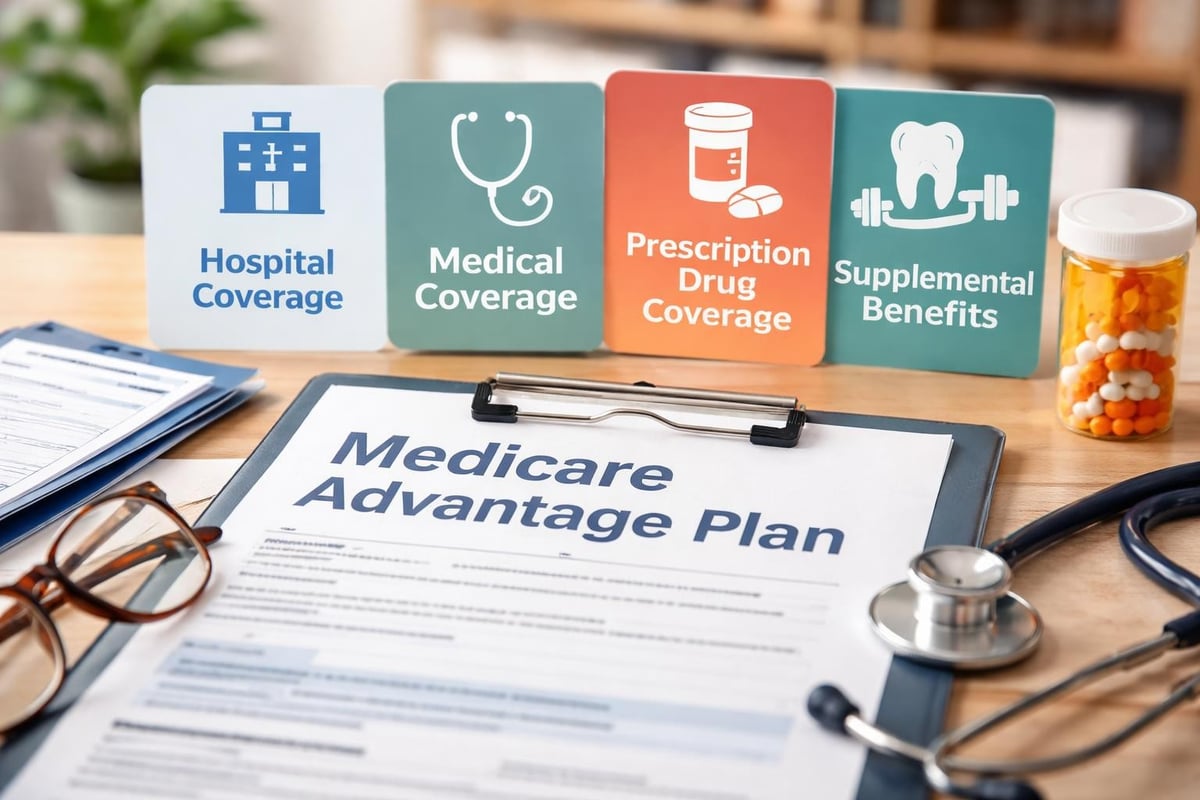
Medicare health plans extend beyond Original Medicare through Part C, commonly known as Medicare Advantage. These plans are offered by private insurance companies approved by Medicare and must cover everything Original Medicare covers, often with additional benefits.
Medicare Advantage plans typically include:
- Prescription drug coverage (Part D)
- Vision services
- Dental care
- Hearing aids
- Fitness programs
- Transportation to medical appointments
Many residents throughout Winston Salem and the broader Triad Area find that top Medicare Advantage plans offer comprehensive coverage that simplifies their healthcare management by bundling multiple services into one plan.
Prescription Drug Coverage Through Medicare Health Plans
Part D represents a critical component of Medicare health plans, addressing the significant costs many seniors face for prescription medications. While Part D is optional, most beneficiaries find this coverage valuable for managing medication expenses.
How Part D Plans Work
Prescription drug plans operate through a formulary system, which categorizes medications into different tiers. Each tier corresponds to a different cost-sharing amount:
| Tier Level | Medication Type | Typical Cost |
|---|---|---|
| Tier 1 | Generic drugs | Lowest copay |
| Tier 2 | Preferred brand drugs | Low to moderate copay |
| Tier 3 | Non-preferred brand drugs | Higher copay |
| Tier 4 | Specialty drugs | Highest cost-sharing |
| Tier 5 | Specialty tier medications | Percentage-based coinsurance |
Understanding your medication needs helps determine which best Medicare Part D plans align with your prescription requirements and budget considerations.
Part D plans include a coverage gap, sometimes called the "donut hole," which occurs after you and your plan have spent a certain amount on covered drugs. In 2026, coverage gap provisions continue to evolve, making it essential to review plan details annually.
For personalized guidance on prescription coverage, Moser Insurance Group Inc can be reached at 336-862-1763 or via email at moserinsurancegroup@gmail.com to discuss your specific medication needs.
Medigap Supplemental Insurance Options
Medicare health plans can be enhanced through Medigap policies, which are supplemental insurance plans designed to fill the "gaps" in Original Medicare coverage. These standardized plans help cover out-of-pocket costs like deductibles, copayments, and coinsurance.
Key advantages of Medigap policies include:
- Predictable healthcare costs
- Freedom to see any doctor who accepts Medicare
- Coverage when traveling outside the United States
- No network restrictions
- Guaranteed renewable coverage
Medigap plans are identified by letters (Plan A, Plan G, Plan N, etc.), with each letter representing a standardized set of benefits. Plan G has become one of the most popular options in 2026, offering comprehensive coverage at competitive premium rates.
It's important to note that you cannot have both a Medicare Advantage plan and a Medigap policy simultaneously. This distinction makes understanding your coverage preferences crucial before enrollment.
The fundamentals of Medicare basics have evolved significantly, making recent updates to coverage options particularly relevant for new beneficiaries in the Triad Area.
Enrollment Periods for Medicare Health Plans
Timing plays a critical role when selecting Medicare health plans. Missing enrollment windows can result in coverage gaps or lifetime penalties, making it essential to understand each enrollment period.
Initial Enrollment Period (IEP)
Your IEP spans seven months: the three months before your 65th birthday month, your birthday month, and three months after. This represents your first opportunity to enroll in Medicare Parts A and B without penalties.
Annual Enrollment Period (AEP)
Running from October 15 through December 7 each year, AEP allows beneficiaries to:
- Switch from Original Medicare to Medicare Advantage
- Change from one Medicare Advantage plan to another
- Return to Original Medicare from Medicare Advantage
- Add, drop, or change Part D prescription drug coverage
- Enroll in a Medicare Advantage plan for the first time
Changes made during AEP take effect January 1 of the following year.
Medicare Advantage Open Enrollment Period
From January 1 through March 31, current Medicare Advantage enrollees can switch to a different Medicare Advantage plan or return to Original Medicare and add a Part D plan. This period provides a second opportunity to adjust coverage if your initial selection doesn't meet expectations.
Special Enrollment Periods (SEPs)
Certain life events trigger SEPs, allowing enrollment changes outside standard periods:
- Moving to a new service area
- Losing employer coverage
- Qualifying for Medicaid
- Moving into a nursing home
- Experiencing plan contract violations
Residents in Greensboro, Kernersville, High Point, and Winston Salem should verify whether life changes qualify them for a SEP before making coverage decisions.
Evaluating Medicare Health Plans Quality and Performance
Not all Medicare health plans deliver the same level of service and member satisfaction. Medicare uses a five-star rating system to help beneficiaries compare plan quality and performance.
Understanding Star Ratings
The star rating system evaluates plans on multiple factors:
- Quality of preventive services
- Managing chronic conditions
- Member satisfaction
- Customer service performance
- Plan administrative efficiency
Plans earning 5 stars represent the highest quality options available. These 5-star Medicare Advantage plans often include special enrollment privileges, allowing beneficiaries to switch to them outside standard enrollment periods.
Research from the Agency for Healthcare Research and Quality examines care management programs and their outcomes, providing valuable insights into plan effectiveness.
| Star Rating | Performance Level | Plan Quality |
|---|---|---|
| 5 Stars | Excellent | Top-tier performance across all measures |
| 4 Stars | Above Average | Strong performance with minor improvement areas |
| 3 Stars | Average | Meets basic requirements, room for growth |
| 2 Stars | Below Average | Significant improvement needed |
| 1 Star | Poor | Substantial quality concerns |
Cost Considerations for Medicare Health Plans
Understanding the financial aspects of Medicare health plans helps you budget effectively for healthcare expenses in retirement. Multiple cost components require consideration beyond monthly premiums.
Premium Costs
Part B premiums in 2026 are adjusted annually based on income levels. Higher earners pay Income-Related Monthly Adjustment Amounts (IRMAA), which increase premiums significantly for beneficiaries exceeding specific income thresholds.
Medicare Advantage plans may have $0 premiums, though you still pay your Part B premium. Medigap policies charge separate premiums that vary by age, location, and tobacco use.
Out-of-Pocket Expenses
Different Medicare health plans structure cost-sharing differently:
Original Medicare typically requires:
- Part A deductible for hospital stays
- Part B annual deductible
- 20% coinsurance for most Part B services
- No annual out-of-pocket maximum
Medicare Advantage plans feature:
- Copayments for specific services
- Annual out-of-pocket maximums
- Network restrictions in most cases
- Potentially lower overall costs for frequent healthcare users
Analyzing your anticipated healthcare utilization helps determine which cost structure aligns with your financial situation.
Network Considerations and Provider Access
Medicare health plans differ significantly in how they structure provider networks. This distinction impacts your ability to see preferred doctors and access specific hospitals or specialists.
Original Medicare Provider Access
Original Medicare allows you to visit any doctor or facility that accepts Medicare nationwide. This flexibility appeals to beneficiaries who:
- Travel frequently
- Have established relationships with specific providers
- Want maximum choice without network restrictions
- Live in rural areas with limited plan availability
Medicare Advantage Network Structures
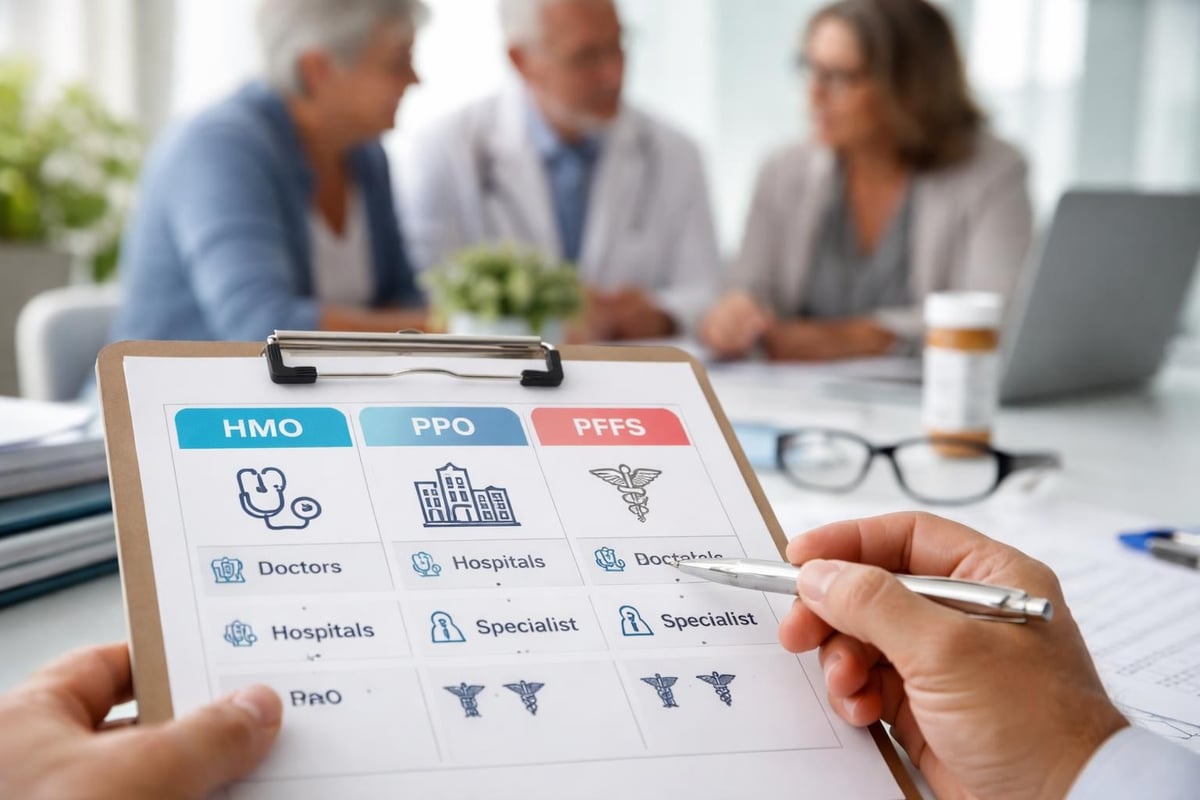
Most Medicare Advantage plans operate through networks, categorized as:
- Health Maintenance Organization (HMO): Requires using network providers except emergencies; needs referrals for specialists
- Preferred Provider Organization (PPO): Offers both in-network and out-of-network coverage; no referrals required
- Private Fee-for-Service (PFFS): Allows any willing provider accepting plan terms
- Special Needs Plans (SNP): Designed for beneficiaries with specific conditions or circumstances
Residents throughout the Triad Area should verify that their preferred doctors and facilities participate in plan networks before enrollment. The website moserinsurancegroup.com provides resources for comparing network options across different carriers.
Specialized Medicare Health Plans for Unique Needs
Certain beneficiaries benefit from specialized Medicare health plans designed to address specific health conditions or circumstances. These targeted options provide coordinated care for complex medical situations.
Chronic Special Needs Plans (C-SNPs)
C-SNPs serve beneficiaries with specific chronic conditions such as:
- Diabetes
- Cardiovascular disorders
- Chronic heart failure
- End-stage renal disease
These plans coordinate care through specialized provider teams familiar with managing specific conditions, often resulting in improved health outcomes and reduced complications.
Dual Eligible Special Needs Plans (D-SNPs)
D-SNPs serve individuals eligible for both Medicare and Medicaid, coordinating benefits between both programs. These plans typically feature:
- Low or no premiums
- Minimal cost-sharing
- Comprehensive prescription drug coverage
- Additional support services
Institutional Special Needs Plans (I-SNPs)
I-SNPs provide coverage for beneficiaries living in nursing facilities or requiring nursing-level care at home. These plans coordinate long-term care services with medical coverage.
Determining whether you qualify for specialized Medicare health plans requires understanding eligibility criteria and comparing benefits with standard options. Studies on quality assurance in Medicare highlight the importance of accountability measures in specialized care programs.
Comparing Medicare Health Plans Effectively
Making an informed decision about Medicare coverage requires systematic comparison of available options. Several factors warrant careful evaluation beyond monthly premiums.
Essential comparison points include:
- Total estimated annual costs (premiums + out-of-pocket)
- Prescription drug formulary and pharmacy network
- Provider network adequacy
- Extra benefits (dental, vision, hearing)
- Star ratings and member satisfaction scores
- Coverage when traveling
- Customer service accessibility
The Medicare Plan Finder tool at Medicare.gov allows side-by-side plan comparisons based on your location and specific needs. Entering your prescription medications and preferred providers generates personalized cost estimates.
For residents in High Point, Kernersville, and surrounding communities, local factors like provider availability and plan service areas significantly impact plan selection. Working with experienced advisors familiar with Triad Area healthcare systems proves invaluable during this process.
Regional Availability and Local Considerations
Medicare health plans vary significantly by geographic location. Plan availability, provider networks, and even premium costs differ between counties and zip codes throughout North Carolina.
Triad Area Specific Factors
Greensboro, Winston Salem, Kernersville, and High Point residents have access to multiple Medicare Advantage carriers and Part D options. However, plan benefits and networks differ within the region:
- Urban areas typically offer more plan choices
- Rural communities may have fewer Medicare Advantage options
- Hospital networks vary between Forsyth, Guilford, and Davidson counties
- Specialist availability influences network adequacy
Verifying plan availability in your specific zip code ensures you're comparing actually available options rather than plans not offered in your service area.
Carrier Reputation and Local Presence
Major carriers offering Medicare health plans in the Triad Area include national and regional insurers. Research indicates that structural accountability in Medicare health plans requires attention to government oversight, market dynamics, and professional standards.
Evaluating carrier reputation through member reviews, complaint ratios, and star ratings provides insight into day-to-day plan performance. Some beneficiaries prefer carriers with local offices for in-person support, while others prioritize comprehensive benefits regardless of office locations.
Understanding Coverage Coordination
Beneficiaries with multiple insurance sources must understand how Medicare health plans coordinate with other coverage types. Coordination of benefits rules determine which insurance pays first and how claims are processed.
Medicare with Employer Coverage
Active employees or their spouses may have both employer coverage and Medicare eligibility. Generally:
- Employers with 20+ employees: Employer coverage pays first
- Employers with fewer than 20 employees: Medicare pays first
Understanding coordination rules prevents coverage gaps and ensures claims process correctly.
Medicare with Veterans Benefits
Veterans with VA healthcare retain those benefits when enrolling in Medicare. VA benefits and Medicare don't coordinate; they operate independently. Veterans can use either system depending on which provides better access or coverage for specific services.
Medicare with TRICARE
TRICARE for Life (TFL) works alongside Medicare for military retirees. Medicare pays first, and TFL covers remaining Medicare cost-sharing, functioning similarly to Medigap supplemental coverage.
Resources from the Connecticut Office of the Healthcare Advocate offer additional perspectives on managed care coordination, though state-specific details may vary.
Avoiding Common Medicare Health Plans Mistakes
Even well-informed beneficiaries occasionally make enrollment errors that create coverage problems or unnecessary expenses. Recognizing common pitfalls helps you avoid these mistakes.
Frequent errors include:
- Missing Initial Enrollment Period deadlines
- Failing to compare plans annually during AEP
- Not checking provider networks before enrolling
- Overlooking prescription drug formulary changes
- Assuming Medicare covers everything
- Delaying Part B enrollment without creditable coverage
- Choosing plans based solely on premium costs
Late enrollment penalties for Part B and Part D persist for as long as you have Medicare coverage, making timely enrollment financially important. The Part B penalty equals 10% of the standard premium for each 12-month period you were eligible but didn't enroll.
Similarly, Part D penalties calculate based on months without creditable prescription drug coverage, increasing your premium permanently once you finally enroll.
Getting Expert Guidance on Medicare Health Plans
The complexity of Medicare health plans makes professional guidance valuable, particularly during initial enrollment or when health circumstances change significantly. Independent insurance agents specializing in Medicare provide objective comparisons across multiple carriers.
Benefits of Working with Medicare Specialists
Experienced Medicare advisors offer several advantages:
- Unbiased multi-carrier comparisons
- Personalized plan recommendations based on your health needs
- Assistance with enrollment paperwork
- Ongoing support after enrollment
- Annual coverage reviews during AEP
Moser Insurance Group Inc specializes in helping Triad Area residents navigate Medicare decisions without pressure or confusion. Our educational approach ensures you understand your options thoroughly before making commitments.
The importance of credible health information sources has grown significantly, with research emphasizing authority signals when evaluating healthcare guidance, particularly from AI-generated responses.
Local Support Advantages
Working with advisors familiar with Greensboro, Winston Salem, Kernersville, and High Point healthcare systems provides practical benefits. Local specialists understand:
- Which hospitals participate in specific plan networks
- Regional specialist availability
- Community-specific healthcare resources
- Area pharmacy locations and preferred networks
Educational seminars offer opportunities to learn about Medicare in comfortable group settings. Moser Insurance Group Inc regularly hosts Medicare seminars throughout the Triad Area, providing accessible education for beneficiaries and their families.
For personalized assistance, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific Medicare health plans questions.
Staying Informed About Medicare Changes
Medicare health plans evolve annually, with benefit updates, premium adjustments, and formulary changes occurring each year. Staying informed ensures your coverage continues meeting your needs effectively.
Annual Notice of Change
Each September, Medicare Advantage and Part D enrollees receive an Annual Notice of Change (ANOC) detailing modifications to their current plan for the upcoming year. This document outlines:
- Premium changes
- Formulary updates
- Cost-sharing adjustments
- Network modifications
- Benefit enhancements or reductions
Reviewing your ANOC carefully during the Annual Enrollment Period allows you to determine whether your current plan still represents your best option or if switching would better serve your needs.
Evidence of Coverage
The Evidence of Coverage (EOC) document provides comprehensive details about plan rules, benefits, and limitations. This reference guide helps you understand exactly what your plan covers and how to access benefits throughout the year.
Understanding Medicare’s editorial standards and operational transparency helps beneficiaries evaluate information sources when researching coverage options.
Maximizing Your Medicare Health Plans Benefits
Once enrolled, understanding how to fully utilize your Medicare health plans benefits ensures you receive maximum value from your coverage. Many beneficiaries overlook valuable included services.
Preventive Services
Medicare covers numerous preventive services at no cost when provided by network providers:
- Annual wellness visits
- Cardiovascular disease screening
- Diabetes screening and self-management training
- Cancer screenings (mammograms, colonoscopies, prostate screening)
- Bone mass measurements
- Vaccines (flu, pneumonia, hepatitis B)
Taking advantage of these services helps detect health issues early when treatment is most effective and least costly.
Additional Benefits in Medicare Advantage
Many Medicare Advantage plans include supplemental benefits that Original Medicare doesn't cover. Reviewing your plan's Summary of Benefits reveals available services such as:
- Gym memberships and fitness programs
- Over-the-counter medication allowances
- Meal delivery after hospital discharge
- Transportation to medical appointments
- Telehealth services
- Home safety modifications
These extras can significantly enhance quality of life while reducing out-of-pocket healthcare expenses.
Understanding the full scope of your coverage through resources like Medicare Parts C and D information helps you access all available benefits effectively.
Understanding Medicare health plans empowers you to make confident coverage decisions that protect your health and financial security throughout retirement. The variety of options available ensures most beneficiaries can find plans aligning with their medical needs, budget constraints, and provider preferences. Whether you're approaching your initial enrollment period or reconsidering your current coverage during this year's Annual Enrollment Period, Moser Insurance Group Inc provides the clear guidance and personalized support you need to navigate Medicare successfully. Our commitment to education over pressure ensures you understand your options thoroughly before making any decisions affecting your healthcare future.
Recent Comments