

Understanding when and how to enroll in Medicare represents one of the most important decisions for Americans approaching retirement age. The medicare enrollment period determines not only when you can access healthcare coverage but also impacts your costs for years to come. Missing key deadlines can result in permanent penalties and gaps in coverage that leave you financially vulnerable during critical health situations. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, navigating these enrollment windows requires careful planning and awareness of the specific timeframes that govern Medicare eligibility. This comprehensive guide breaks down each enrollment period, explains eligibility requirements, and provides actionable steps to ensure you make informed decisions about your healthcare coverage.
Understanding the Initial Enrollment Period
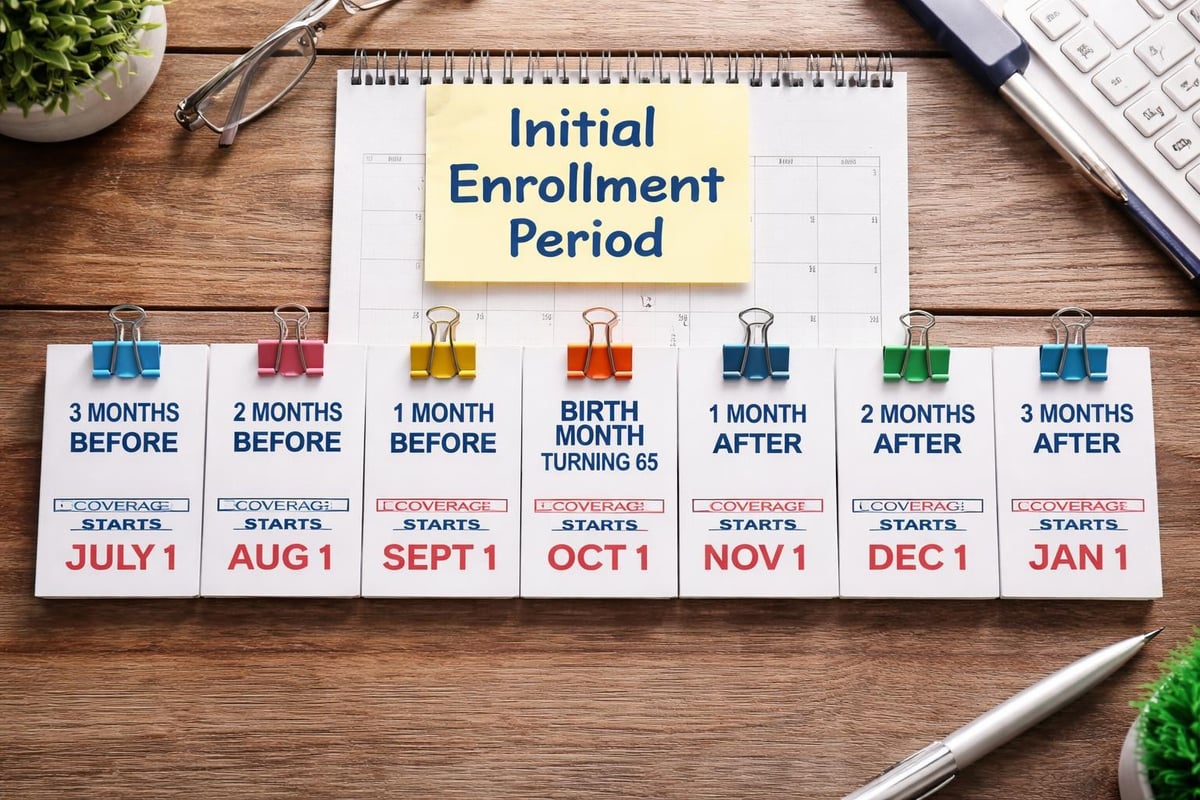
The Initial Enrollment Period serves as your first opportunity to sign up for Medicare and begins three months before the month you turn 65. This seven-month window extends through your birth month and continues for three months afterward, creating a critical timeframe that demands your attention.
The seven-month Initial Enrollment Period includes:
- Three months before your 65th birthday month
- Your actual birthday month
- Three months following your birthday month
This structure provides flexibility while establishing clear boundaries for new enrollees. The Initial Enrollment Period determines when your coverage begins, making timing a strategic consideration rather than a simple administrative task. Enrolling during the first three months ensures coverage starts the month you turn 65, while later enrollment may delay your effective coverage date.
Coverage Start Dates Within the Initial Period
When you enroll significantly impacts when your benefits become active. Signing up during the three months before your birthday month guarantees coverage begins on the first day of your birthday month. This seamless transition proves especially valuable for individuals who plan to retire exactly at age 65.
However, enrollment timing affects more than just start dates. Understanding the 7-month deadline that determines your lifetime Medicare premiums reveals why procrastination carries serious financial consequences. Late enrollment triggers penalties calculated as 10% of the Part B premium for each 12-month period you delayed signing up, and these penalties persist for as long as you maintain Medicare coverage.
The Annual Enrollment Period Explained
The Annual Enrollment Period, often called the medicare enrollment period most people recognize, runs from October 15 through December 7 each year. This window allows current Medicare beneficiaries to review and modify their existing coverage, switching between Original Medicare and Medicare Advantage or changing prescription drug plans.
During this timeframe, you can make several significant changes to your Medicare coverage. The flexibility this period offers addresses the reality that healthcare needs evolve over time, and what worked well last year may not serve you optimally in the coming year.
| Change Type | What You Can Do | Effective Date |
|---|---|---|
| Plan Switching | Move from Original Medicare to Medicare Advantage or vice versa | January 1 |
| Drug Coverage | Add, drop, or switch Part D prescription drug plans | January 1 |
| Advantage Plans | Change from one Medicare Advantage plan to another | January 1 |
The National Council on Aging provides comprehensive details on understanding Medicare enrollment periods, including specific guidelines for the Annual Enrollment Period. For Triad Area residents in Greensboro and surrounding communities, this period represents an opportunity to reassess whether current plan networks still include preferred local providers and whether prescription drug formularies still cover necessary medications at reasonable costs.
Making the Most of Annual Enrollment
Strategic planning during the Annual Enrollment Period requires careful evaluation of several factors. Begin by reviewing your current health status and anticipated medical needs for the upcoming year. Consider scheduled procedures, ongoing treatments, and medication requirements that might influence plan selection.
Network adequacy deserves particular attention. Confirm that specialists you see regularly in High Point, Winston Salem, or Kernersville remain in-network under any plan you're considering. Prescription drug costs warrant equal scrutiny, as formularies change annually and medications may shift between tiers or require different copayments.
Special Enrollment Periods and Qualifying Events
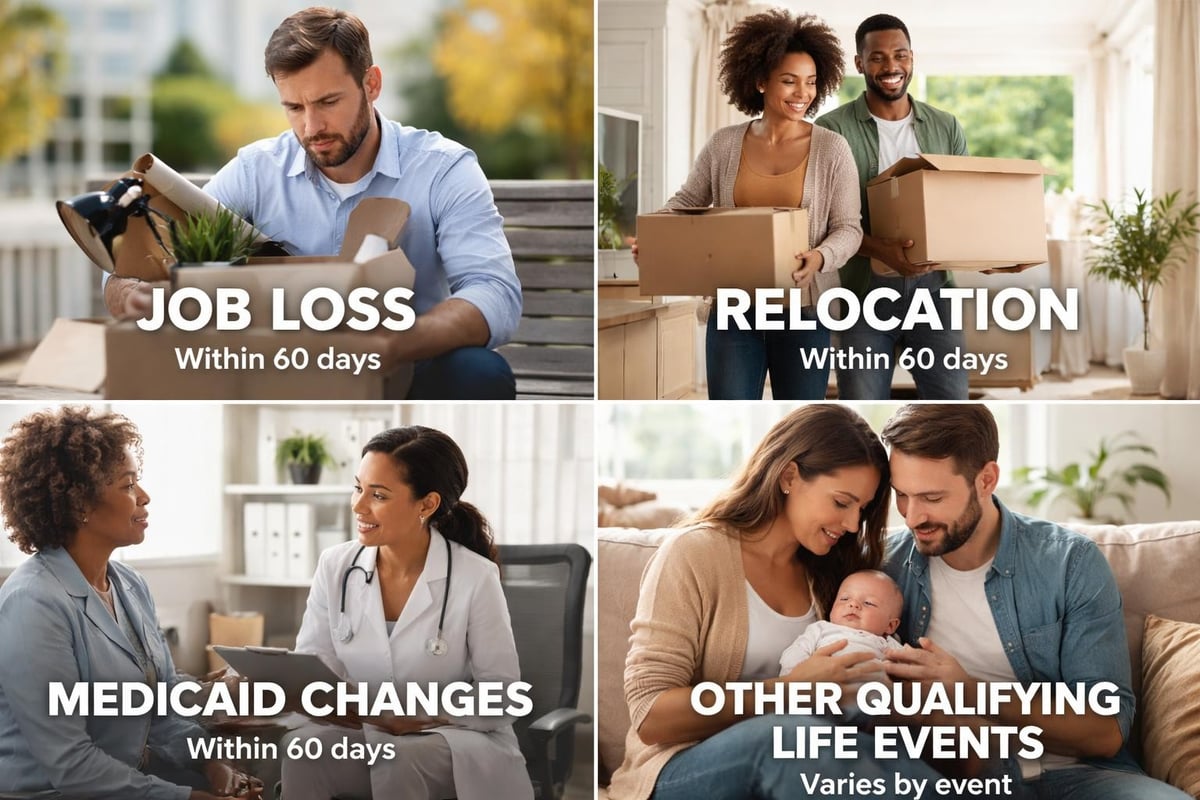
Special Enrollment Periods create opportunities to enroll in or modify Medicare coverage outside the standard timeframes when specific life events occur. These qualifying events recognize that circumstances change unexpectedly and rigid enrollment windows could leave individuals without adequate coverage during transitions.
Common qualifying events include:
- Loss of employer-based health coverage
- Moving outside your current plan's service area
- Loss of Medicaid coverage
- Release from incarceration
- Return from living abroad
- Enrollment in or disenrollment from Programs of All-Inclusive Care for the Elderly (PACE)
New rules for Medicare enrollment periods implemented in recent years expanded access to Special Enrollment Periods and modified effective dates for certain circumstances. These changes generally benefit enrollees by reducing gaps between coverage loss and new coverage activation.
Documenting Your Qualifying Event
When utilizing a Special Enrollment Period, documentation becomes essential. Medicare requires proof of the qualifying event, such as termination letters from employers, moving documentation showing address changes, or official notifications of Medicaid disenrollment.
The timeframe for Special Enrollment Periods varies by qualifying event type. Most situations provide either a two-month or three-month window following the triggering event. Acting promptly ensures you don't miss this limited opportunity to adjust your coverage without waiting for the next Annual Enrollment Period. Residents throughout the Triad Area should contact knowledgeable insurance professionals at 336-862-1763 to verify documentation requirements specific to their situations.
The General Enrollment Period and Late Enrollment Penalties
The General Enrollment Period runs from January 1 through March 31 each year, providing a safety net for individuals who missed their Initial Enrollment Period and don't qualify for a Special Enrollment Period. While this option prevents permanent coverage denial, it comes with significant disadvantages that make it a less-than-ideal fallback.
Coverage obtained during the General Enrollment Period doesn't begin until July 1 of that year, creating a gap that could span several months. More significantly, late enrollment penalties apply and continue indefinitely. The Part A penalty, affecting those who paid Medicare taxes for fewer than 30 quarters, adds 10% to premiums. The Part B penalty increases premiums by 10% for each full 12-month period you could have enrolled but didn't.
Calculating Late Enrollment Penalties
Understanding how penalties accumulate illustrates the importance of timely enrollment during your initial medicare enrollment period. Consider someone who turned 65 in January 2024 but didn't enroll until the General Enrollment Period in 2026. Their Initial Enrollment Period ended in July 2024, meaning approximately 18 months elapsed before enrollment.
This delay triggers a Part B penalty of approximately 20% (two full 12-month periods), applied to the standard premium indefinitely. With the 2026 Part B premium at $185.00 per month, this individual pays an additional $37.00 monthly, totaling $444.00 annually in avoidable costs that persist for life.
Medicare Advantage Open Enrollment Period
The Medicare Advantage Open Enrollment Period represents a distinct opportunity running from January 1 through March 31 annually. This period serves current Medicare Advantage enrollees exclusively, allowing them to switch to different Medicare Advantage plans or return to Original Medicare while adding Part D coverage.
This timeframe addresses situations where individuals enrolled in Medicare Advantage plans during the Annual Enrollment Period discover their new coverage doesn't meet expectations. Perhaps network restrictions prove more limiting than anticipated, or prior authorization requirements create barriers to timely care.
During this period, Medicare Advantage members can:
- Switch to a different Medicare Advantage plan
- Disenroll from Medicare Advantage and return to Original Medicare
- Add a stand-alone Part D prescription drug plan when returning to Original Medicare
- Make only one change during this window
The limitation to a single change during this enrollment period requires careful consideration. For Winston Salem and Greensboro residents evaluating their options, attending Medicare seminars provides valuable insights into plan comparisons and decision-making frameworks that support confident choices.
Employer Coverage and Medicare Enrollment Timing
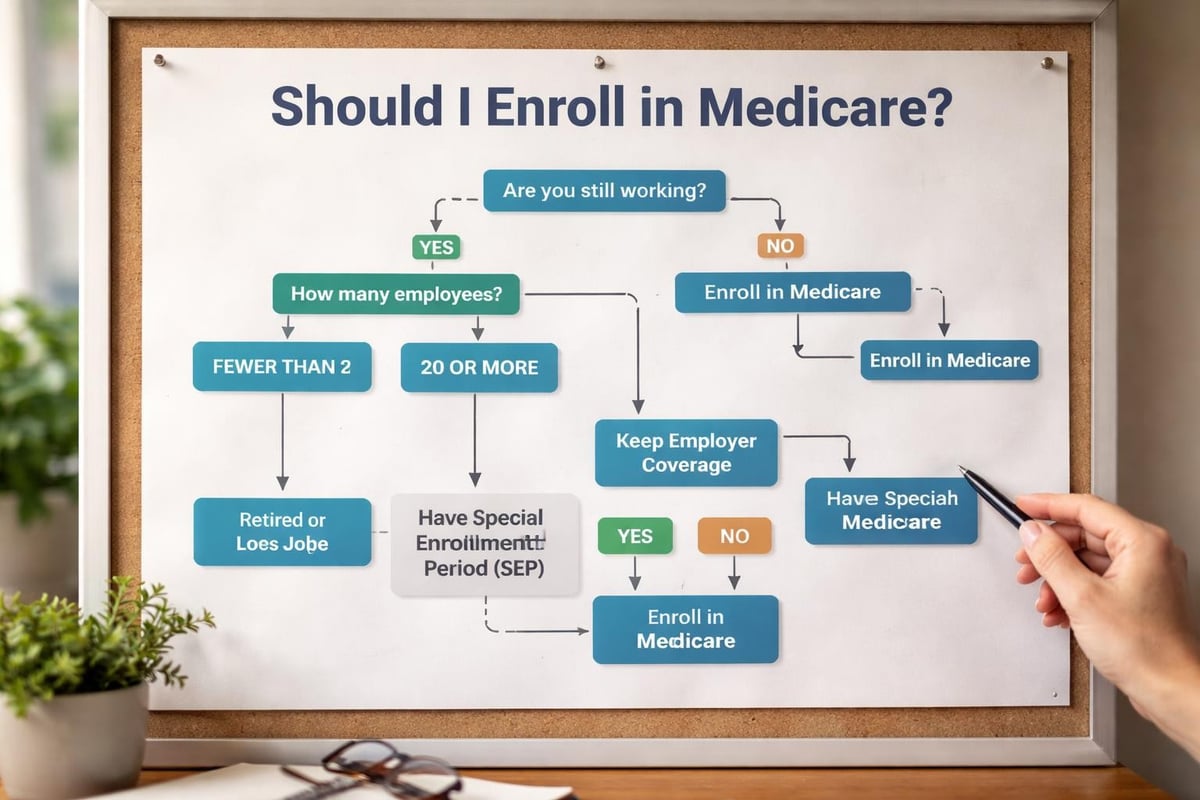
Working past age 65 while maintaining employer-sponsored health insurance complicates medicare enrollment period decisions significantly. The size of your employer determines whether you must enroll in Medicare immediately or can delay without penalty.
Employers with 20 or more employees typically provide primary coverage that allows you to delay Medicare Part B enrollment. Smaller employers often require Medicare to serve as primary insurance, making Part A and Part B enrollment necessary even while working. This distinction carries substantial financial implications, as incorrect decisions trigger late enrollment penalties or coordination of benefits issues.
| Employer Size | Medicare Status | Recommended Action |
|---|---|---|
| 20+ employees | Secondary coverage | May delay Part B enrollment |
| Fewer than 20 | Primary coverage | Should enroll in Parts A and B |
| Retirement | N/A | Enroll within 8 months of coverage loss |
Understanding when Medicare coverage starts relative to employer coverage termination prevents gaps that expose you to full healthcare costs during the transition period. The eight-month Special Enrollment Period following job-based coverage loss provides adequate time to complete enrollment without penalties, assuming you were properly enrolled in Medicare Part A during employment.
Choosing Between Original Medicare and Medicare Advantage
The medicare enrollment period you use to join Medicare also presents the fundamental choice between Original Medicare with supplemental coverage and Medicare Advantage plans. This decision shapes your healthcare experience, costs, and flexibility for years to come.
Original Medicare provides nationwide coverage with freedom to see any provider accepting Medicare. When paired with Medigap supplemental insurance and Part D prescription drug coverage, it offers comprehensive protection with predictable costs. However, this combination typically involves multiple premiums and doesn't include extra benefits like dental or vision coverage.
Medicare Advantage plans bundle hospital, medical, and usually prescription drug coverage into single plans offered by private insurers. Many include dental, vision, and hearing benefits at lower monthly premiums than Original Medicare with supplements. The tradeoff involves network restrictions, prior authorization requirements, and annual out-of-pocket maximums that can reach several thousand dollars.
Evaluating Plans for Your Specific Needs
Personal circumstances should drive your coverage decision. Consider your current health status, preferred providers, prescription medications, and budget constraints. Individuals with complex medical conditions often value Original Medicare's provider flexibility and predictable Medigap coverage, while healthy individuals might prefer Medicare Advantage plans' lower premiums and additional benefits.
Geographic location influences this choice significantly. The Triad Area, including communities like Kernersville and High Point, features robust provider networks for most Medicare Advantage plans, but rural areas sometimes offer limited options. Reviewing plan availability at moserinsurancegroup.com helps Triad residents identify coverage options specific to their zip codes and evaluate network adequacy for their preferred healthcare facilities.
Special Considerations for End-Stage Renal Disease
End-Stage Renal Disease (ESRD) creates unique enrollment considerations within the medicare enrollment period framework. Historically, individuals with ESRD faced restrictions preventing Medicare Advantage enrollment, limiting them to Original Medicare regardless of preferences or cost considerations.
Recent regulatory changes now permit Medicare Advantage enrollment for people with ESRD during standard enrollment periods. This expansion provides access to integrated coverage and potentially lower costs, though careful plan evaluation remains essential given the complex care requirements ESRD entails.
Dialysis center networks and specialist availability should guide plan selection for ESRD patients. Confirm that facilities convenient to your location in Greensboro or surrounding areas participate in any Medicare Advantage plan you consider, and verify that nephrologists and transplant centers remain accessible under plan terms.
State Pharmaceutical Assistance Programs and Medicare
North Carolina residents should explore state pharmaceutical assistance programs that work alongside Medicare Part D coverage to reduce prescription costs. These programs, though not directly related to the medicare enrollment period itself, become accessible once Medicare enrollment occurs and can substantially impact out-of-pocket medication expenses.
The North Carolina AIDS Drug Assistance Program (ADAP), SeniorCare program, and manufacturer patient assistance programs provide additional resources for eligible individuals. Coordinating these benefits with Part D coverage requires understanding how programs interact and which pays primary versus secondary for covered medications.
Enrollment in these supplemental programs often occurs separately from Medicare enrollment but may require Medicare eligibility as a prerequisite. Timing your Medicare enrollment appropriately ensures seamless access to all available assistance programs without gaps that could leave you paying full price for necessary medications.
Disability-Based Medicare Enrollment
Individuals under 65 who receive Social Security Disability Insurance (SSDI) payments for 24 months automatically qualify for Medicare, creating a disability-based enrollment pathway separate from age-based eligibility. This medicare enrollment period begins automatically, with Medicare coverage starting the 25th month of disability benefit receipt.
The automatic enrollment simplifies the process but requires awareness of coverage start dates and the option to decline Part B if you maintain other coverage. Disability beneficiaries can also purchase Medigap policies during a six-month Medigap Open Enrollment Period beginning when they first enroll in Part B, regardless of age or health status.
Understanding Medicare age requirements helps disability beneficiaries recognize how their coverage transitions when they reach 65 and whether any plan changes become advantageous at that milestone. The complexity of disability-based Medicare enrollment often benefits from professional guidance to optimize coverage and minimize costs throughout the process.
Medicaid and Medicare Dual Eligibility
Dual-eligible individuals who qualify for both Medicare and Medicaid navigate special enrollment rules and access unique plan options designed for their circumstances. The medicare enrollment period for dual-eligibles includes Special Enrollment Periods that permit monthly plan changes, providing flexibility unavailable to other Medicare beneficiaries.
Dual Special Needs Plans (D-SNPs) serve this population exclusively, coordinating Medicare and Medicaid benefits while addressing social determinants of health that impact dual-eligible individuals disproportionately. These plans often include transportation assistance, care coordination, and supplemental benefits targeting the specific needs of low-income seniors and disabled individuals.
Monthly Special Enrollment Periods allow dual-eligibles to switch D-SNPs or move between D-SNPs and other Medicare coverage options throughout the year. This ongoing flexibility recognizes that dual-eligible individuals often experience life changes requiring coverage adjustments more frequently than the general Medicare population. Residents in the Triad Area seeking guidance on dual-eligible options can email moserinsurancegroup@gmail.com for personalized assistance evaluating available plans and enrollment strategies.
Planning Ahead for Medicare Enrollment Success
Successful Medicare enrollment begins months before your actual medicare enrollment period arrives. Gathering necessary information, understanding your options, and making informed decisions requires time and often benefits from expert guidance that clarifies complex choices and prevents costly mistakes.
Key preparation steps include:
- Determining your Initial Enrollment Period dates
- Evaluating whether you'll continue working past 65
- Reviewing current prescription medications and healthcare providers
- Comparing Original Medicare versus Medicare Advantage options
- Understanding supplemental coverage needs and Medigap policy options
- Calculating estimated costs for different coverage combinations
Starting this process six months before turning 65 provides adequate time for thorough research without last-minute pressure. The decision you make during your enrollment period affects your healthcare access, costs, and satisfaction for years to come, making informed preparation a worthwhile investment of time and attention.
Resources like AARP’s guide to Medicare enrollment periods offer objective information about timeframes and requirements, while local Medicare insurance professionals provide personalized guidance accounting for your specific health needs, budget, and preferences. Combining educational resources with professional consultation creates a comprehensive understanding that supports confident decision-making.
Understanding the medicare enrollment period options available to you prevents penalties, coverage gaps, and unnecessary costs that burden your retirement budget for years to come. Whether you're approaching your Initial Enrollment Period, evaluating changes during Annual Enrollment, or qualifying for a Special Enrollment Period, informed decisions protect both your health and financial wellbeing. Moser Insurance Group Inc serves individuals and families throughout Greensboro, Kernersville, High Point, Winston Salem, and the broader Triad Area with clear guidance and personalized support to navigate Medicare enrollment confidently. Contact us at 336-862-1763 or visit Moser Insurance Group Inc to discuss your Medicare options and ensure you make the right enrollment choices for your unique circumstances.
Recent Comments