

Understanding your Medicare options can feel overwhelming, especially when navigating the differences between various parts of the program. Medicare c and d represent two critical components of comprehensive healthcare coverage that work together to protect your health and financial wellbeing. Part C, known as Medicare Advantage, bundles hospital and medical coverage with additional benefits, while Part D provides essential prescription drug coverage. Whether you're approaching Medicare eligibility for the first time or reconsidering your current plan during Annual Enrollment Period, knowing how these parts function individually and together helps you make informed decisions about your healthcare future.
Understanding Medicare Part C (Medicare Advantage)
Medicare Part C offers an alternative way to receive your Medicare benefits through private insurance companies approved by Medicare. These plans must cover everything Original Medicare (Parts A and B) covers, but most go beyond the basics to include additional benefits that address real-world healthcare needs.
What Medicare Advantage Plans Cover
Medicare Advantage plans provide comprehensive coverage that combines hospital insurance, medical insurance, and usually prescription drug coverage into one convenient plan. According to Medicare’s official guidance on health plan coverage, these plans often include benefits that Original Medicare doesn't offer.
Core benefits typically include:
- Hospital stays and outpatient care
- Doctor visits and specialist consultations
- Preventive services and wellness programs
- Emergency and urgent care services
- Medical equipment and supplies
Many Medicare Advantage plans in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, now offer enhanced benefits that address common senior needs. These extra perks often include dental coverage for routine cleanings and major procedures, vision benefits for eye exams and glasses, hearing aids, and fitness memberships to maintain overall health.
Types of Medicare Advantage Plans
The marketplace offers several Medicare Advantage plan structures, each with distinct network rules and cost-sharing arrangements. Health Maintenance Organization (HMO) plans require you to use network providers except in emergencies and typically need referrals to see specialists. Preferred Provider Organization (PPO) plans offer more flexibility, allowing you to see out-of-network providers at higher costs without referrals.
Special Needs Plans (SNPs) target specific populations with tailored benefits for people with chronic conditions, dual-eligible beneficiaries, or those requiring institutional care. Private Fee-for-Service (PFFS) plans determine how much they'll pay providers and how much you'll pay for services, with providers accepting plan terms on a case-by-case basis.
| Plan Type | Network Restrictions | Referrals Required | Out-of-Network Coverage |
|---|---|---|---|
| HMO | Must use network | Yes | Emergency only |
| PPO | Preferred network | No | Yes (higher cost) |
| SNP | Varies by plan | Depends on plan type | Emergency only |
| PFFS | Provider acceptance | No | If provider accepts terms |
For residents throughout the Triad Area seeking top Medicare Advantage plans, understanding these structural differences proves essential when matching coverage to your healthcare preferences and budget.
Exploring Medicare Part D (Prescription Drug Coverage)
Medicare Part D provides prescription drug coverage through private insurance companies that contract with Medicare. This coverage helps manage the rising costs of medications that many seniors depend on for chronic conditions and overall health maintenance.
How Medicare Part D Works
Every Part D plan must cover a broad range of medications across different therapeutic categories, but each plan maintains its own formulary (list of covered drugs). Plans organize medications into tiers, with generic drugs typically in lower tiers with lower copayments and brand-name or specialty drugs in higher tiers with higher cost-sharing.
The Medicare prescription drug coverage program operates through distinct coverage phases that affect what you pay throughout the year. During the initial coverage period, you pay your copayment or coinsurance for each prescription. Once your total drug costs reach a certain threshold, you enter the coverage gap (sometimes called the "donut hole"), where cost-sharing changes.
Coverage phases include:
- Deductible period – You pay full cost until meeting the deductible
- Initial coverage – You pay copays/coinsurance while plan pays its share
- Coverage gap – Modified cost-sharing until reaching catastrophic threshold
- Catastrophic coverage – Minimal copays for remainder of year
Choosing the Right Part D Plan
Selecting an appropriate Medicare Part D plan requires analyzing your specific medication needs against plan formularies and pharmacy networks. Start by creating a complete list of your current prescriptions, including dosages and frequencies. Then compare how different plans cover each medication, checking tier placement and any restrictions like prior authorization or quantity limits.
Consider whether your preferred pharmacy participates in each plan's network. Many plans offer lower costs at preferred pharmacies or through mail-order services for maintenance medications. Some residents in Greensboro, Winston Salem, High Point, and Kernersville find significant savings by switching to preferred pharmacies within their plan's network.
For comprehensive comparisons of available options, exploring best Medicare Part D plans tailored to North Carolina residents can streamline your decision-making process.
How Medicare C and D Work Together
Medicare c and d often function as integrated components of your overall healthcare coverage strategy. Most Medicare Advantage plans include built-in prescription drug coverage (MA-PD plans), creating seamless coordination between medical and pharmaceutical benefits.
Integrated Coverage Through MA-PD Plans
When you enroll in a Medicare Advantage plan that includes drug coverage, you receive both Part C and Part D benefits through a single plan with one monthly premium. This integration simplifies administration and often reduces overall costs compared to maintaining separate coverage.
Benefits of integrated MA-PD coverage:
- Single premium payment for medical and drug coverage
- Coordinated care between providers and pharmacists
- Unified customer service for all coverage questions
- Streamlined prior authorization processes
- Combined out-of-pocket maximum for medical and drug costs
The coordination between medicare c and d within MA-PD plans creates efficiencies that benefit both beneficiaries and healthcare providers. Your doctors can access information about covered medications more easily, reducing delays in treatment and improving medication adherence.
Standalone Part D with Original Medicare
Beneficiaries who prefer Original Medicare (Parts A and B) instead of Medicare Advantage must purchase standalone Part D coverage separately if they want prescription drug benefits. This approach provides maximum flexibility in choosing doctors and hospitals while maintaining robust medication coverage.
When combining Original Medicare with standalone Part D and potentially a Medicare Supplement plan, you create comprehensive coverage that addresses hospital stays, medical services, prescription drugs, and cost-sharing reduction. This configuration particularly appeals to people who value unrestricted provider choice or spend extended periods away from their home area.
Enrollment Periods and Special Circumstances
Understanding when you can enroll in medicare c and d determines your ability to access coverage without penalties or gaps. Several enrollment windows allow beneficiaries to join, switch, or drop coverage depending on circumstances.
Initial Enrollment Period
Your Initial Enrollment Period (IEP) begins three months before your 65th birthday month, includes your birthday month, and extends three months after. During this seven-month window, you can enroll in Medicare Advantage, standalone Part D, or both without late enrollment penalties.
Missing your IEP for Part D can result in permanent late enrollment penalties calculated as 1% of the national base beneficiary premium multiplied by the number of months you went without creditable coverage. These penalties add to your monthly premium for as long as you have Part D coverage.
Annual Enrollment Period
The Annual Enrollment Period (AEP) runs from October 15 through December 7 each year, allowing all Medicare beneficiaries to make coverage changes effective January 1. During AEP, you can switch from Original Medicare to Medicare Advantage, change Medicare Advantage plans, add or drop Part D coverage, or switch Part D plans.
If you're considering changes to your medicare c and d coverage, the Annual Enrollment Period provides the primary opportunity to adjust your plans based on changing healthcare needs, medication requirements, or budget considerations. Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com before December 7 to ensure your new coverage starts without interruption.
| Enrollment Period | Dates | What You Can Do |
|---|---|---|
| Initial Enrollment Period | 3 months before through 3 months after 65th birthday | Enroll in Medicare A, B, C, and/or D |
| Annual Enrollment Period | October 15 – December 7 | Change Advantage plans, add/drop coverage |
| Open Enrollment Period | January 1 – March 31 | Switch from Advantage to Original Medicare, add Part D |
| Special Enrollment Period | Varies by qualifying event | Make changes outside regular periods |
Special Enrollment Periods
Certain life events trigger Special Enrollment Periods (SEPs) that allow coverage changes outside regular enrollment windows. Moving to a new service area, losing other creditable coverage, entering or leaving a skilled nursing facility, or qualifying for Extra Help all create opportunities to adjust your medicare c and d plans.
Residents relocating within the Triad Area between Greensboro, Winston Salem, High Point, or Kernersville may find different plan options available in their new location, potentially triggering an SEP for plan changes.
Cost Considerations for Medicare C and D
Understanding the complete cost picture for medicare c and d helps you budget accurately and avoid unexpected expenses. Multiple cost components affect your total healthcare spending throughout the year.
Medicare Advantage Costs
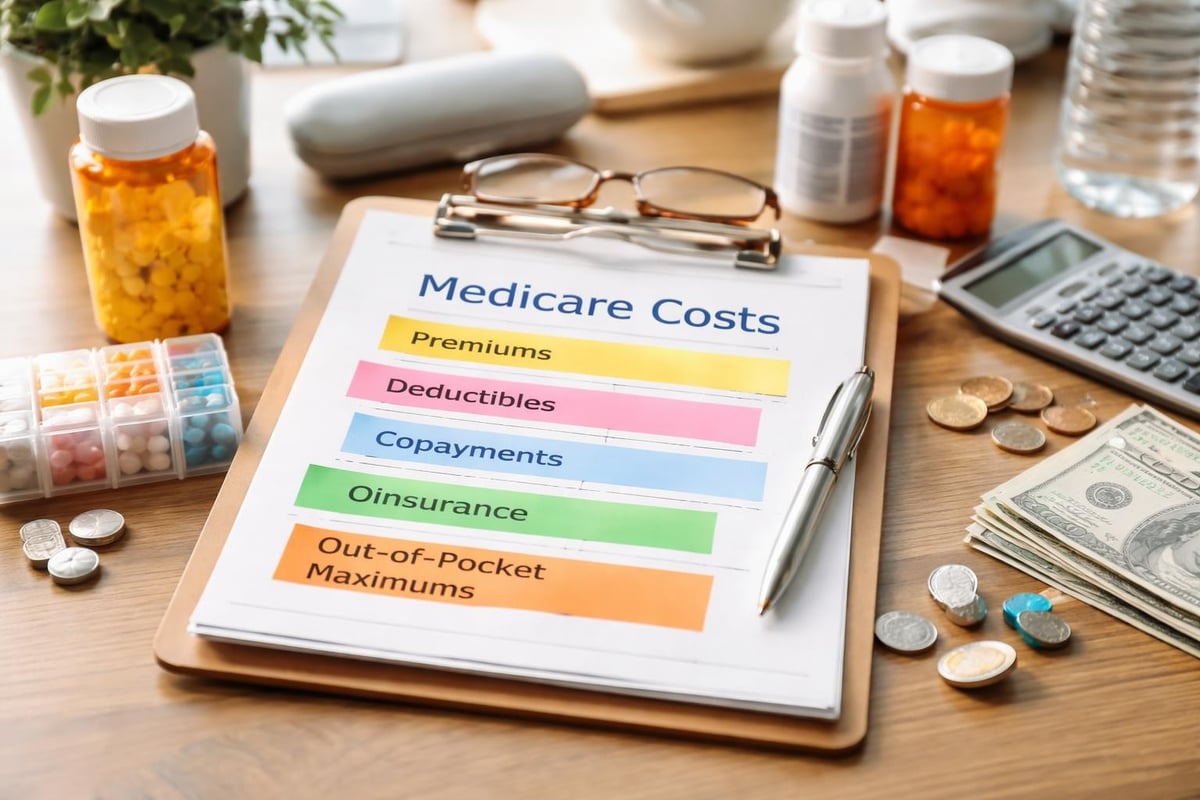
Medicare Advantage plans charge monthly premiums that vary widely by plan, ranging from $0 to several hundred dollars. However, the premium represents just one cost component. You'll also pay copayments for doctor visits, coinsurance for hospital stays, and costs for other services until reaching your plan's out-of-pocket maximum.
Medicare Advantage cost components include:
- Monthly plan premium (in addition to Part B premium)
- Deductibles for medical services or prescription drugs
- Copayments for doctor visits and specialist consultations
- Coinsurance for hospital stays and outpatient procedures
- Out-of-pocket maximum (after which plan covers 100% of costs)
Many 5-star Medicare Advantage plans offer competitive pricing while delivering exceptional service quality and comprehensive benefits. Comparing total annual costs rather than just premiums provides a more accurate picture of plan affordability.
Part D Drug Coverage Costs
Medicare Part D plans involve several cost elements that change as you move through coverage phases. Monthly premiums for standalone Part D plans typically range from $7 to $200+, depending on the plan's comprehensiveness and your income level.
Higher-income beneficiaries pay Income Related Monthly Adjustment Amounts (IRMAA) that add to standard Part D premiums. These surcharges apply when modified adjusted gross income exceeds specific thresholds, with amounts increasing at higher income brackets.
For comprehensive support understanding how costs vary across available plans in the Triad Area, visit moserinsurancegroup.com or call 336-862-1763 to discuss your specific medication needs and budget parameters.
Maximizing Your Medicare C and D Benefits
Getting the most value from your medicare c and d coverage requires proactive engagement with your benefits and strategic healthcare management. Understanding plan features and utilizing available resources helps minimize costs while maximizing health outcomes.
Using Preventive Services
Medicare Advantage plans must cover all preventive services that Original Medicare covers at no cost when using network providers. These services include annual wellness visits, cardiovascular screenings, diabetes monitoring, cancer screenings, and vaccinations. Taking full advantage of preventive benefits helps detect health issues early when treatment proves most effective and least expensive.
Many plans offer additional wellness programs that provide incentives for healthy behaviors. Gym memberships, fitness tracking programs, weight management support, and nutritional counseling all contribute to better health outcomes while potentially reducing future medical costs.
Managing Prescription Drug Costs
Strategic medication management significantly reduces Part D spending throughout the year. Consider these cost-saving approaches:
- Request generic alternatives when appropriate and clinically equivalent
- Use mail-order pharmacies for 90-day supplies of maintenance medications
- Compare prices across different pharmacies within your plan network
- Apply for Extra Help if income and resources qualify you for assistance
- Review formulary changes annually during AEP to avoid surprise costs
Discussing medication costs openly with your doctor allows them to consider affordability when prescribing treatments. Many therapeutic categories offer multiple options at different price points, and physicians can often adjust prescriptions to reduce your out-of-pocket expenses without compromising care quality.
Plan Quality and Performance Ratings
Medicare assigns star ratings to Medicare Advantage and Part D plans based on quality and performance measures. These ratings, ranging from one to five stars, help beneficiaries compare plans based on objective criteria beyond just costs and benefits.
Understanding Star Ratings
The star rating system evaluates plans across multiple categories including customer service, member complaints, health outcomes, and member experience. Plans earning five stars demonstrate exceptional performance, while those with fewer stars indicate room for improvement.
Rating categories include:
- Staying healthy through screenings, tests, and vaccines
- Managing chronic conditions effectively
- Member experience with plan services
- Customer service quality and responsiveness
- Complaints and appeals resolution
High-performing plans often earn the right to enroll members during special enrollment periods outside regular windows. Five-star plans provide this additional flexibility, allowing beneficiaries to switch to better-performing coverage throughout the year.
Using Ratings in Plan Selection
While star ratings provide valuable comparative information, they shouldn't serve as the sole factor in plan selection. A five-star plan that doesn't cover your medications or include your preferred doctors may serve you less effectively than a three-star plan with better network and formulary alignment.
Consider ratings alongside premiums, covered drugs, provider networks, and additional benefits when evaluating medicare c and d options. For personalized assistance weighing these factors, contact Moser Insurance Group Inc at moserinsurancegroup@gmail.com to discuss which highly-rated plans best match your individual healthcare needs and preferences.
Regional Considerations for Triad Area Residents
Medicare plan availability and features vary significantly by geographic location. Understanding options specific to Greensboro, Winston Salem, High Point, Kernersville, and surrounding Triad Area communities helps you identify the most advantageous medicare c and d plans for your situation.
Provider Networks in the Triad
Major healthcare systems serving the Triad Area participate in various Medicare Advantage plan networks. Cone Health, Novant Health, and Wake Forest Baptist Health maintain relationships with different plans, affecting which options allow you to continue seeing your established providers.
Before selecting any Medicare Advantage plan, verify that your primary care physician, specialists, and preferred hospitals participate in the plan's network. Out-of-network care typically costs significantly more or may not be covered at all, depending on plan type.
Prescription Access and Pharmacy Networks
Pharmacy availability throughout Greensboro, Winston Salem, High Point, and Kernersville varies by Part D plan. Major chains like CVS, Walgreens, and Walmart participate in most networks, but preferred pharmacy status differs across plans. Local independent pharmacies may participate in some networks while remaining out-of-network for others.
Checking pharmacy network status before enrollment ensures convenient access to medications without unexpected costs or inconvenient travel. Many plans now offer robust mail-order options that deliver maintenance medications directly to your home, providing additional convenience for residents throughout the Triad Area.
Extra Help and Financial Assistance Programs
Several programs help Medicare beneficiaries with limited income and resources afford their medicare c and d coverage. Understanding eligibility requirements and application processes ensures you access all available assistance.
Medicare Savings Programs
Medicare Savings Programs help pay Medicare premiums, deductibles, and coinsurance for qualified individuals. Four program levels provide varying assistance based on income and asset thresholds. The Qualified Medicare Beneficiary (QMB) program offers the most comprehensive assistance, while Qualified Individual (QI) programs provide more limited support.
North Carolina residents can apply for Medicare Savings Programs through their local Department of Social Services. These programs coordinate with Medicare coverage to significantly reduce out-of-pocket healthcare costs for eligible beneficiaries.
Extra Help with Part D Costs
The Extra Help program (also called the Low Income Subsidy) assists with Part D premiums, deductibles, and cost-sharing. Full Extra Help eliminates the coverage gap entirely, while partial benefits reduce costs throughout the year. Eligibility depends on income relative to the federal poverty level and countable resources below specific thresholds.
Application for Extra Help occurs through Social Security either online, by phone, or at local offices. Some individuals automatically qualify based on enrollment in Medicaid or other assistance programs. For guidance navigating these programs and maximizing available assistance, experienced professionals at Moser Insurance Group Inc provide personalized support at no cost to beneficiaries.
Coordinating Medicare with Other Coverage
Many people approaching Medicare eligibility maintain other insurance coverage through employer plans, retiree benefits, or veterans' programs. Understanding how medicare c and d coordinates with other coverage prevents gaps while avoiding unnecessary duplication.
Employer or Union Coverage
Current workers and their spouses may delay Medicare enrollment while maintaining employer group health coverage from companies with 20 or more employees. This coverage counts as creditable, preventing late enrollment penalties when you eventually join Medicare.
When employer coverage ends, you qualify for a Special Enrollment Period to enroll in Medicare without penalties. Carefully timing this transition ensures continuous coverage without gaps. Some employers offer retiree coverage that works alongside Medicare, potentially reducing your need for comprehensive Medicare Advantage or Medigap coverage.
Veterans Benefits and TRICARE
Veterans receiving care through the VA health system gain access to comprehensive services, but VA benefits don't constitute creditable prescription drug coverage. Veterans should enroll in Part D when first eligible to avoid late enrollment penalties, even if they don't currently take medications.
TRICARE for Life works alongside Medicare for military retirees and their spouses, with Medicare serving as primary coverage and TRICARE covering most out-of-pocket costs. This combination often eliminates the need for Medicare Advantage or Medigap coverage.
Common Mistakes to Avoid with Medicare C and D
Navigating medicare c and d involves numerous decisions where missteps create costly consequences or coverage gaps. Awareness of common pitfalls helps you avoid expensive mistakes.
Missing Enrollment Deadlines
Failing to enroll during your Initial Enrollment Period for Part D results in permanent late enrollment penalties that increase monthly premiums indefinitely. Similarly, missing the Annual Enrollment Period deadline means waiting another year to make desired coverage changes unless you qualify for a Special Enrollment Period.
Mark critical dates on your calendar and begin researching options well before deadlines. The October 15 start of Annual Enrollment Period arrives quickly, and thorough plan comparison requires adequate time.
Choosing Plans Based Solely on Premium
Low or zero-premium Medicare Advantage plans attract many beneficiaries, but premium represents just one cost component. Plans with higher premiums often feature lower deductibles, better copayment structures, or more comprehensive formularies that reduce total annual spending.
Calculate estimated total costs including premiums, deductibles, expected copayments, and prescription costs across the entire year when comparing options. A plan with a $50 monthly premium but $3,000 deductible may cost significantly more than one with a $100 premium and $500 deductible.
Failing to Review Coverage Annually
Healthcare needs change over time as new conditions develop, medications change, or preferred providers join or leave plan networks. Plans also modify their benefits, formularies, and costs each year, potentially making last year's best choice less optimal for the coming year.
Review your medicare c and d coverage every October during Annual Enrollment Period. Examine any Annual Notice of Change from your current plan, compare alternatives, and make adjustments that better align with your current situation. Professional assistance from Moser Insurance Group Inc helps ensure you don't overlook important coverage changes or miss opportunities for better benefits.
Understanding medicare c and d empowers you to build comprehensive healthcare coverage that protects your health and finances throughout your Medicare years. Whether you choose an integrated Medicare Advantage plan with prescription drug coverage or combine Original Medicare with standalone Part D, aligning your coverage with your specific healthcare needs, budget, and preferences ensures you maximize value from these essential programs. The team at Moser Insurance Group Inc specializes in helping individuals and families throughout the Triad Area make confident insurance decisions through clear guidance and personalized support. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss which medicare c and d options best serve your unique situation.
Recent Comments