

Understanding when you become eligible for Medicare and what steps to take is one of the most important healthcare decisions you'll make in your lifetime. The medicare age threshold represents a critical milestone that affects not only your healthcare coverage but also your financial planning for retirement. Whether you're approaching 65 in Greensboro, Kernersville, High Point, Winston Salem, or anywhere in the Triad Area, knowing the rules and deadlines can save you from costly mistakes and coverage gaps.
The Standard Medicare Age Explained
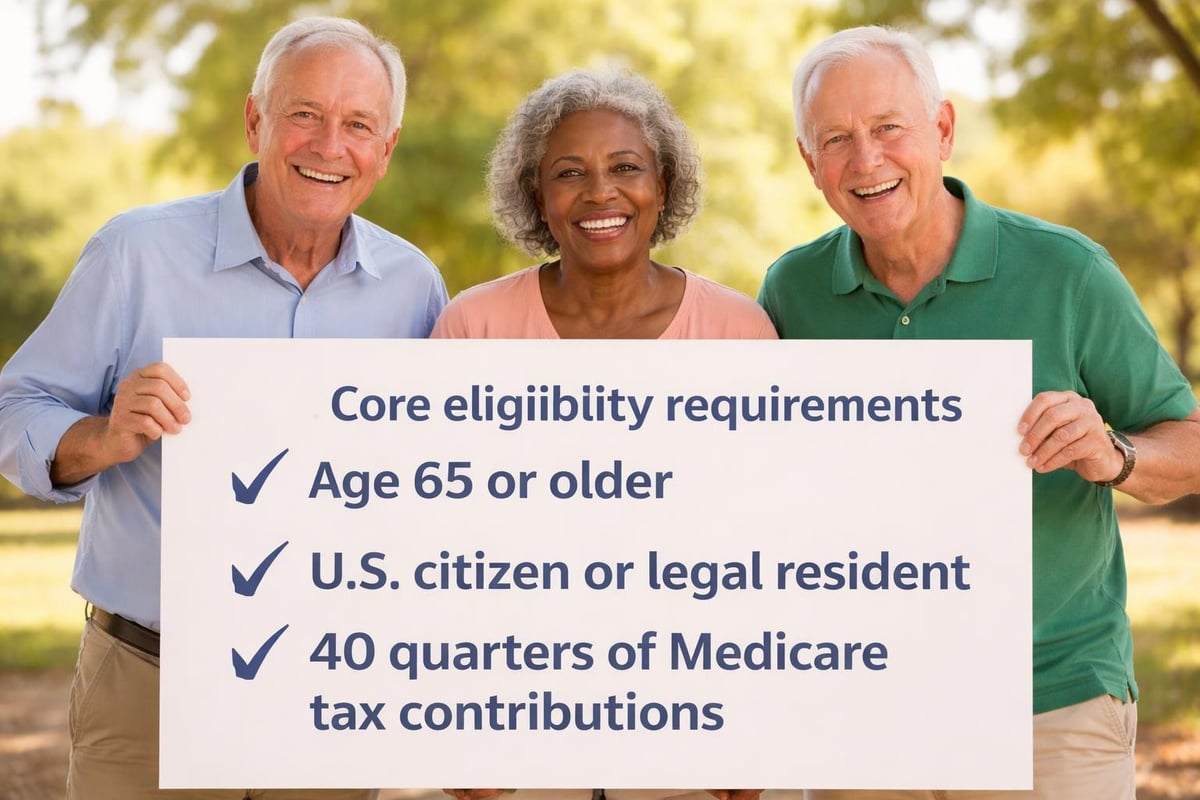
The standard medicare age is 65 years old. This has been the benchmark since Medicare was established in 1965, and it remains the primary eligibility criterion for most Americans. When you turn 65, you become eligible for Medicare Part A (hospital insurance) and Part B (medical insurance), regardless of whether you're still working or have already retired.
However, eligibility involves more than just reaching the right age. You must also be a U.S. citizen or a legal resident who has lived in the United States continuously for at least five years. Additionally, you or your spouse must have worked and paid Medicare taxes for at least 10 years (40 quarters) to qualify for premium-free Part A coverage.
When Age Isn't the Only Factor
While 65 is the standard medicare age, certain circumstances allow for earlier enrollment:
- Disability status: If you've been receiving Social Security Disability Insurance (SSDI) benefits for 24 months, you automatically qualify for Medicare, regardless of your age.
- End-Stage Renal Disease (ESRD): Individuals with permanent kidney failure requiring dialysis or a transplant can enroll at any age.
- Amyotrophic Lateral Sclerosis (ALS): Medicare coverage begins immediately upon receiving SSDI benefits for ALS, with no waiting period.
These exceptions ensure that vulnerable populations receive coverage when they need it most, not just when they reach the traditional medicare age milestone.
Understanding Your Initial Enrollment Period
The Initial Enrollment Period is a seven-month window surrounding your 65th birthday, and missing it can have serious financial consequences. This period includes:
- The three months before your birth month
- Your birth month
- The three months after your birth month
Important timing consideration: If your birthday falls on the first day of the month, your Initial Enrollment Period actually begins four months before your birth month. This detail matters because your coverage start date depends on when you enroll during this window.
| Enrollment Month | Part A Start Date | Part B Start Date |
|---|---|---|
| 3 months before birth month | First day of birth month | First day of birth month |
| Birth month | First day of following month | First day of following month |
| Month after birth month | First day of month after enrollment | First day of month after enrollment |
| 2-3 months after birth month | Two months after enrollment | Two months after enrollment |
Understanding when Medicare open enrollment occurs helps you plan beyond just your initial signup.
Coordinating Medicare Age with Social Security
Many people assume that reaching medicare age and claiming Social Security benefits happen simultaneously, but these are separate decisions with different optimal timing strategies. Your Full Retirement Age for Social Security might be 66, 67, or somewhere in between, depending on your birth year.
You can claim Social Security as early as age 62, but doing so reduces your monthly benefit permanently. Conversely, you can delay Social Security until age 70 to maximize your monthly payments. Medicare, however, doesn't offer the same flexibility. Delaying enrollment past your Initial Enrollment Period without creditable coverage leads to penalties, not increased benefits.
Automatic Enrollment Scenarios
If you're already receiving Social Security benefits when you turn 65, you'll be automatically enrolled in Medicare Parts A and B. You'll receive your Medicare card in the mail about three months before your 65th birthday. This automatic enrollment ensures you don't miss critical deadlines.
However, if you're still working and have employer-based coverage, you might want to decline Part B to avoid paying premiums for duplicate coverage. You can do this by following the instructions that come with your Medicare card.
The upcoming changes to Social Security in 2026 may affect how you coordinate these benefits, making it essential to review your strategy annually.
Working Past Medicare Age
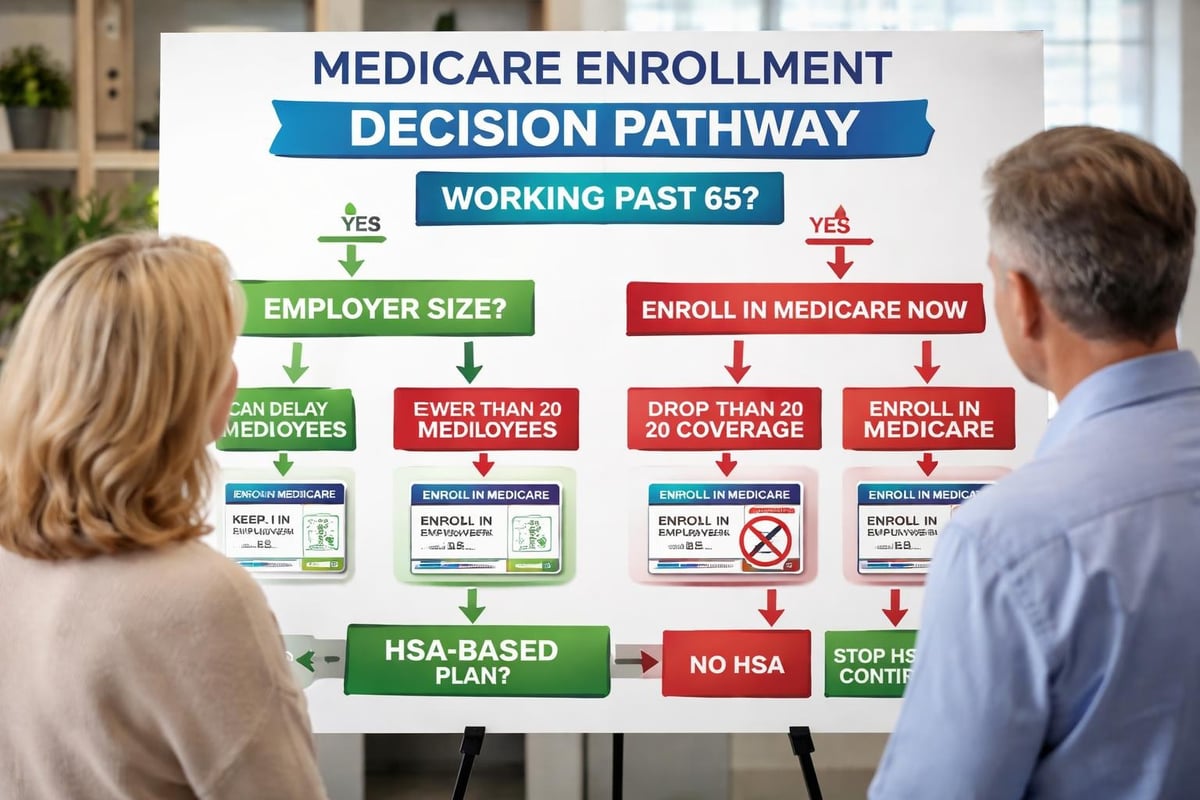
Continuing to work past the traditional medicare age is increasingly common, and it significantly impacts your Medicare enrollment decisions. Your employer size and the type of coverage you have determine whether you should enroll in Medicare immediately or delay enrollment.
Large Employer Coverage (20+ Employees)
If your employer has 20 or more employees, your employer health plan is primary, and Medicare becomes secondary. In this situation:
- You can delay enrolling in Part B without penalty
- You should still enroll in Part A if it's premium-free
- You qualify for a Special Enrollment Period when your employment or coverage ends
- You have eight months after employment ends to enroll without penalty
Small Employer Coverage (Fewer Than 20 Employees)
When your employer has fewer than 20 employees, Medicare becomes the primary payer. You should enroll in both Part A and Part B at medicare age to avoid coverage gaps. Your employer plan will coordinate with Medicare as the secondary payer.
Critical consideration for the Triad Area: If you're working for a smaller business in Greensboro, Winston Salem, High Point, or Kernersville, understanding these rules prevents unexpected medical bills. Contact Moser Insurance Group Inc at 336-862-1763 to discuss your specific employment situation.
Medicare Age and Spouse Coverage
Reaching medicare age when you have a spouse creates additional planning considerations, especially if there's an age gap between you. The younger spouse cannot enroll in Medicare through their older partner's eligibility-each person must qualify individually based on their own age or disability status.
COBRA and spouse coverage: If you've been covered under your spouse's employer plan and that coverage ends when they retire at medicare age, you have 63 days to enroll in Medicare under a Special Enrollment Period. Alternatively, you could elect COBRA, but this is typically more expensive than Medicare and doesn't extend the special enrollment window.
Key scenarios for married couples:
- Both spouses turning 65 in the same year: Coordinate enrollment to ensure continuous coverage and avoid overlapping premiums
- Significant age gap: The younger spouse needs alternative coverage until reaching medicare age
- One spouse still working: Consider whether the working spouse's coverage can cover both partners or if separate Medicare enrollment makes more sense
Understanding how Medicare eligibility works for different family situations helps you avoid costly mistakes.
Late Enrollment Penalties
Missing your Initial Enrollment Period without creditable coverage results in permanent penalties that increase your premiums for as long as you have Medicare. These penalties serve as a significant financial incentive to enroll on time.
Part A Late Enrollment Penalty
If you have to pay a premium for Part A and don't buy it when first eligible, your monthly premium may increase by 10%. You'll pay this higher premium for twice the number of years you could have had Part A but didn't sign up.
Part B Late Enrollment Penalty
The Part B penalty is more common and more complex. Your monthly premium increases by 10% for each full 12-month period you could have had Part B but didn't enroll. This penalty continues for as long as you have Part B coverage.
Example calculation: If you delay enrollment for 30 months (two full 12-month periods plus six months), your penalty would be 20% of the standard Part B premium, added to your monthly payment indefinitely.
| Delay Period | Penalty Percentage | 2026 Monthly Impact* |
|---|---|---|
| 12 months | 10% | Approximately $18.50 |
| 24 months | 20% | Approximately $37.00 |
| 36 months | 30% | Approximately $55.50 |
*Based on estimated 2026 Part B premium of $185 (subject to change)
The seven-month deadline that determines lifetime Medicare premiums underscores why timing matters so much.
Special Enrollment Periods Beyond Medicare Age
Even if you miss your Initial Enrollment Period, you may qualify for a Special Enrollment Period (SEP) that allows you to enroll without penalties. These occur when you experience certain qualifying life events.
Common Special Enrollment Period triggers include:
- Losing employer coverage: You have eight months after coverage ends
- Moving outside your plan's service area: Must enroll within two months
- Losing Medicaid coverage: Immediate enrollment opportunity
- Returning from living abroad: Special rules apply for U.S. citizens
- Released from incarceration: Specific enrollment windows available
Special Enrollment Periods protect you from gaps in coverage and penalties when circumstances beyond your control affect your insurance. However, you must take action within the specified timeframes.
For residents in the Greensboro, High Point, Winston Salem, and Kernersville areas, reaching out to Moser Insurance Group Inc at moserinsurancegroup@gmail.com ensures you understand which Special Enrollment Period applies to your situation.
Medicare Age and Other Coverage Options
Reaching medicare age doesn't mean you're limited to Original Medicare (Parts A and B). You have several coverage paths to consider, each with distinct advantages.
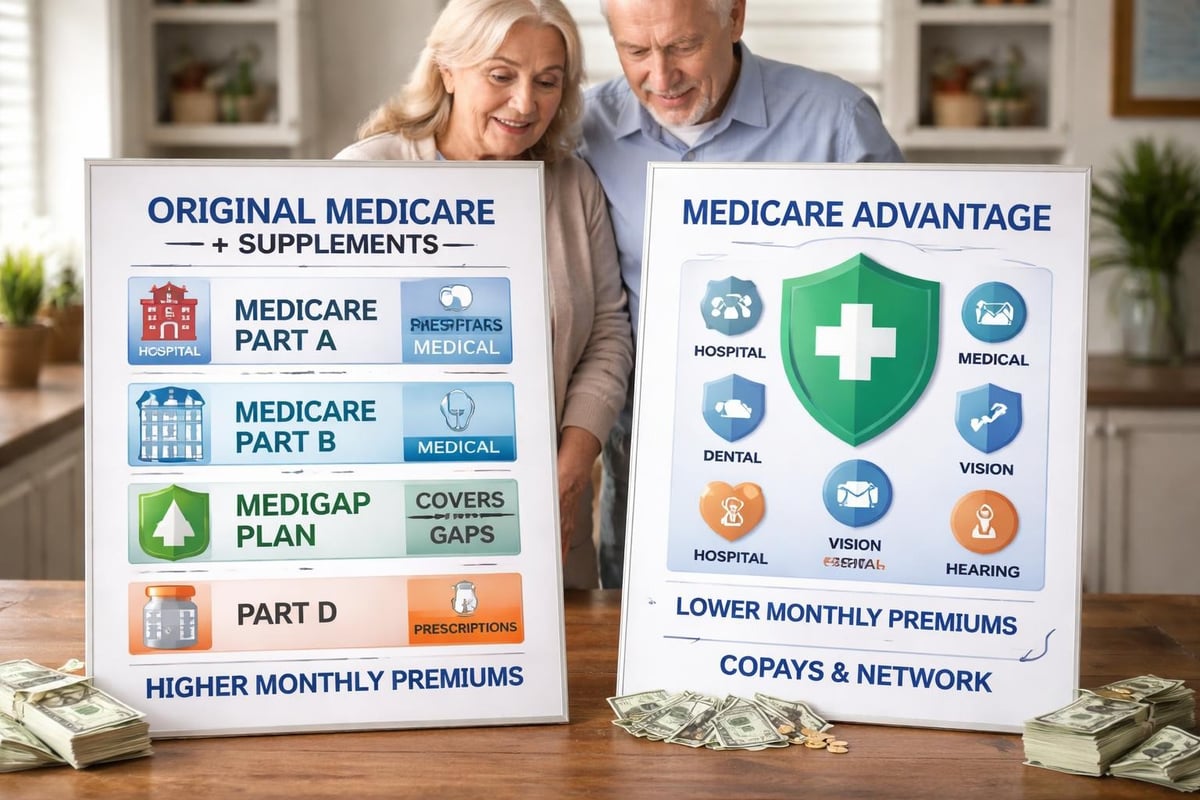
Medicare Advantage (Part C)
Medicare Advantage plans are offered by private insurance companies approved by Medicare. These plans:
- Cover everything Original Medicare covers
- Often include prescription drug coverage (Part D)
- May offer additional benefits like dental, vision, and hearing
- Typically have network restrictions
- Use different cost-sharing structures
Medigap (Medicare Supplement Insurance)
Medigap policies help cover the out-of-pocket costs that Original Medicare doesn't pay, such as copayments, coinsurance, and deductibles. Important considerations:
- Best to purchase during your Medigap Open Enrollment Period: The six-month period beginning when you're 65 or older and enrolled in Part B
- Guaranteed issue rights protect you from medical underwriting during this window
- After this period, you may face higher premiums or denial based on health conditions
Prescription Drug Coverage (Part D)
Unless you have creditable prescription drug coverage from another source, you should enroll in a Part D plan when you reach medicare age. Delaying enrollment results in a late enrollment penalty that increases your premiums permanently.
The Medicare enrollment and eligibility guidelines provided by CMS offer detailed information about coordinating these different coverage options.
Planning Timeline for Medicare Age
Creating a timeline as you approach medicare age ensures you don't miss critical deadlines or opportunities. This planning should begin well before your 65th birthday.
12 months before medicare age:
- Review current health insurance coverage and determine if it's creditable
- Understand your employer's policies regarding Medicare enrollment
- Begin researching Medicare options available in your area
- Consider scheduling an appointment with a Medicare specialist
6 months before medicare age:
- Decide whether to enroll in Part B or delay if you have qualifying employer coverage
- Research Medicare Advantage and Medigap plans in the Triad Area
- Compare prescription drug plans based on your current medications
- Gather documentation of creditable coverage if delaying enrollment
3 months before medicare age:
- Complete your Medicare enrollment through Social Security
- Finalize decisions on supplemental coverage
- Ensure all applications are submitted before deadlines
- Set up any automatic payments for premiums
Birth month and after:
- Confirm receipt of Medicare card and all insurance documents
- Verify coverage effective dates
- Update healthcare providers with new insurance information
- Keep records of all enrollment dates for future reference
Understanding key milestone ages in retirement helps you see how medicare age fits into your broader retirement planning strategy.
Common Medicare Age Mistakes to Avoid
Even well-informed individuals make mistakes when navigating Medicare enrollment at age 65. Being aware of these common pitfalls helps you avoid expensive errors.
Assuming automatic enrollment applies to everyone: Only those already receiving Social Security benefits are automatically enrolled. If you haven't claimed Social Security, you must actively enroll in Medicare.
Confusing creditable coverage rules: Not all employer coverage qualifies as creditable. HSA-compatible high-deductible health plans and retiree coverage have specific rules. Verify your coverage status in writing from your plan administrator.
Waiting to compare plans: The best time to research options is before you need to make decisions, not during your enrollment window when you're rushed.
Ignoring state-specific programs: Some states offer additional assistance programs for Medicare beneficiaries. North Carolina residents in Greensboro, Winston Salem, High Point, and Kernersville should explore local resources.
Failing to coordinate with other benefits: Medicare coordination with Veterans Affairs benefits, Medicaid, and employer coverage requires understanding complex rules.
The National Council on Aging’s eligibility checklist helps you verify you've considered all factors before making enrollment decisions.
Getting Expert Help with Medicare Age Decisions
The complexity of Medicare enrollment and the permanent consequences of mistakes make professional guidance valuable. Working with an experienced Medicare insurance advisor provides several benefits:
- Personalized analysis of your specific situation
- Comparison of all available plans in your area
- Help understanding how Medicare coordinates with other coverage
- Ongoing support as your needs change
Moser Insurance Group Inc specializes in helping individuals and families throughout the Triad Area navigate Medicare decisions. Whether you're approaching medicare age, caring for a parent who's enrolling, or dealing with a complex employment situation, personalized guidance makes the process clearer and less stressful.
Local expertise matters: Medicare plans and options vary by location. An advisor familiar with Greensboro, High Point, Winston Salem, and Kernersville can identify plans with the best provider networks and coverage for your specific area.
To discuss your Medicare options as you approach age 65, contact Moser Insurance Group Inc at 336-862-1763 or visit moserinsurancegroup.com to learn more about comprehensive insurance planning that goes beyond Medicare, including life insurance options and other coverage needs.
Medicare Age and Financial Planning
Reaching medicare age has significant implications for your overall retirement financial plan. Healthcare costs represent one of the largest expenses in retirement, and Medicare provides the foundation for managing these costs.
Premium Budgeting
Understanding your Medicare costs helps with retirement income planning:
- Part A: Premium-free for most beneficiaries
- Part B: Standard premium in 2026 (subject to annual adjustment)
- Part D: Varies by plan, averaging $30-$70 monthly
- Medigap or Medicare Advantage: Additional premiums vary widely
- Income-Related Monthly Adjustment Amount (IRMAA): High-income beneficiaries pay surcharges
IRMAA considerations: If your modified adjusted gross income exceeds certain thresholds, you'll pay higher premiums for Part B and Part D. These thresholds are based on tax returns from two years prior, so 2024 income affects 2026 premiums.
Healthcare Spending Accounts
Medicare eligibility affects your ability to contribute to Health Savings Accounts (HSAs). Once you enroll in any part of Medicare, you can no longer make new HSA contributions, though you can still use existing HSA funds tax-free for qualified medical expenses.
If you're delaying Medicare while working, maintaining HSA eligibility might be valuable for tax-advantaged healthcare savings. This consideration factors into the decision of when to enroll relative to medicare age.
Resources for Medicare Age Planning
Educating yourself about Medicare leads to better decisions. Several authoritative resources provide reliable information:
Official government sources: Medicare Interactive offers comprehensive overviews of eligibility, enrollment, and coverage options. These resources are updated regularly to reflect current rules and requirements.
Professional advisors: Insurance professionals specializing in Medicare provide personalized guidance based on your circumstances. They stay current on plan changes, enrollment rules, and local coverage options.
Community education: Many organizations offer Medicare education workshops in the Triad Area. These sessions provide opportunities to ask questions and learn alongside others approaching medicare age.
Online tools: Medicare.gov offers plan comparison tools that show options available in your ZIP code, including premium costs, coverage details, and quality ratings.
Taking advantage of multiple resources ensures you understand Medicare from different perspectives and can make informed choices aligned with your healthcare needs and financial situation.
Understanding medicare age eligibility and enrollment requirements protects you from costly penalties while ensuring comprehensive healthcare coverage as you transition into retirement. Whether you're approaching 65, planning ahead, or helping a family member navigate these decisions, having expert guidance makes all the difference. Moser Insurance Group Inc helps individuals and families throughout Greensboro, High Point, Winston Salem, Kernersville, and the Triad Area understand their Medicare options with clear, personalized support. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your Medicare questions and make confident decisions about your healthcare coverage-visit Moser Insurance Group Inc to learn more about how we can help.
Recent Comments