

Understanding Medicare can feel overwhelming when you're approaching age 65 or helping a family member navigate their healthcare options. The term "medicare abcd" represents the four distinct parts of Medicare that work together to provide comprehensive health coverage for millions of Americans. Each part serves a specific purpose, and knowing how they interact helps you build the right coverage package for your needs. Whether you're in Greensboro, Winston Salem, High Point, Kernersville, or anywhere in the Triad Area, making informed decisions about Medicare ABCD can protect your health and your finances for years to come.
Breaking Down Medicare Part A: Hospital Insurance
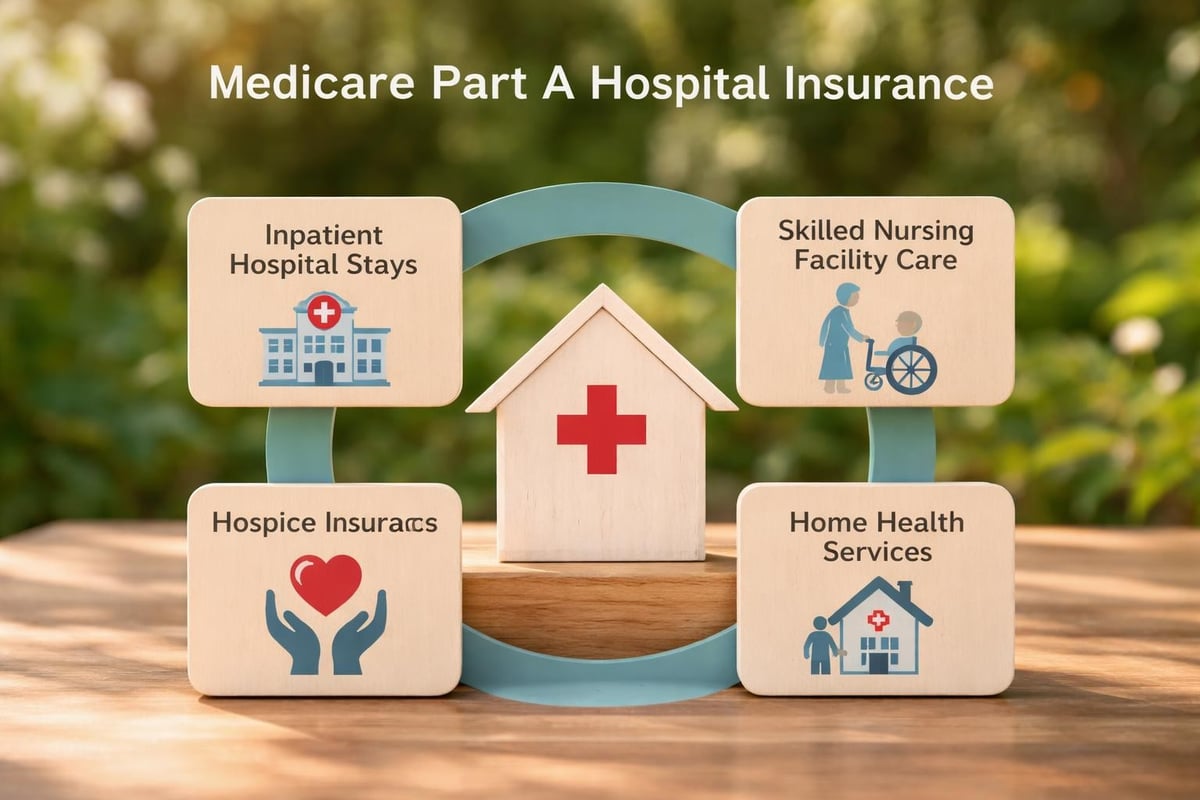
Medicare Part A provides hospital insurance coverage and is often called the foundation of Medicare. Most people who paid Medicare taxes during their working years receive Part A premium-free when they turn 65. This part covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services.
When you're admitted to a hospital, Part A handles the costs associated with your room, meals, nursing care, and necessary medications during your stay. However, it's important to understand the benefit periods and how deductibles work. In 2026, the deductible for Medicare Part A continues to apply per benefit period rather than per calendar year.
What Part A Covers
- Inpatient hospital care (semi-private room, meals, general nursing)
- Skilled nursing facility care (following a qualifying hospital stay)
- Hospice care for terminally ill patients
- Limited home health care services
- Inpatient care in religious non-medical healthcare institutions
Part A does not cover long-term care or custodial care, which many people mistakenly believe Medicare covers. Understanding these limitations helps you plan for potential out-of-pocket expenses or supplemental coverage needs. For residents in the Triad Area seeking comprehensive guidance, exploring Medicare supplement options can help fill these gaps.
Understanding Medicare Part B: Medical Insurance
Medicare Part B covers medical insurance, including doctor visits, outpatient care, preventive services, and medical equipment. Unlike Part A, most beneficiaries pay a monthly premium for Part B coverage. The standard premium amount adjusts annually based on federal guidelines and your income level.
Part B operates on a calendar year deductible system. After you meet your annual deductible, you typically pay 20% of the Medicare-approved amount for most services. This cost-sharing arrangement makes supplemental coverage particularly valuable for managing predictable healthcare expenses.
Core Part B Benefits
Covered Services:
- Doctor visits and outpatient care
- Preventive services (screenings, vaccines, wellness visits)
- Ambulance services
- Durable medical equipment (wheelchairs, walkers, hospital beds)
- Mental health services (outpatient)
- Limited outpatient prescription drugs (certain chemotherapy drugs, immunosuppressive drugs)
The official Medicare website provides detailed information about which specific services fall under Part B coverage. This resource helps you understand exactly what to expect when visiting healthcare providers.
Income-Related Adjustments
Higher-income beneficiaries pay additional amounts for Part B through IRMAA (Income-Related Monthly Adjustment Amount). The 2026 IRMAA brackets and surcharges determine whether you'll pay more than the standard premium based on your modified adjusted gross income from two years prior.
| Income Level (Individual) | Income Level (Joint) | Monthly Part B Premium |
|---|---|---|
| $106,000 or less | $212,000 or less | Standard premium |
| $106,001-$133,000 | $212,001-$266,000 | Standard + surcharge tier 1 |
| $133,001-$167,000 | $266,001-$334,000 | Standard + surcharge tier 2 |
| $167,001-$200,000 | $334,001-$400,000 | Standard + surcharge tier 3 |
| Above $200,000 | Above $400,000 | Standard + surcharge tier 4 |
If you experience a life-changing event such as retirement, divorce, or loss of income, you can appeal a Medicare premium surcharge to potentially reduce your IRMAA amount.
Exploring Medicare Part C: Medicare Advantage Plans
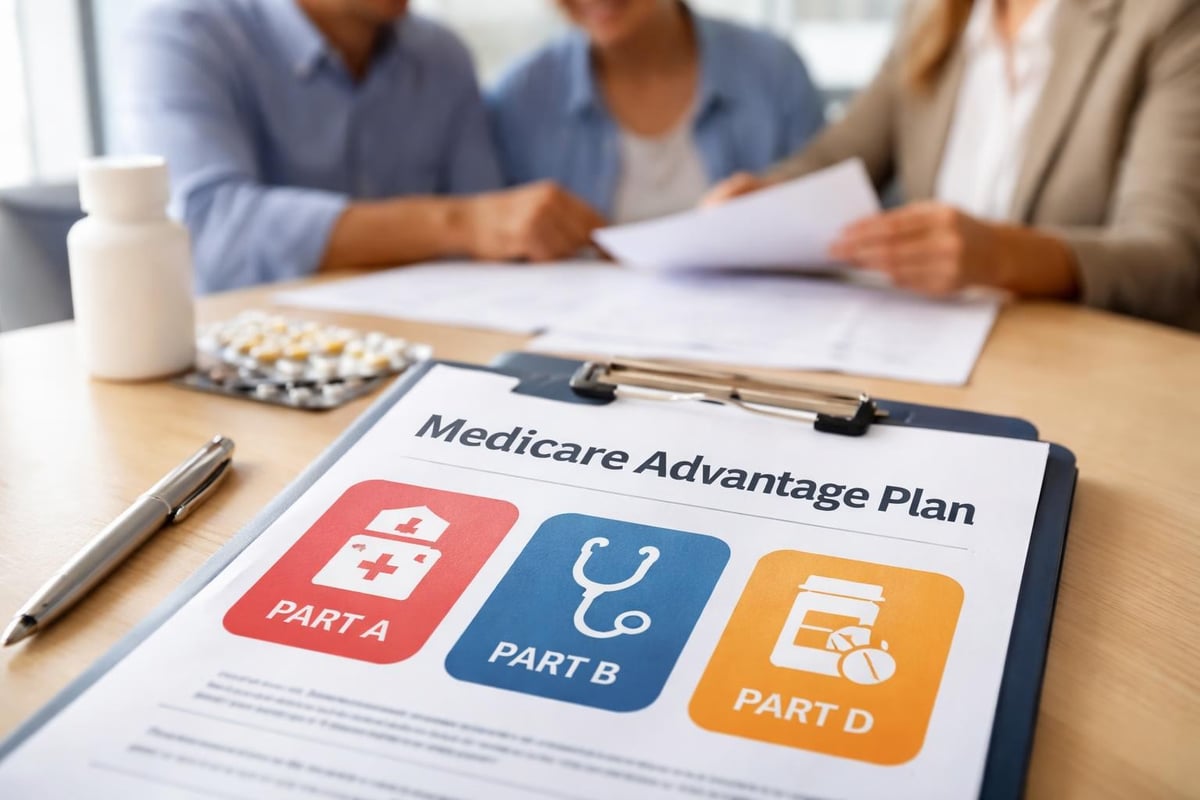
Medicare Part C, commonly known as Medicare Advantage, offers an alternative way to receive your Medicare benefits. Private insurance companies approved by Medicare provide these plans, which must cover everything Original Medicare (Parts A and B) covers. Many Medicare Advantage plans also include additional benefits like dental, vision, hearing, and prescription drug coverage.
When you enroll in a Medicare Advantage plan, you're still in Medicare, but the private insurance company manages your healthcare coverage. These plans often feature network restrictions, requiring you to use specific doctors and hospitals except in emergencies.
Medicare Advantage Plan Types
- Health Maintenance Organization (HMO) Plans – Require referrals and network providers
- Preferred Provider Organization (PPO) Plans – Offer more flexibility with out-of-network care
- Private Fee-for-Service (PFFS) Plans – Determine payment amounts for providers
- Special Needs Plans (SNPs) – Designed for specific groups with particular conditions
The landscape of Medicare Advantage continues to evolve, with major insurers scaling back their plan offerings in certain markets for 2026. This makes working with a knowledgeable local agent even more critical.
For those in High Point, Winston Salem, or Greensboro, understanding the differences between Medicare Advantage and Medicare Supplements helps you choose the right path for your healthcare needs.
Navigating Medicare Part D: Prescription Drug Coverage
Medicare Part D provides prescription drug coverage through private insurance companies approved by Medicare. Whether you have Original Medicare or a Medicare Advantage plan without drug coverage, you can add a standalone Part D plan to help manage medication costs.
Understanding medicare abcd means recognizing that Part D operates differently from other Medicare parts. Plans vary significantly in covered medications (formularies), cost-sharing structures, and pharmacy networks. The North Carolina Department of Insurance provides resources to help residents compare Part D options available in their area.
Part D Cost Structure
Part D plans typically include multiple cost phases throughout the year:
- Monthly premium – Varies by plan, with IRMAA surcharges for higher-income beneficiaries
- Annual deductible – Some plans have no deductible, while others charge the maximum allowed
- Initial coverage phase – You pay copays or coinsurance until reaching a spending threshold
- Coverage gap – Cost-sharing continues with specific percentages for brand and generic drugs
- Catastrophic coverage – Lower cost-sharing after reaching the out-of-pocket maximum
Recent reforms have significantly improved Part D coverage. The Medicare Part D reforms enacted between 2023 and 2025 include a $2,000 out-of-pocket cap and the Medicare Prescription Payment Plan, which helps beneficiaries manage costs more predictably.
Choosing the Right Part D Plan
Selecting a Part D plan requires careful evaluation of your specific medications and pharmacy preferences. Consider these factors:
- Does the plan cover all your current medications?
- Which tier does each medication fall under?
- Are your preferred pharmacies in-network?
- What are the total annual costs including premiums, deductibles, and copays?
- Does the plan offer mail-order pharmacy options?
If you're turning 65 in Greensboro or surrounding communities, reviewing Part D options during your Initial Enrollment Period prevents coverage gaps and potential late enrollment penalties.
How Medicare ABCD Parts Work Together
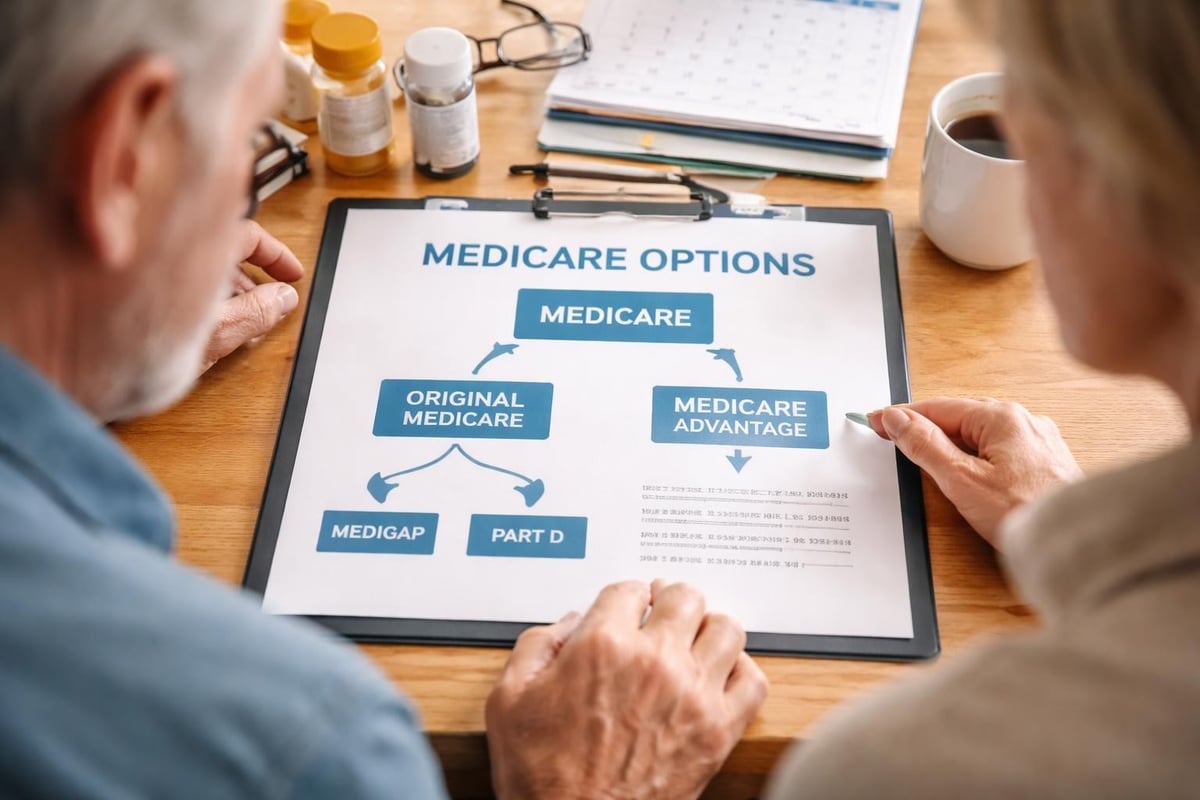
The medicare abcd framework represents a comprehensive system designed to address different healthcare needs. Most beneficiaries start with Original Medicare (Parts A and B), then decide whether to add Part D for prescriptions and a Medicare Supplement for additional coverage, or switch to a Medicare Advantage plan (Part C) that combines benefits.
Coverage Combination Options
| Approach | Components | Best For |
|---|---|---|
| Original Medicare + Medigap + Part D | Parts A, B, Medicare Supplement, standalone Part D | Those who want provider flexibility and predictable costs |
| Medicare Advantage | Part C (includes A, B, often D) | Those comfortable with network restrictions and integrated care |
| Original Medicare + Part D only | Parts A, B, standalone Part D | Healthy individuals comfortable with cost-sharing |
Understanding how these components interact helps you avoid coverage gaps and duplicate coverage. For example, it's illegal for insurance companies to sell you a Medicare Supplement if you're enrolled in a Medicare Advantage plan.
Enrollment Periods and Timing Considerations
Navigating medicare abcd successfully requires understanding when you can enroll, change, or drop coverage. Missing enrollment windows can result in permanent penalties or coverage gaps that affect your healthcare access and finances.
Initial Enrollment Period (IEP)
Your IEP spans seven months: three months before your 65th birthday month, your birthday month, and three months after. During this window, you can enroll in Parts A, B, and D without penalties. Resources for those turning 65 in Winston Salem provide localized guidance for navigating this critical period.
Annual Enrollment Period (AEP)
Running from October 15 through December 7 each year, AEP allows you to:
- Switch from Original Medicare to Medicare Advantage or vice versa
- Change Medicare Advantage plans
- Add, drop, or change Part D prescription drug plans
- Add, drop, or switch Medicare Supplement plans (subject to underwriting outside guaranteed issue periods)
Medicare Advantage Open Enrollment Period
From January 1 through March 31, current Medicare Advantage enrollees can switch to a different Medicare Advantage plan or return to Original Medicare and add a Part D plan.
Cost Considerations Across Medicare ABCD
Managing healthcare costs effectively means understanding the financial obligations associated with each part of medicare abcd. Beyond monthly premiums, you'll encounter deductibles, copayments, and coinsurance that vary depending on your coverage choices.
2026 Cost Overview
The projected costs for Medicare in 2026 include adjustments to premiums, deductibles, and out-of-pocket maximums across all parts. Planning for these expenses helps you budget appropriately and evaluate whether supplemental coverage makes financial sense.
Typical Annual Costs:
- Part A: Premium-free for most (deductible per benefit period)
- Part B: Monthly premium plus 20% coinsurance after deductible
- Part C: Plan-specific premiums and cost-sharing (plus Part B premium)
- Part D: Monthly premium, deductible, and tiered copays
For comprehensive cost protection, many beneficiaries in Kernersville and the surrounding Triad Area choose Medicare Supplement plans to cover the gaps in Original Medicare, creating predictable monthly expenses instead of uncertain out-of-pocket costs.
Special Considerations for North Carolina Residents
Living in North Carolina provides access to numerous Medicare Advantage and Part D plans, but options vary by county. The Triad Area, including Greensboro, High Point, Winston Salem, and Kernersville, typically offers robust plan selections from multiple carriers.
State-specific factors affecting your medicare abcd decisions include:
- Regional plan availability and network coverage
- Local healthcare provider participation in Medicare Advantage networks
- Prescription drug plan formularies that may favor certain regional pharmacy chains
- State regulations governing Medicare Supplement plan sales
Working with a local insurance professional who understands these regional nuances ensures you select coverage that works with your preferred doctors and pharmacies. Whether you need Medicare help in High Point or guidance in Winston Salem, local expertise makes a significant difference.
Making Informed Decisions About Medicare ABCD
Selecting the right combination of medicare abcd coverage requires evaluating your current health status, prescription needs, preferred healthcare providers, and financial situation. No single approach works for everyone, which is why personalized guidance proves invaluable during the decision-making process.
Questions to Ask Yourself
- Do I have preferred doctors or specialists I want to continue seeing?
- What prescription medications do I take regularly?
- How often do I typically visit doctors or require medical care?
- What is my monthly budget for healthcare premiums and potential out-of-pocket costs?
- Do I value provider flexibility or prefer lower potential costs with network restrictions?
Comprehensive guides to understanding Medicare Parts A through D offer additional perspectives as you evaluate your options. However, general information works best when combined with personalized analysis of your specific situation.
The Value of Professional Guidance
Medicare's complexity means even well-informed consumers benefit from professional assistance. Independent insurance agents can compare multiple carriers and plan types, helping you understand the true costs and benefits of different medicare abcd combinations without the pressure of a sales quota.
For personalized support in the Triad Area, contact Moser Insurance Group Inc at 336-862-1763 or email moserinsurancegroup@gmail.com. You can also visit moserinsurancegroup.com to learn more about available options and schedule a no-pressure consultation.
Common Medicare ABCD Mistakes to Avoid
Even with the best intentions, beneficiaries often make preventable errors when navigating medicare abcd. Understanding these common pitfalls helps you avoid costly mistakes that could affect your coverage or finances.
Frequent Errors
- Missing enrollment deadlines – Results in late enrollment penalties that last a lifetime
- Failing to compare plans annually – Coverage and costs change yearly; last year's best plan may not remain optimal
- Ignoring IRMAA implications – Not planning for income-based surcharges when strategizing retirement distributions
- Assuming all doctors accept Medicare Advantage – Network restrictions may exclude preferred providers
- Overlooking prescription drug coverage – Even if you take no medications now, you'll face penalties when you need coverage later
Understanding how Medicare Advantage plans work in your area prevents surprises about network restrictions and referral requirements.
Verification Steps
Before finalizing any medicare abcd coverage decision:
- Confirm your doctors participate in the plan network
- Verify all medications appear on the plan formulary
- Calculate total annual costs including premiums, deductibles, and expected copays
- Review the plan's star rating and customer satisfaction scores
- Understand the appeals process if coverage is denied
Taking these verification steps upfront prevents discovering coverage problems when you need medical care.
Planning for Long-Term Medicare Needs
Your medicare abcd coverage needs will likely change over time as your health evolves, medications change, and healthcare costs adjust. Building flexibility into your coverage strategy ensures you can adapt without disrupting care or facing unnecessary expenses.
Consider how your coverage choice affects your ability to make changes later. Medicare Advantage plans require annual re-evaluation during AEP, while Medicare Supplement plans offer stability but may be difficult to change after your initial enrollment due to medical underwriting.
Future-Proofing Your Coverage
- Review coverage annually during the Fall enrollment period
- Keep detailed records of healthcare expenses to identify cost trends
- Stay informed about Medicare policy changes and benefit updates
- Maintain relationships with knowledgeable insurance professionals who can advise on changes
- Plan for potential increases in healthcare needs as you age
Working with trusted advisors who understand both medicare abcd and your personal situation creates a foundation for confident decision-making year after year.
Understanding medicare abcd empowers you to make informed coverage decisions that protect both your health and your financial security. The interaction between Parts A, B, C, and D creates numerous coverage options, each with distinct advantages depending on your circumstances. Moser Insurance Group Inc helps individuals and families throughout Greensboro, Winston Salem, High Point, Kernersville, and the Triad Area understand their Medicare options with clear guidance and personalized support. We focus on educating clients so they can make confident insurance decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Medicare coverage needs.
Recent Comments