

Finding the right life insurance for older people requires understanding how age affects coverage options, premiums, and qualification requirements. Many individuals over 50 or approaching retirement wonder whether they still need life insurance and what types of policies remain accessible. The good news is that multiple coverage solutions exist specifically designed for older applicants, each addressing different financial protection needs and budget considerations.
Understanding Life Insurance Options After Age 50
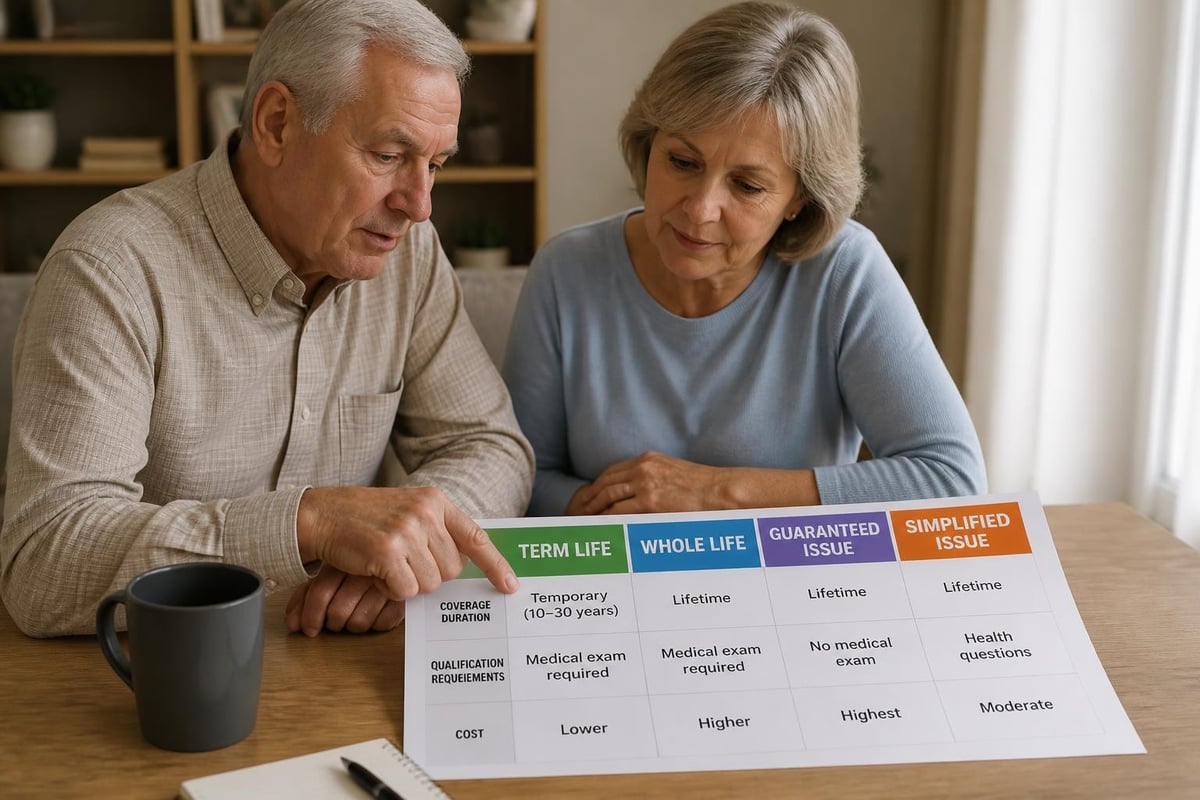
Life insurance for older people comes in several distinct forms, each with unique characteristics that serve different purposes. The most common categories include term life, whole life, universal life, and guaranteed issue policies. Understanding these fundamental differences helps older applicants match their financial goals with appropriate coverage.
Term life insurance provides coverage for a specific period, typically 10, 20, or 30 years. While premiums increase with age, term policies remain the most affordable option for temporary needs. This type works well for covering specific obligations like a remaining mortgage balance or supporting a spouse until Social Security benefits begin.
Permanent life insurance includes whole life and universal life policies that provide lifetime coverage and accumulate cash value. These policies cost significantly more than term insurance but guarantee death benefit payment regardless of when death occurs, assuming premiums remain current.
Guaranteed Issue and Simplified Issue Policies
For individuals with health conditions that prevent approval for traditional policies, guaranteed issue life insurance requires no medical exam and accepts all applicants within certain age ranges. These policies typically:
- Offer lower coverage amounts (usually $5,000 to $25,000)
- Include a graded death benefit period (often two to three years)
- Charge higher premiums relative to coverage amount
- Provide immediate approval without health questions
Simplified issue policies require answering health questions but skip the medical exam requirement. They bridge the gap between fully underwritten and guaranteed issue coverage, offering moderate coverage amounts at more favorable rates than guaranteed issue options.
How Age Affects Premiums and Eligibility
Insurance companies calculate premiums based primarily on life expectancy, which naturally increases costs for older applicants. Age limits for life insurance vary by company and policy type, with some traditional policies accepting applicants into their 80s while others cap eligibility at age 75 or younger.
Several factors influence premium calculations beyond just age:
- Current health status including chronic conditions like diabetes or heart disease
- Family medical history indicating genetic risk factors
- Lifestyle choices such as tobacco use or high-risk activities
- Gender, with women typically paying lower rates due to longer life expectancy
- Coverage amount and policy duration selected
| Age Range | Average Monthly Premium (Term) | Average Monthly Premium (Whole Life) |
|---|---|---|
| 50-54 | $75-$150 | $300-$500 |
| 55-59 | $110-$200 | $400-$650 |
| 60-64 | $165-$300 | $550-$850 |
| 65-69 | $250-$450 | $750-$1,200 |
| 70+ | $400-$700 | $1,000-$1,800 |
Estimates for $100,000 coverage for non-smoking applicants in good health. Actual rates vary significantly based on individual circumstances.
Determining Coverage Needs in Later Life
Life insurance for older people serves different purposes than policies purchased during younger working years. Rather than replacing decades of future income, coverage at this stage typically addresses specific financial obligations and legacy goals. Evaluating your actual needs prevents overpaying for unnecessary coverage.
Common Reasons for Senior Life Insurance
Final expense coverage remains the most popular reason older individuals purchase life insurance. Funeral costs, medical bills, and estate settlement expenses can easily reach $15,000 to $30,000 or more. A modestly sized policy ensures these costs don't burden surviving family members.
Outstanding debt protection addresses mortgages, personal loans, or credit card balances that would transfer responsibility to a spouse or estate. Even if you've paid off most major debts, remaining balances deserve consideration when sizing coverage.
Income replacement for a spouse becomes critical when one partner earns significantly more than the other or when retirement benefits don't transfer fully. Ensuring your spouse maintains their standard of living after your death provides important peace of mind.
Estate equalization helps business owners or individuals with unequal assets among heirs. Life insurance can balance inheritances when one child receives a family business or property that can't be easily divided.
- Legacy gifts to grandchildren for education or first homes
- Charitable donations to causes you support
- Business succession funding for family enterprises
- Special needs trust funding for dependent adult children
Medical Underwriting and Application Process
The application process for life insurance for older people varies significantly based on policy type and coverage amount. Traditional fully underwritten policies require the most comprehensive health evaluation but offer the best rates for healthy applicants. Understanding what to expect reduces anxiety and helps you prepare appropriately.
What Medical Underwriting Involves
Full medical underwriting includes a detailed application questionnaire, phone interview, medical exam, and review of prescription drug history. The paramedical exam typically measures:
- Height, weight, and blood pressure
- Blood sample testing for cholesterol, glucose, and other markers
- Urine sample analysis
- Potentially an EKG for older applicants or higher coverage amounts
Many applicants worry about health conditions disqualifying them entirely. In reality, insurers frequently approve applicants with managed chronic conditions like high blood pressure, diabetes, or previous cancer diagnoses. The key factors include how well conditions are controlled, how long they've been stable, and whether you follow prescribed treatment plans.
Accelerated underwriting uses data analytics and prescription databases to approve some applicants without medical exams. This newer approach works best for younger, healthier seniors seeking moderate coverage amounts. Processing typically completes within days rather than weeks.
For those serving the Triad Area including Greensboro, Kernersville, High Point, and Winston Salem, local insurance guidance helps navigate carrier options and underwriting requirements specific to North Carolina residents.
Comparing Costs Across Policy Types
Understanding how different life insurance for older people products compare on cost requires looking beyond just monthly premiums. The total value proposition includes coverage guarantees, cash value accumulation, premium flexibility, and death benefit certainty.
| Policy Feature | Term Life | Whole Life | Universal Life | Guaranteed Issue |
|---|---|---|---|---|
| Coverage Duration | Fixed term | Lifetime | Lifetime | Lifetime |
| Premium Structure | Level or increasing | Fixed | Flexible | Fixed |
| Cash Value | None | Yes | Yes | Limited |
| Medical Exam Required | Usually yes | Usually yes | Usually yes | No |
| Best For | Temporary needs | Estate planning | Flexible needs | Difficult to insure |
Premium payment timing also affects total costs. Some permanent policies allow single premium payments, limited payment periods (10-20 years), or lifetime payments. Shorter payment periods mean higher individual premiums but lower total lifetime costs.
Hidden Costs to Consider
Beyond stated premiums, several factors influence the true cost of coverage:
- Policy riders and additional benefits that enhance coverage
- Guaranteed versus non-guaranteed premium structures
- Surrender charges if you cancel permanent policies early
- Opportunity cost of premium dollars versus alternative investments
Working with an experienced agent helps evaluate these factors in context of your complete financial picture rather than focusing solely on monthly premium amounts.
Special Considerations for Medicare Recipients
Older Americans enrolled in Medicare often question whether life insurance still serves a purpose once healthcare costs become more predictable. The reality is that Medicare coverage actually creates several specific life insurance planning considerations that shouldn't be overlooked.
Medicare gap coverage addresses expenses that Medicare Parts A and B don't fully cover. While Medicare Supplement plans handle most gaps, life insurance can provide a financial cushion for copays, deductibles, and prescription costs that accumulate over time. Those exploring Medicare options in the Greensboro area should evaluate how life insurance fits within their comprehensive healthcare and financial strategy.
Medicare Advantage plans sometimes include small life insurance benefits, but these rarely replace the need for dedicated coverage. Understanding how these complementary insurance products work together creates more comprehensive protection.
When Life Insurance Makes Less Sense
Not every older person needs life insurance. Certain financial situations make coverage unnecessary or even counterproductive. Recognizing when to forgo or reduce coverage saves money for more productive uses.
Sufficient liquid assets eliminate the need for insurance when you have accessible funds to cover final expenses and any obligations. If you've accumulated $100,000 or more in savings specifically designated for end-of-life costs, additional insurance may be redundant.
Situations Where Coverage Isn't Critical
- No surviving dependents who rely on your income
- All major debts completely paid off including mortgage
- Spouse has adequate retirement income from pensions and Social Security
- No desire to leave inheritance beyond existing assets
- Adult children are financially independent
- Estate doesn't face significant tax obligations
Cost-benefit analysis becomes increasingly important as premiums rise with age. A 75-year-old paying $500 monthly for a $50,000 policy would need to live less than eight years for beneficiaries to receive more than paid premiums. Investing those funds differently might serve family better.
Some individuals discover that converting existing term policies to permanent coverage through contractual conversion rights provides better value than purchasing new coverage. This option locks in insurability without new underwriting.
Choosing Between Carriers and Products
The life insurance marketplace includes dozens of companies offering products targeted at older applicants. Comparing senior life insurance options requires evaluating company financial strength, policy features, and customer service quality alongside premium costs.
Key Comparison Factors
Financial strength ratings from agencies like AM Best, Moody's, and Standard & Poor's indicate an insurer's ability to pay future claims. Look for ratings of A- or higher, as life insurance represents a long-term promise that requires financial stability over decades.
Contestability and suicide clauses appear in all policies but vary in duration and specifics. The standard two-year contestability period allows insurers to investigate and potentially deny claims for misrepresentations discovered after death. Understanding these provisions prevents unpleasant surprises for beneficiaries.
Conversion and portability options matter when circumstances change. Some term policies allow conversion to permanent coverage without new underwriting. Portability lets you maintain coverage if you change employment or move between states.
Working with a knowledgeable agent familiar with products from multiple carriers ensures you see appropriate options rather than a limited selection from a single company. Moser Insurance Group Inc specializes in helping individuals understand their choices without pressure, providing education that supports confident decisions. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation.
Application Strategies for Approval
Maximizing your chances of approval for life insurance for older people at favorable rates requires strategic preparation. Small changes in timing, presentation, and health management can significantly impact underwriting decisions.
Timing your application around health improvements creates advantages. If you're currently working with your doctor to manage blood pressure, cholesterol, or blood sugar levels, waiting until these markers stabilize in a healthy range before applying can reduce premiums by 20-40% or more.
Preparation Steps Before Applying
- Schedule a checkup with your primary care physician and address any concerning test results
- Gather documentation about treatments for chronic conditions showing stable management
- Compile a complete list of current medications with dosages
- Avoid alcohol for at least 72 hours before a scheduled medical exam
- Stay well-hydrated to facilitate blood and urine sample collection
- Get adequate sleep the night before your exam
Prescription drug history receives intense scrutiny during underwriting. Insurers access databases showing all filled prescriptions for the past several years. Ensure your application accurately reflects all medications, as discrepancies raise red flags even for innocent omissions.
Some applicants benefit from applying with multiple carriers simultaneously, particularly when health conditions create uncertainty about underwriting classification. Different companies assess identical health profiles differently based on their specific underwriting guidelines and experience.
Policy Management After Purchase
Successfully securing life insurance for older people represents just the beginning. Proper policy management ensures coverage serves its intended purpose and adapts to changing circumstances over time.
Annual policy reviews verify that beneficiary designations remain current, coverage amounts still match needs, and premiums stay affordable. Major life events trigger immediate review needs:
- Death or divorce affecting designated beneficiaries
- Significant changes in financial obligations or assets
- Health improvements that might qualify for lower rates
- Retirement reducing income and changing needs
- Relocation affecting carrier availability or regulations
Premium payment management prevents accidental lapses that could terminate coverage. Setting up automatic bank drafts ensures timely payments, but maintaining awareness of withdrawal dates prevents overdrafts. Most policies include a grace period of 30-31 days after the due date before lapsing.
For permanent policies with cash value, monitoring policy performance ensures illustrations remain on track. Annual statements show current cash value, death benefit, and whether adjustments to premium payments might be necessary to maintain coverage.
Tax Implications and Estate Planning
Life insurance for older people creates several tax considerations that affect both premium payments and death benefit distributions. Understanding these rules helps maximize the value transferred to beneficiaries and avoid unintended tax consequences.
Death benefits generally pass to beneficiaries completely tax-free as income. This advantage makes life insurance exceptionally efficient for transferring wealth compared to retirement accounts or investment portfolios that trigger income taxes.
Estate Tax Considerations
Estate inclusion rules can subject large policies to federal estate taxes if you maintain ownership at death. For estates potentially exceeding the federal exemption amount ($13.99 million for individuals in 2026), transferring policy ownership to an irrevocable life insurance trust (ILIT) removes death benefits from your taxable estate.
Three-year lookback rules mean transfers of existing policies to ILITs less than three years before death still count toward estate values. Early planning prevents this issue for those with large estates.
Cash value withdrawals and loans from permanent policies receive favorable tax treatment up to your total premium payments (basis). Amounts exceeding basis become taxable income. Loans avoid taxation entirely but reduce death benefits if outstanding at death.
Making an Informed Decision
Selecting appropriate life insurance for older people requires balancing multiple competing priorities: affordability, coverage adequacy, qualification likelihood, and long-term value. No single "best" policy exists because individual circumstances vary dramatically.
Resources for seniors evaluating life insurance provide helpful comparison frameworks, but personalized guidance addresses your unique situation more effectively than general advice.
The decision process becomes clearer when you:
- Calculate specific coverage needs based on actual obligations
- Obtain quotes from multiple carriers for comparison
- Honestly assess your health status and insurability
- Consider whether temporary or permanent coverage better fits your goals
- Evaluate affordability over the expected premium payment period
- Understand what happens if you outlive term coverage or can't maintain permanent policy premiums
Second opinions provide valuable perspective when significant financial commitments are involved. Discussing options with independent agents who represent multiple carriers versus captive agents selling only one company's products reveals whether you're seeing the full range of suitable options.
Many older applicants discover that combining different policy types addresses their needs more cost-effectively than relying on a single large policy. For example, a small permanent policy covering final expenses plus term coverage protecting specific obligations often costs less than whole life insurance for the combined death benefit.
Special Programs and Discounts
Several programs and underwriting accommodations specifically benefit older life insurance applicants. Awareness of these opportunities can reduce costs or improve coverage access.
Guaranteed acceptance periods occur when group life insurance through former employers or organizations opens enrollment without medical questions. These windows typically happen annually and allow coverage increases up to specified limits regardless of health status.
Preferred and super-preferred rates remain available even for older applicants who maintain excellent health profiles. Non-smokers with favorable cholesterol, blood pressure, weight, and family history might qualify for premium discounts of 30-50% compared to standard rates.
Professional and Affinity Discounts
- Alumni associations from universities
- Professional organizations and unions
- Veterans groups and military service affiliations
- Religious organizations and churches
- Fraternal organizations with insurance programs
These group policies sometimes offer simplified underwriting or guaranteed issue provisions not available to individual applicants. However, comparing group rates against individual policies remains important since group coverage doesn't always provide the best value.
Return of premium riders available on some term policies refund all paid premiums if you outlive the coverage period. While these riders significantly increase premiums (often doubling costs), they appeal to applicants who view pure term insurance as "wasted" money if they don't die during the coverage period.
Understanding life insurance for older people empowers you to make protection decisions that align with your financial goals and family needs without overpaying for unnecessary coverage. Whether you need final expense protection, income replacement for a spouse, or legacy planning tools, appropriate options exist at every age and health status. Moser Insurance Group Inc helps individuals and families throughout the Triad Area understand their life insurance, Medicare, and health insurance options with clear guidance and personalized support. Reach out today at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your unique situation and explore coverage options without pressure.
Recent Comments