

Financial security during life's most challenging moments requires more than a single type of insurance. When serious illness strikes or a family loses a loved one, the costs extend far beyond medical bills. Life and critical illness cover work together to create a safety net that addresses both scenarios, protecting your family's finances when they're most vulnerable. Understanding how these two types of coverage complement each other helps you build comprehensive protection tailored to your specific needs.
Understanding the Fundamentals of Life and Critical Illness Cover
Life insurance pays a tax-free death benefit to your beneficiaries when you pass away, replacing your income and covering final expenses. Critical illness cover provides a lump-sum payment when you're diagnosed with a serious medical condition specified in your policy, such as cancer, heart attack, or stroke.
The key distinction lies in when benefits are paid. Traditional life insurance only pays after death, while critical illness coverage pays while you're still living. This timing difference addresses two separate financial risks that most families face.
Why Both Types of Coverage Matter
Many people focus exclusively on life insurance, assuming it covers all major financial risks. However, surviving a critical illness often creates more immediate financial strain than death itself. Medical treatments, lost income during recovery, experimental procedures not covered by health insurance, and ongoing care expenses can quickly deplete savings.
Critical illness coverage addresses these living expenses:
- Mortgage or rent payments during treatment
- Travel costs for specialized medical care
- Experimental treatments not covered by primary health insurance
- Home modifications for accessibility
- Childcare or eldercare assistance
- Everyday bills when you can't work
Meanwhile, life insurance ensures your family can maintain their standard of living, pay off debts, and fund long-term goals like college education after you're gone. Both forms of protection serve essential but different purposes in a complete financial plan.
How Life and Critical Illness Cover Work Together
Combining life and critical illness cover creates layered protection that responds to multiple scenarios. Some insurance companies offer policies that include both components, while others require separate policies for each type of coverage.
Standalone vs. Combined Policies
Standalone critical illness policies operate independently from life insurance. You receive the full critical illness benefit if diagnosed with a covered condition, and your life insurance remains intact for future death benefit protection. This approach maximizes total coverage but requires managing two separate premiums.
Combined policies link critical illness cover to your life insurance policy. When you claim the critical illness benefit, it typically reduces your life insurance death benefit by the same amount. Some policies offer "accelerated benefit riders" that advance a portion of your death benefit for critical illness expenses. These combined approaches cost less than two separate policies but provide lower total benefit amounts.
| Policy Type | Critical Illness Payment | Life Insurance Impact | Total Cost | Best For |
|---|---|---|---|---|
| Standalone Both | Full CI benefit | No reduction | Higher | Maximum protection |
| Accelerated Benefit | Partial advance | Reduced by advance amount | Moderate | Budget-conscious buyers |
| Integrated Policy | Full CI benefit | Reduced to zero | Lower | Single comprehensive policy |
Coverage Duration Considerations
Life and critical illness cover typically follow similar term structures, though the optimal duration for each may differ based on your situation. Most families need life insurance coverage through their working years until retirement savings can replace their income. Critical illness coverage becomes particularly valuable during peak earning years when you have the most financial obligations and the least accumulated savings to handle a health crisis.
Common term lengths include:
- 10-year terms for short-term protection during specific high-risk periods
- 20-year terms aligning with mortgage payoff or children reaching independence
- 30-year terms covering full working career from early adulthood to retirement
- Whole life options providing permanent protection with cash value accumulation
Families in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, often structure their coverage to match regional cost-of-living factors and typical mortgage terms for local housing markets.
Medical Conditions Covered by Critical Illness Policies
Critical illness policies define specific conditions that trigger benefit payments. While the exact list varies by insurance carrier, most policies cover major life-threatening illnesses that require significant medical intervention and recovery time.
Core Covered Conditions
The most commonly covered conditions across life and critical illness cover policies include cancer (excluding certain early-stage types), heart attack, stroke, coronary artery bypass surgery, kidney failure, and major organ transplants. These "core conditions" account for the majority of critical illness claims and appear in virtually all policies.
Additional conditions frequently covered:
- Multiple sclerosis
- Parkinson's disease
- Alzheimer's disease (when diagnosed before age 60)
- Paralysis affecting two or more limbs
- Blindness (permanent and irreversible)
- Deafness (permanent and total)
- Third-degree burns covering specific body percentage
- Coma lasting a minimum specified duration
Policy Exclusions and Limitations
Understanding what isn't covered proves equally important when evaluating life and critical illness cover. Pre-existing conditions diagnosed before policy inception typically don't qualify for benefits. Most policies include survival periods requiring you to live a specified number of days (usually 14 to 30) after diagnosis to receive payment.
Certain lifestyle-related conditions may have additional restrictions. Self-inflicted injuries, substance abuse complications, and conditions resulting from illegal activities generally don't trigger benefits. Some policies exclude certain cancers like skin cancers (except melanoma) or carcinoma in situ, considering them less severe.
Financial Planning with Combined Coverage
Calculating appropriate coverage amounts for life and critical illness cover requires analyzing your family's complete financial picture. The goal is ensuring sufficient resources to maintain your household's financial stability regardless of which type of claim occurs.
Determining Life Insurance Coverage Needs
A comprehensive approach to life insurance considers multiple financial obligations. Start by calculating annual income replacement needs, typically 5 to 10 times your annual salary depending on how many years of income your family would need to replace. Add outstanding debts including mortgages, car loans, and credit cards that would burden survivors.
Include future expenses like college education costs, final expenses averaging $7,000 to $12,000, and an emergency fund covering 6 to 12 months of household expenses. For many families, total life insurance needs range from $250,000 to $1,000,000 or more.
| Income Level | Typical Coverage Multiple | Additional Considerations |
|---|---|---|
| $50,000 | 7-10x income | Plus mortgage balance |
| $75,000 | 8-12x income | Plus education funding |
| $100,000+ | 10-15x income | Plus estate planning needs |
Calculating Critical Illness Coverage Amounts
Critical illness coverage typically ranges from $25,000 to $100,000, though higher amounts are available. Consider your health insurance deductibles and out-of-pocket maximums, income replacement for 6 to 18 months of recovery, and expenses your primary health insurance won't cover.
Many financial advisors recommend critical illness coverage equal to one year's gross income as a starting point. This amount covers most families' immediate needs during treatment and recovery without creating prohibitively expensive premiums. Families with high-deductible health plans may need higher amounts to cover the gap before their health insurance provides substantial coverage.
Premium Costs and Affordability Factors
Life and critical illness cover premiums vary significantly based on age, health status, coverage amounts, policy terms, and additional riders or benefits included. Understanding these factors helps you optimize coverage while managing costs effectively.
Age and Health Impact on Pricing
Insurance companies calculate premiums based on actuarial risk. Younger, healthier applicants receive substantially lower rates than older applicants or those with health conditions. A healthy 30-year-old might pay $25 to $40 monthly for $500,000 in term life insurance, while a 50-year-old would pay $150 to $200 for identical coverage.
Critical illness premiums follow similar age-based pricing but typically cost 30% to 50% of comparable life insurance premiums. Combined life and critical illness cover costs more than life insurance alone but less than purchasing two completely separate policies.
Factors increasing premiums:
- Tobacco use (can double or triple rates)
- High-risk occupations or hobbies
- Family history of critical illnesses
- Elevated blood pressure or cholesterol
- Body mass index outside healthy ranges
Strategies for Managing Coverage Costs
Several approaches help families afford comprehensive life and critical illness cover without overextending their budgets. Starting with term policies rather than permanent insurance reduces costs significantly while providing maximum death benefit during high-need years. You can always convert term policies to permanent coverage later if your financial situation improves.
Purchasing coverage while young and healthy locks in lower rates for the policy duration. Consider slightly longer terms than you think necessary, as extending coverage later requires new underwriting at older ages and higher premiums. For example, a 35-year-old choosing a 30-year term instead of 20 years adds minimal cost but extends protection to age 65 rather than 55.
Bundling life and critical illness cover with the same carrier often provides multi-policy discounts. Some employers offer group critical illness coverage at reduced rates, though these policies typically provide lower benefits and aren't portable if you change jobs.
Medical Underwriting and Application Process
Securing life and critical illness cover requires medical underwriting where insurance companies evaluate your health risks. The process varies by coverage amount and company policies, but understanding what to expect helps you prepare for a smoother application experience.
What to Expect During Underwriting
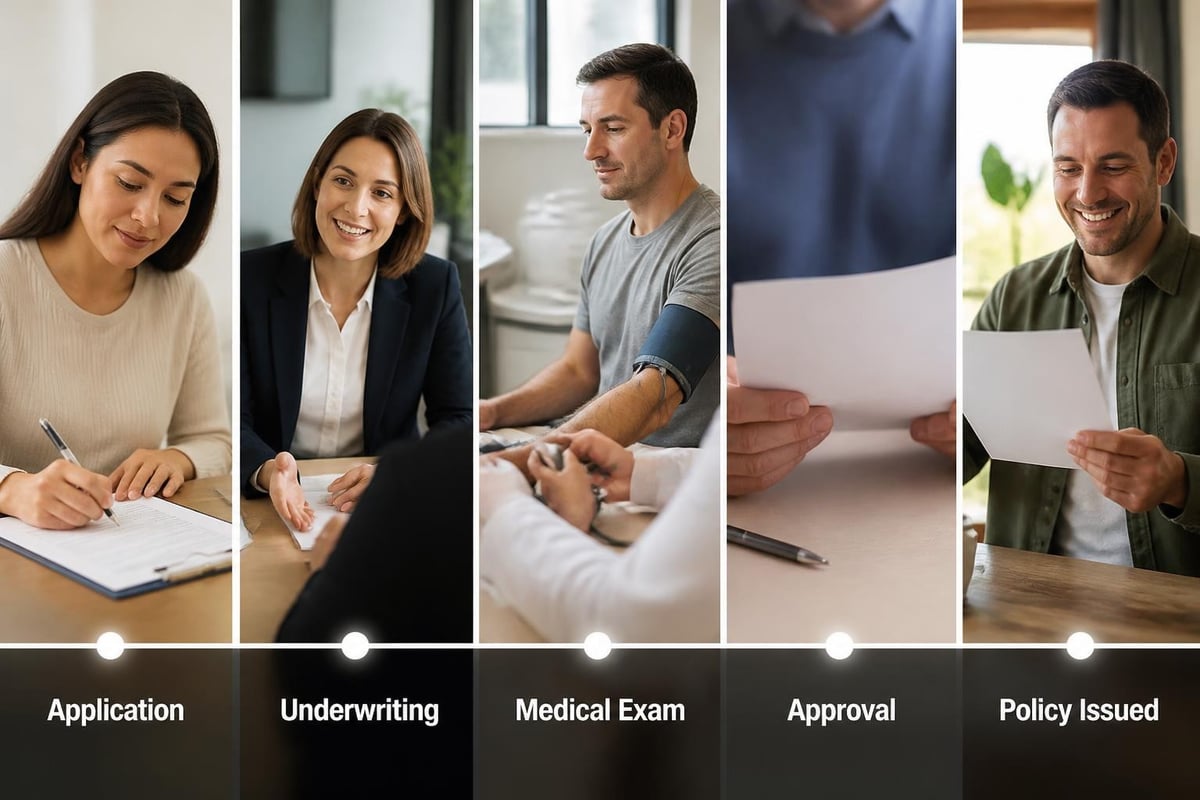
For coverage amounts below $250,000, many insurers offer simplified underwriting with health questions but no medical exam. Larger policies typically require comprehensive medical exams including blood work, urine samples, height and weight measurements, and blood pressure readings. Some companies also order attending physician statements reviewing your medical history with your doctors.
The underwriting process typically takes 2 to 6 weeks depending on application complexity. Insurance companies review prescription histories, driving records, and sometimes credit reports as part of their risk assessment. Being forthcoming about health conditions proves essential, as material misrepresentations can lead to claim denials later.
Improving Your Insurability
Several proactive steps taken before applying can improve your risk classification and reduce premiums. Schedule a physical exam with your doctor to identify and address any health concerns before insurance underwriting. Managing conditions like high blood pressure or high cholesterol through medication and lifestyle changes demonstrates health improvement.
Maintain consistent medical care rather than avoiding doctors. Insurance companies view regular checkups and managed chronic conditions more favorably than gaps in medical care suggesting undiagnosed problems. If you use tobacco, quitting for 12 months typically qualifies you for non-tobacco rates, potentially cutting premiums in half.
Special Considerations for Different Life Stages
Life and critical illness cover needs evolve throughout your life based on changing financial responsibilities and health risks. Tailoring coverage to your specific life stage ensures appropriate protection without paying for unnecessary coverage.
Young Families and Working Parents
Parents with young children face the highest financial vulnerability if critical illness or death occurs. Mortgage obligations, childcare costs, and decades of lost income create substantial replacement needs. This life stage typically requires maximum life insurance coverage amounts combined with meaningful critical illness protection.
Consider coverage lasting until your youngest child reaches financial independence, usually 20 to 25 years from birth. Critical illness coverage proves particularly valuable during these years when you're building wealth and haven't yet accumulated substantial savings. A health crisis forcing extended work absence could derail college savings, retirement contributions, and debt payoff plans.
Young families often benefit from term life insurance paired with standalone critical illness coverage. This combination maximizes total protection during peak need years at affordable premium costs.
Pre-Retirement and Empty Nesters
As children become independent and mortgages approach payoff, life insurance needs typically decrease. However, critical illness risks increase with age, making this coverage potentially more valuable than in younger years. Many people in their 50s and early 60s shift their insurance focus from maximum death benefits toward health-related coverage.
Pre-retirement insurance priorities include:
- Maintaining enough life insurance to replace remaining working years income
- Covering any remaining mortgage balance and other debts
- Ensuring critical illness coverage bridges the gap to Medicare eligibility
- Protecting retirement savings from early withdrawal due to health crises
- Considering permanent life insurance for estate planning purposes
Residents throughout the Triad Area should evaluate how their existing coverage aligns with approaching retirement needs. Converting term policies to permanent coverage becomes more difficult after age 65, making this decision important during late working years.
Retirees and Medicare-Eligible Individuals
Once Medicare eligibility begins at age 65, health insurance costs stabilize but critical illness financial risks persist. Medicare covers many medical expenses but includes substantial cost-sharing through deductibles, copayments, and coinsurance. Critical illness coverage can help manage these out-of-pocket costs alongside non-medical expenses during serious health events.
Life insurance needs in retirement often focus on final expense coverage, estate liquidity for taxes, or legacy planning rather than income replacement. Smaller permanent life insurance policies serve these purposes effectively without the higher premiums required for large term policies at advanced ages.
Integration with Other Insurance Coverage
Life and critical illness cover work alongside other insurance policies in your overall financial protection strategy. Understanding how these different coverage types interact helps you avoid gaps while preventing unnecessary duplication.
Coordination with Health Insurance
Health insurance covers medical bills up to your out-of-pocket maximum, while critical illness coverage provides cash payments you control regardless of medical expenses. These serve complementary rather than overlapping purposes. Your health insurance might cover $200,000 in cancer treatment costs, but critical illness coverage provides funds for mortgage payments, lost income, experimental treatments, and other expenses during your recovery.
Higher deductible health plans increase the value of critical illness coverage since you face more initial out-of-pocket costs before your health insurance provides significant benefits. Families with high-deductible plans often need larger critical illness coverage amounts to bridge this gap effectively.
Disability Insurance Considerations
Disability insurance replaces a portion of your income when injury or illness prevents you from working. Critical illness coverage provides a lump-sum payment upon diagnosis of specific conditions regardless of whether you can work. Both address income protection but trigger under different circumstances and pay benefits differently.
Short-term and long-term disability insurance typically replace 50% to 70% of pre-disability income on a monthly basis during the disability period. Critical illness coverage pays the full benefit immediately upon diagnosis, even if you return to work quickly. Many financial planners recommend both types of coverage for comprehensive protection, with disability insurance protecting income during any medical condition preventing work and critical illness coverage providing immediate lump-sum resources for serious diagnoses.
Medicare Supplement and Advantage Plans
For Medicare-eligible individuals, Medicare supplement plans reduce cost-sharing under Original Medicare but don't provide lump-sum payments for critical illness diagnoses. Critical illness coverage remains valuable alongside Medicare by covering non-medical expenses and providing financial flexibility during serious health events.
Some Medicare Advantage plans include limited critical illness benefits as supplemental coverage, though these typically provide smaller benefits than standalone critical illness policies. Review your Medicare Advantage plan's critical illness rider carefully, as coverage amounts often range from just $5,000 to $25,000, which may not adequately address your needs.
Making Informed Coverage Decisions
Selecting appropriate life and critical illness cover requires evaluating your unique financial situation, health risks, and family circumstances. A systematic approach helps you identify the right coverage types and amounts for your needs.
Assessing Your Protection Gaps
Begin by inventorying existing coverage through employer benefits, individual policies, and government programs. Calculate the financial impact of critical illness by estimating how long you could maintain your current lifestyle using savings if unable to work for 6, 12, or 18 months. Factor in your health insurance deductible and out-of-pocket maximum that you'd need to pay during serious illness treatment.
For life insurance needs assessment, total all debts, ongoing financial obligations, and future expenses your family would face without your income. Subtract existing life insurance coverage and liquid assets that could address these needs. The remaining gap represents your additional life insurance need.
| Financial Obligation | Amount | Coverage Source | Gap |
|---|---|---|---|
| Mortgage Balance | $225,000 | Current life insurance: $150,000 | $75,000 |
| 5 Years Income | $350,000 | Savings: $40,000 | $310,000 |
| Education Fund | $100,000 | 529 Plan: $30,000 | $70,000 |
| Emergency Fund | $50,000 | None | $50,000 |
| Total Gap | $505,000 |
Working with Insurance Professionals
Navigating life and critical illness cover options becomes significantly easier with experienced guidance. Independent insurance professionals can compare policies across multiple carriers, identifying the best value for your specific situation. They understand underwriting requirements and can suggest strategies for challenging health situations.
Look for advisors who take time to understand your complete financial picture rather than immediately recommending products. Quality advisors should explain policy differences, help you understand complex terms and conditions, and provide personalized coverage recommendations based on your budget and needs.
For residents in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, working with local insurance professionals familiar with regional factors provides additional value. They understand local cost-of-living considerations, typical housing costs, and common employer benefit packages in your area.
Policy Review and Updates
Life and critical illness cover needs change as your life circumstances evolve. Schedule annual policy reviews to ensure coverage remains appropriate for your current situation. Major life events like marriage, divorce, childbirth, home purchases, or job changes should trigger immediate coverage evaluation.
Many term policies include conversion options allowing you to change to permanent coverage without new medical underwriting. These conversion periods typically end at age 65 or before, making it important to exercise these options before they expire if permanent coverage aligns with your goals.
Understanding Claims and Benefits Payment
Knowing how to file claims and what to expect during the benefits process ensures you can access your life and critical illness cover when needed. Both types of coverage have specific requirements that must be met for successful claims.
Critical Illness Claims Process
Filing a critical illness claim begins with medical diagnosis of a covered condition by a qualified physician. Your insurance company requires comprehensive medical documentation including diagnostic test results, pathology reports, and physician statements confirming the diagnosis meets policy definitions.
Steps in the critical illness claims process:
- Notify your insurance company of the diagnosis promptly
- Complete required claim forms provided by the insurer
- Authorize release of medical records to the insurance company
- Submit all requested documentation and physician statements
- Await claim review and approval (typically 30-60 days)
- Receive lump-sum benefit payment via check or direct deposit
The survival period requirement means you must live a specified number of days after diagnosis before benefits become payable. Most policies require 14 to 30 days of survival. This prevents claims for immediately terminal diagnoses where the policyholder passes away within days.
Life Insurance Claims Requirements
Life insurance claims require submitting a certified death certificate along with the original policy or policy number to the insurance company. Beneficiaries complete claim forms providing their contact information and preferred payment method. The insurance company verifies the death certificate, confirms the policy remained in force, and reviews for any contestability period issues.
During the first two years of coverage (the contestability period), insurance companies can investigate claims more thoroughly, reviewing the application for material misrepresentations. Claims filed after this period typically process much faster with fewer investigations.
Most life insurance claims process within 30 to 60 days if all documentation is properly submitted. Beneficiaries can usually choose between lump-sum payment or structured payment options depending on their financial needs and the insurance company's available settlement options.
Tax Implications and Financial Planning Integration
Understanding the tax treatment of life and critical illness cover benefits helps you plan effectively and maximize the value of your coverage. Generally favorable tax treatment makes these insurance products even more valuable in comprehensive financial plans.
Tax-Free Benefit Payments
Life insurance death benefits paid to beneficiaries are income tax-free under current federal law. This means a $500,000 life insurance policy pays the full $500,000 to beneficiaries without reduction for income taxes. However, interest earned on death benefits paid in installments may be taxable.
Critical illness benefit payments also receive favorable tax treatment, generally qualifying as tax-free reimbursement for medical expenses under IRS guidelines. The IRS typically doesn’t consider these benefits taxable income since they reimburse or compensate for loss related to injury or illness. This favorable treatment applies to individually owned policies, though employer-paid critical illness coverage may have different tax implications.
Estate Planning Considerations
Large life insurance policies can create estate tax concerns for high-net-worth individuals. Life insurance death benefits are included in your taxable estate if you own the policy at death. For estates exceeding federal estate tax exemptions (currently $13.61 million in 2026), this could trigger substantial estate taxes.
Irrevocable life insurance trusts (ILITs) provide a solution by removing life insurance from your taxable estate while maintaining benefits for your heirs. These trusts own the life insurance policy, receive death benefits, and distribute proceeds according to trust terms without estate tax inclusion.
Premium Payment Strategies
Paying life and critical illness cover premiums requires balancing adequate coverage with budget constraints. Annual payment modes often provide discounts compared to monthly premiums, potentially saving 5% to 8% annually. However, monthly payments help many families manage cash flow more effectively despite the slight premium increase.
Some permanent life insurance policies offer premium financing options for high-net-worth individuals purchasing large policies. Third-party lenders provide loans to pay premiums, with the death benefit eventually repaying the loan. This strategy requires careful analysis and professional guidance but can provide significant coverage leverage in certain situations.
Life and critical illness cover provides essential financial protection that addresses different but equally important risks your family faces. Understanding how these coverage types work together and selecting appropriate amounts for your situation ensures comprehensive protection during life's most challenging moments. Whether you need guidance evaluating your current coverage, comparing policy options, or understanding how Medicare and other benefits integrate with life and critical illness cover, Moser Insurance Group Inc provides personalized support throughout the Triad Area. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your insurance needs with experienced professionals who focus on education and clarity without pressure.
Recent Comments