

Choosing the right health care plans can feel overwhelming, especially with the variety of options available today. Whether you're turning 65, changing jobs, or shopping during open enrollment, understanding how different plans work is essential to protecting your health and finances. In the Triad Area of North Carolina-including Greensboro, Kernersville, High Point, and Winston Salem-families and individuals need coverage that fits both their medical needs and their budgets. This guide breaks down everything you need to know about selecting health care plans that provide real value and peace of mind.
Understanding Different Types of Health Care Plans
The landscape of health care plans includes several distinct categories, each designed to serve different needs and preferences. Knowing how these plan types function helps you make informed decisions about your coverage.
Major Medical Insurance Plans
Major medical insurance represents the foundation of comprehensive coverage. These health care plans protect against catastrophic medical expenses while covering routine care, preventive services, and prescription medications. Different plan types offer varying levels of flexibility when choosing doctors and specialists.
Key plan structures include:
- Health Maintenance Organizations (HMOs): Lower premiums with required primary care physician coordination
- Preferred Provider Organizations (PPOs): Higher flexibility to see specialists without referrals
- Exclusive Provider Organizations (EPOs): No out-of-network coverage except emergencies
- Point of Service (POS) Plans: Hybrid approach combining HMO and PPO features
Each structure balances cost against convenience differently. HMOs typically offer the lowest monthly premiums but require staying within network. PPOs cost more but allow greater freedom in choosing providers.
Government-Sponsored Health Care Plans
Medicare and Medicaid serve specific populations with unique needs. Medicare provides coverage for individuals 65 and older, plus certain younger people with disabilities. If you're approaching 65 in the Triad Area, understanding Medicare options becomes critical for seamless transition from employer or marketplace coverage.
Medicaid offers coverage for eligible low-income individuals and families. Each state administers its own program within federal guidelines, creating variations in benefits and enrollment requirements.
The Medicare health plans landscape includes Original Medicare (Parts A and B), Medicare Advantage Plans (Part C), and prescription drug coverage (Part D). Many beneficiaries supplement Original Medicare with additional policies to reduce out-of-pocket costs.
Metal Tier Categories and Cost-Sharing
The Affordable Care Act established metal tier categories to help consumers compare health care plans more easily. These tiers-Bronze, Silver, Gold, and Platinum-indicate how costs are shared between you and your insurance company.
| Metal Tier | Insurer Pays | You Pay | Monthly Premium | Best For |
|---|---|---|---|---|
| Bronze | 60% | 40% | Lowest | Healthy individuals, emergency coverage |
| Silver | 70% | 30% | Moderate | Most people, eligible for subsidies |
| Gold | 80% | 20% | Higher | Frequent medical care needs |
| Platinum | 90% | 10% | Highest | Significant ongoing health expenses |
Bronze plans make sense if you're generally healthy and want protection against worst-case scenarios. You'll pay less each month but face higher costs when receiving care. Platinum plans work well if you have chronic conditions requiring regular treatment, prescriptions, or specialist visits.
Silver plans deserve special attention because they're the only tier where cost-sharing reductions apply for eligible individuals. These reductions lower deductibles, copayments, and coinsurance amounts-making care more affordable when you need it.
Calculating Total Healthcare Costs
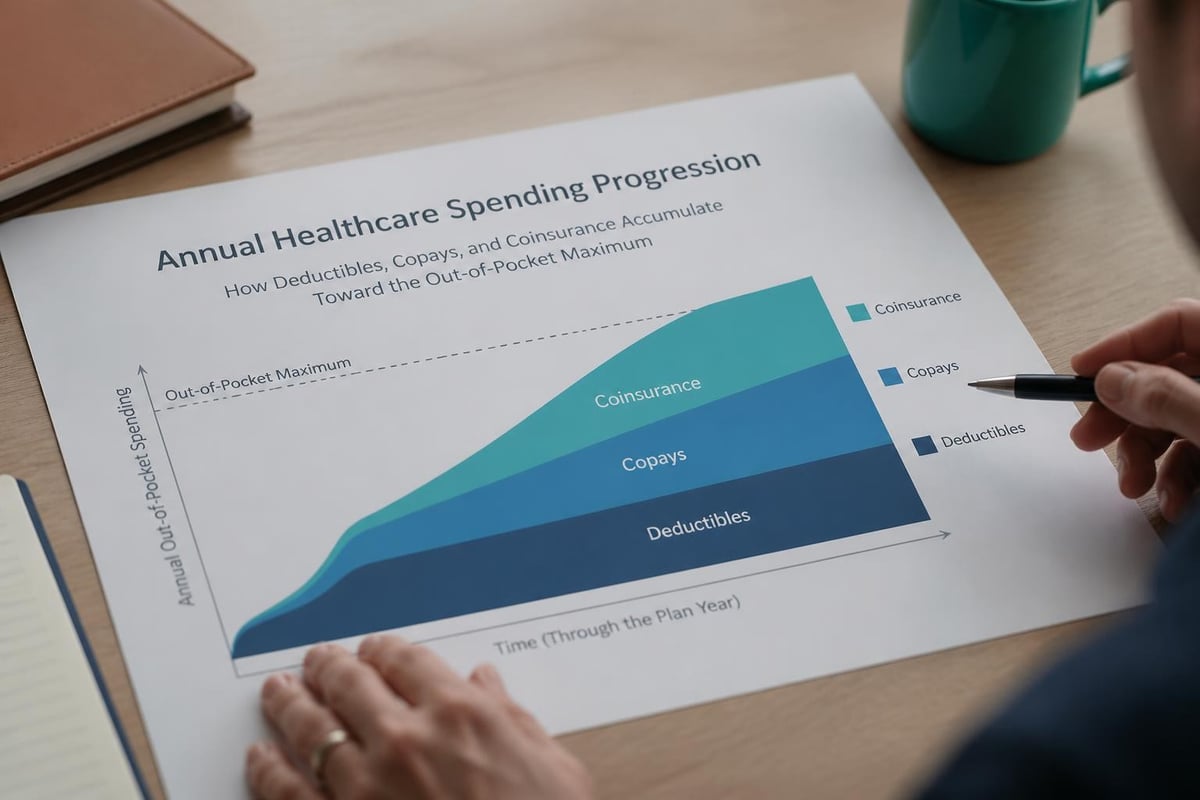
Monthly premiums represent just one piece of your total healthcare expenses. When evaluating health care plans, consider the complete financial picture.
Essential cost components:
- Monthly premium: Your regular insurance payment
- Annual deductible: Amount you pay before insurance starts covering costs
- Copayments: Fixed fees for specific services (office visits, prescriptions)
- Coinsurance: Percentage of costs you pay after meeting your deductible
- Out-of-pocket maximum: The most you'll pay in a year before full coverage kicks in
A plan with a $300 monthly premium and $2,000 deductible might cost less overall than one with a $200 premium and $7,000 deductible-especially if you anticipate needing regular medical care. Run the numbers based on your expected usage.
Evaluating Network Coverage and Provider Access
Network size significantly impacts both convenience and costs. Health care plans contract with specific doctors, hospitals, and specialists to create their networks. Staying in-network saves money because providers have agreed to discounted rates.
Before enrolling, verify that your preferred providers participate in the plan's network. This becomes particularly important if you have established relationships with specialists or receive ongoing treatment. In Greensboro, Kernersville, High Point, and Winston Salem, network configurations vary widely among carriers.
Checking Provider Directories
Most insurers maintain online provider directories, but these aren't always updated in real-time. The most reliable approach involves calling your doctor's office directly to confirm their participation in specific health care plans you're considering.
Ask these questions when verifying coverage:
- Does the doctor accept this insurance plan?
- Are they accepting new patients with this insurance?
- Will this be considered in-network coverage?
- Are there any restrictions on services covered?
Getting written confirmation protects you from surprise bills later. Provider networks change throughout the year, so annual verification during open enrollment prevents disruptions in care.
Understanding Prescription Drug Coverage
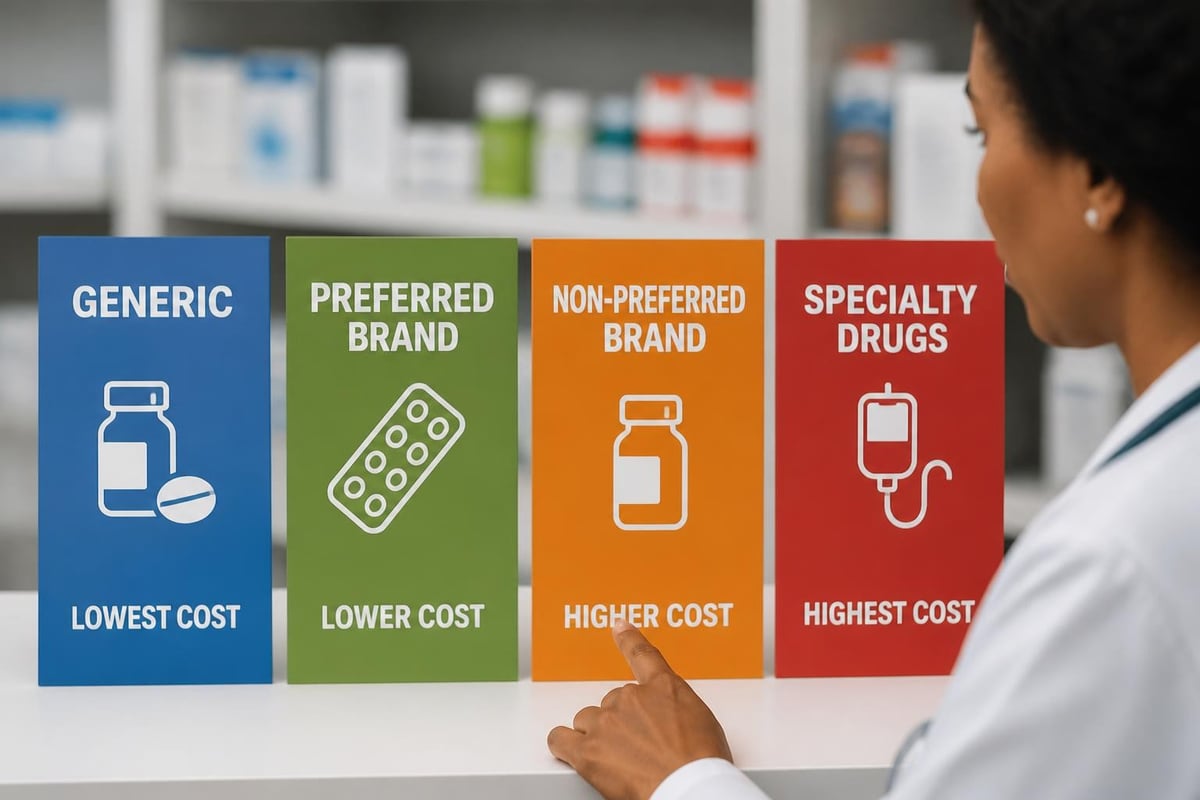
Prescription drug coverage varies dramatically across health care plans. Most plans organize medications into tiers, with different costs for each level. Generic drugs typically occupy Tier 1 with the lowest copays, while specialty medications might sit in Tier 4 or 5 with significantly higher costs.
Typical formulary structure:
- Tier 1: Generic medications ($10-$20 copay)
- Tier 2: Preferred brand-name drugs ($30-$50 copay)
- Tier 3: Non-preferred brand-name drugs ($60-$100 copay)
- Tier 4: Specialty medications (20-33% coinsurance)
Check whether your current prescriptions appear on the plan's formulary-the list of covered medications. Some health care plans require prior authorization for certain drugs, meaning your doctor must justify medical necessity before insurance approves coverage.
Preventive Care and Wellness Benefits
All ACA-compliant health care plans must cover preventive services at 100% with no cost-sharing. This means you pay nothing for covered preventive care, even if you haven't met your deductible.
Covered preventive services include:
- Annual physical examinations
- Immunizations and vaccines
- Cancer screenings (mammograms, colonoscopies)
- Blood pressure and cholesterol testing
- Depression and diabetes screening
- Well-child visits and developmental screenings
Taking advantage of these benefits helps catch health issues early when they're most treatable and least expensive. Many plans also offer wellness programs with incentives for healthy behaviors like gym membership discounts or smoking cessation support.
Comparing Plans During Open Enrollment
Open enrollment represents your annual opportunity to change health care plans without qualifying life events. For marketplace plans, this period typically runs from November 1 through January 15. Medicare has different enrollment windows, particularly important when you're applying for Medicare for the first time.
Comparing health care plans requires examining multiple factors simultaneously. Create a spreadsheet tracking premiums, deductibles, out-of-pocket maximums, and network coverage for your top choices.
The Summary of Benefits and Coverage Document
Every health plan must provide a Summary of Benefits and Coverage (SBC), a standardized document explaining what the plan covers and what it costs. These summaries use consistent formatting, making side-by-side comparisons straightforward.
The SBC includes coverage examples showing how the plan would handle common medical scenarios like having a baby or managing type 2 diabetes. These examples help you understand real-world costs beyond abstract terms like deductibles and coinsurance.
Special Enrollment Periods and Life Changes
While open enrollment serves most people, certain qualifying life events trigger special enrollment periods allowing you to change health care plans mid-year. These events disrupt your current coverage situation, creating legitimate need for immediate changes.
Qualifying life events include:
- Marriage or divorce
- Birth or adoption of a child
- Loss of other health coverage
- Moving to a new coverage area
- Changes in household income affecting subsidy eligibility
You typically have 60 days from the qualifying event to enroll in new coverage. Missing this window means waiting until the next open enrollment period unless another qualifying event occurs.
Financial Assistance and Subsidies
Many people qualify for financial help paying for health care plans through premium tax credits and cost-sharing reductions. These subsidies make coverage more affordable for individuals and families with moderate incomes.
Premium tax credits lower your monthly insurance payment. The amount depends on your household income relative to the federal poverty level. For 2026, individuals earning between $15,060 and $60,240 annually may qualify, with higher limits for larger families.
| Household Size | 100% FPL | 400% FPL (Max for Premium Credits) |
|---|---|---|
| 1 person | $15,060 | $60,240 |
| 2 people | $20,440 | $81,760 |
| 3 people | $25,820 | $103,280 |
| 4 people | $31,200 | $124,800 |
Cost-sharing reductions only apply to Silver-level health care plans purchased through the marketplace. These reductions lower your deductibles and copayments, making medical care more affordable when you actually use it. Eligibility extends to households earning up to 250% of the federal poverty level.
Plan Quality Ratings and Accreditation
Not all health care plans deliver the same quality of care or customer service. Quality ratings for health plans help consumers identify high-performing options based on objective measures.
The National Committee for Quality Assurance (NCQA) evaluates plans using standardized criteria. Their health plan report cards assess performance in categories like preventive care, treatment effectiveness, and member satisfaction.
Plans earn ratings from one to five stars based on their performance. Higher-rated health care plans demonstrate better outcomes for members, more effective chronic disease management, and superior customer service.
Accreditation Standards
Health plan accreditation indicates that independent organizations have verified a plan meets national quality standards. Accredited plans undergo rigorous evaluation of their policies, procedures, and outcomes.
While accreditation doesn't guarantee perfection, it provides assurance that the plan follows evidence-based practices and maintains systems for continuous improvement. This matters most for health care plans serving people with complex medical needs requiring coordinated care.
Understanding Out-of-Pocket Maximums
The out-of-pocket maximum represents the most you'll pay for covered services in a plan year. Once you reach this limit, your insurance pays 100% of covered costs for the remainder of the year. For 2026, ACA-compliant health care plans cannot exceed $9,450 for individuals or $18,900 for families.
This protection proves invaluable during medical emergencies or when managing serious illnesses. If you're diagnosed with cancer requiring surgery, chemotherapy, and radiation, your costs stop accumulating once you hit the out-of-pocket maximum-regardless of how expensive treatment becomes.
Important notes about out-of-pocket limits:
- Monthly premiums don't count toward the maximum
- Out-of-network care may not count in some plans
- Separate maximums apply for in-network versus out-of-network services in some plans
- The limit resets each plan year
Plans with lower out-of-pocket maximums cost more monthly but provide greater financial protection. Consider your risk tolerance and ability to handle unexpected medical expenses when choosing between health care plans.
Coordination of Benefits with Other Coverage
Some people have access to multiple health care plans simultaneously-perhaps through both spouses' employers or through a combination of employer coverage and Medicare. Understanding how coordination of benefits works prevents confusion and ensures claims process correctly.
Primary coverage pays first according to its benefits and cost-sharing rules. Secondary coverage may pay some or all of the remaining costs, depending on the plan's coordination rules. The combined benefits from both plans cannot exceed 100% of covered charges.
When you have both employer coverage and Medicare, specific rules determine which pays primary. If your employer has 20 or more employees, the group plan typically pays primary. For smaller employers, Medicare usually serves as primary coverage.
Employer-Sponsored Health Care Plans
Most Americans under 65 receive coverage through employer-sponsored health care plans. These group plans often provide better value than individual coverage because employers negotiate rates for large groups and typically pay a substantial portion of premiums.
Employer plans must comply with federal regulations including coverage of essential health benefits and preventive services. However, they operate outside the marketplace system, so you can't use premium tax credits even if your income would otherwise qualify.
If your employer offers coverage meeting minimum value and affordability standards, you're generally not eligible for marketplace subsidies. The plan meets minimum value if it covers at least 60% of total healthcare costs. It's affordable if your premium for self-only coverage doesn't exceed 8.39% of household income in 2026.
COBRA and Coverage Continuation
When you lose employer-sponsored coverage due to job loss or reduced hours, COBRA allows you to continue the same health care plans temporarily. You'll pay the full premium plus a 2% administrative fee-typically much higher than your employee contribution.
COBRA coverage lasts up to 18 months in most cases, or 36 months for qualifying events like divorce or a dependent aging out. While expensive, COBRA can be valuable if you're mid-treatment or want to maintain relationships with current providers while transitioning to new coverage.
Losing employer coverage qualifies you for a special enrollment period in the marketplace. In many cases, you'll find more affordable health care plans through the exchange, especially if you qualify for premium subsidies based on your new income level.
Health Savings Accounts and Tax Advantages
High-deductible health care plans paired with Health Savings Accounts (HSAs) offer significant tax advantages for healthy individuals comfortable with higher out-of-pocket costs. HSAs provide triple tax benefits: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are never taxed.
For 2026, HSA-qualified plans must have minimum deductibles of $1,650 for individuals or $3,300 for families. Out-of-pocket maximums cannot exceed $8,300 for individuals or $16,600 for families. These limits are lower than standard ACA maximums, providing additional protection.
HSA contribution limits for 2026:
- Individual coverage: $4,300
- Family coverage: $8,550
- Catch-up contribution (age 55+): Additional $1,000
Money in HSAs rolls over year after year, unlike flexible spending accounts. Many people use HSAs as supplemental retirement savings vehicles, paying medical expenses out-of-pocket while allowing the account to grow tax-free for decades.
Short-Term Health Insurance Limitations
Short-term health insurance plans marketed as affordable alternatives to comprehensive coverage come with significant limitations. These health care plans don't comply with ACA regulations, meaning they can deny coverage based on pre-existing conditions, exclude essential health benefits, and impose annual or lifetime coverage limits.
While premiums appear attractive, short-term plans often prove inadequate when serious illness or injury occurs. They typically exclude maternity care, mental health services, and prescription drug coverage. Pre-existing condition exclusions can deny claims for any condition you had symptoms of before coverage started-even if undiagnosed.
Most insurance professionals recommend short-term plans only for very specific situations like brief gaps between jobs when COBRA seems too expensive. They're not suitable as long-term solutions because they don't provide the comprehensive protection most families need.
Supplemental Insurance Options
Even comprehensive health care plans may leave coverage gaps that supplemental insurance can fill. Hospital indemnity plans pay cash benefits directly to you when hospitalized, helping cover deductibles, lost income, or other expenses your primary insurance doesn't handle.
These supplemental policies work alongside your primary coverage. Critical illness insurance pays lump sums if you're diagnosed with specific serious conditions like cancer, heart attack, or stroke. Accident insurance covers costs related to accidental injuries, often with no deductible.
While not necessary for everyone, supplemental coverage makes sense if you have high deductibles, limited savings, or concerns about missing work during illness. The monthly costs are typically modest compared to the financial protection provided during serious health events.
Dental and Vision Coverage Considerations
Most health care plans don't include comprehensive dental or vision coverage. While pediatric dental and vision benefits are essential health benefits under the ACA, adult coverage is optional in many plans. You often need separate policies for these services.
Dental insurance typically covers preventive care like cleanings and X-rays at 100%, basic procedures like fillings at 70-80%, and major services like crowns or root canals at 50%. Annual maximums often range from $1,000 to $2,000, which may not cover extensive work.
Vision plans reduce costs for routine eye exams, glasses, and contact lenses. If you wear corrective lenses, standalone vision coverage usually pays for itself quickly. Some health care plans include vision benefits or offer them as optional add-ons during enrollment.
For more information about supplemental coverage options for dental, vision, and hearing, explore how these benefits support overall wellness.
Making Your Decision
Selecting among health care plans requires balancing multiple priorities: affordability, comprehensive coverage, provider access, and prescription drug benefits. No single plan works best for everyone-the right choice depends on your specific health needs, financial situation, and personal preferences.
Start by listing your must-haves: specific doctors, regular medications, or anticipated procedures. Eliminate health care plans that don't meet these requirements. Then compare costs using realistic projections of how much care you'll need throughout the year.
Consider both best-case and worst-case scenarios. What happens if you stay healthy and use only preventive care? What if you face a serious diagnosis requiring expensive treatment? Plans that minimize costs in both scenarios often represent the best value.
Don't hesitate to ask questions or seek expert guidance. Insurance professionals can explain confusing terms, verify provider participation, and help you understand how different health care plans would handle your specific situation. Having clarity before enrollment prevents frustration and unexpected costs later.
If you need personalized assistance navigating health care plans in North Carolina, you can reach out by phone at 336-862-1763, email at moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com for more information.
Understanding health care plans empowers you to make confident coverage decisions that protect both your health and your finances. The right plan balances monthly affordability with comprehensive protection, ensures access to trusted providers, and covers your medications at reasonable costs. At Moser Insurance Group Inc, we help individuals and families throughout the Triad Area-including Greensboro, Kernersville, High Point, and Winston Salem-understand their options without pressure or confusion. Whether you're comparing marketplace plans, transitioning to Medicare, or evaluating employer coverage, our team provides clear guidance tailored to your unique needs. Contact Moser Insurance Group Inc today to discuss which health care plans make the most sense for your situation.
Recent Comments