

Understanding the differences in Medicare plans can feel overwhelming when you're approaching age 65 or already enrolled. With multiple plan types, varying costs, and distinct coverage options available throughout the Triad Area including Greensboro, Kernersville, High Point, and Winston Salem, making the right choice requires clear information. Medicare offers several pathways to coverage, each designed to meet different healthcare needs and financial situations. This comprehensive guide breaks down the essential differences in Medicare plans so you can make confident decisions about your healthcare coverage.
Medicare Parts: The Foundation of Your Coverage
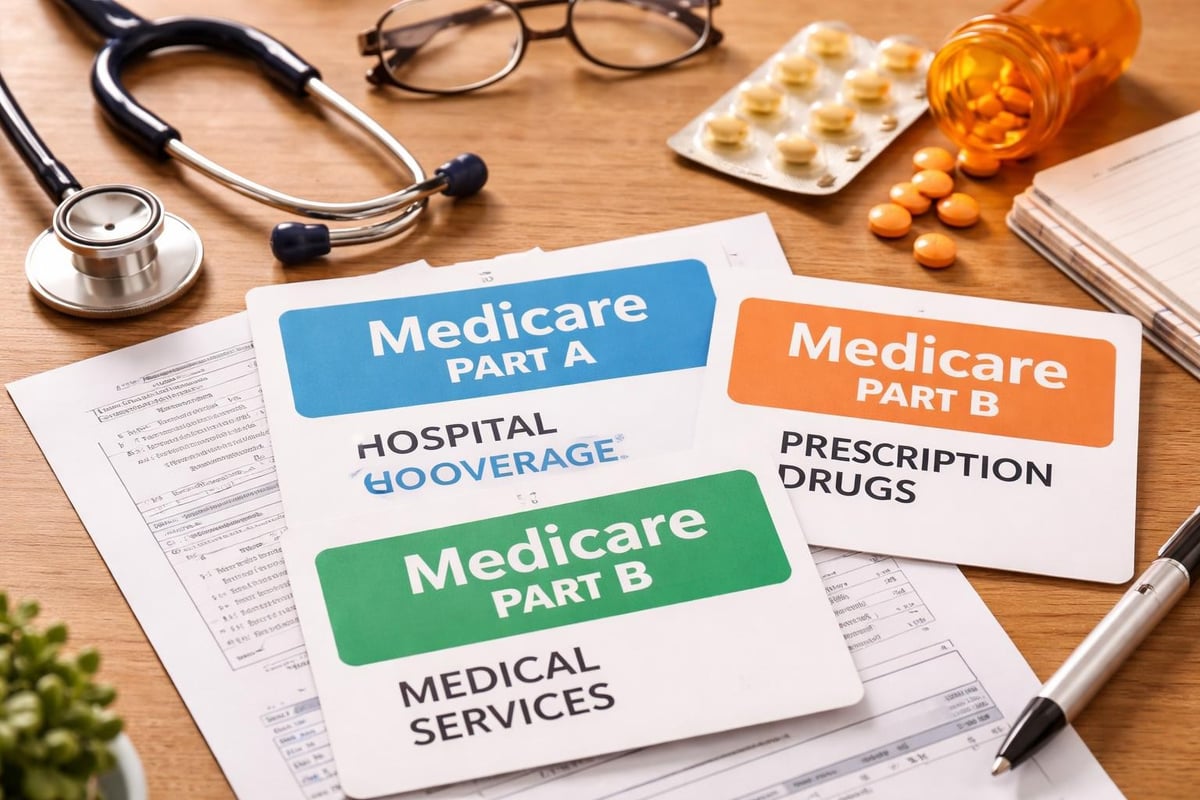
Medicare coverage starts with understanding the basic building blocks. Original Medicare consists of Part A and Part B, which together form the foundation of traditional coverage. Part A covers hospital stays, skilled nursing facility care, hospice care, and some home health services. Most people don't pay a premium for Part A if they or their spouse paid Medicare taxes while working.
Part B covers outpatient services, including doctor visits, preventive care, medical equipment, and some home health services. For 2026, Part B comes with a monthly premium that varies based on your income. According to Medicare cost projections for 2026, these premiums continue to adjust annually based on inflation and healthcare costs.
The Prescription Drug Component
Part D provides prescription drug coverage and represents another critical element when comparing differences in Medicare plans. This optional coverage helps reduce the cost of medications, both generic and brand-name. You can add Part D to Original Medicare or find it included in many Medicare Advantage plans.
Key Part D features include:
- Monthly premiums that vary by plan and income
- Annual deductibles before coverage begins
- Coverage gap (donut hole) where you pay more
- Catastrophic coverage after reaching spending limits
Original Medicare Versus Medicare Advantage
One of the most significant differences in Medicare plans involves choosing between Original Medicare and Medicare Advantage (Part C). This decision affects everything from which doctors you can see to how much you'll pay out-of-pocket. Understanding how Original Medicare works provides essential context for this comparison.
Original Medicare allows you to visit any doctor or hospital that accepts Medicare nationwide. You'll typically pay 20% of Medicare-approved costs after meeting your deductible, with no annual out-of-pocket maximum. This traditional option offers maximum flexibility but requires additional coverage for prescription drugs and may benefit from supplemental insurance.
Medicare Advantage Plan Characteristics
Medicare Advantage plans bundle Part A, Part B, and usually Part D into one comprehensive package offered by private insurance companies. These plans operate differently from Original Medicare in several fundamental ways.
| Feature | Original Medicare | Medicare Advantage |
|---|---|---|
| Provider Network | Any Medicare provider | Network restrictions apply |
| Out-of-Pocket Max | None | Annual limit included |
| Drug Coverage | Requires separate Part D | Often included |
| Extra Benefits | Limited | May include dental, vision, hearing |
| Prior Authorization | Rarely needed | Often required |
Medicare Advantage plans typically use networks of doctors and hospitals in areas like Greensboro, High Point, Winston Salem, and Kernersville. You'll need to choose providers within your plan's network or pay higher costs for out-of-network care. However, recent industry changes mean insurers are scaling back Medicare Advantage offerings for 2026, which may affect available options in your area.
Medigap Supplemental Insurance
Medigap policies represent another category when examining differences in Medicare plans. These supplemental plans work exclusively with Original Medicare to cover gaps in coverage. Private insurance companies sell standardized Medigap policies labeled with letters (Plan A, Plan B, Plan G, Plan N, etc.), and each letter represents a specific set of benefits.
The most popular Medigap options include:
- Plan G – Covers nearly everything except the Part B deductible
- Plan N – Requires copays for doctor visits and emergency room visits
- Plan F – Comprehensive coverage (only available to those eligible before 2020)
- High Deductible Plan G – Lower premiums with higher deductible
Medigap policies help manage healthcare costs by covering copayments, coinsurance, and deductibles that Original Medicare doesn't pay. Choosing the best Medigap plan depends on your health status, budget, and how frequently you use medical services.
Medigap Enrollment Timing
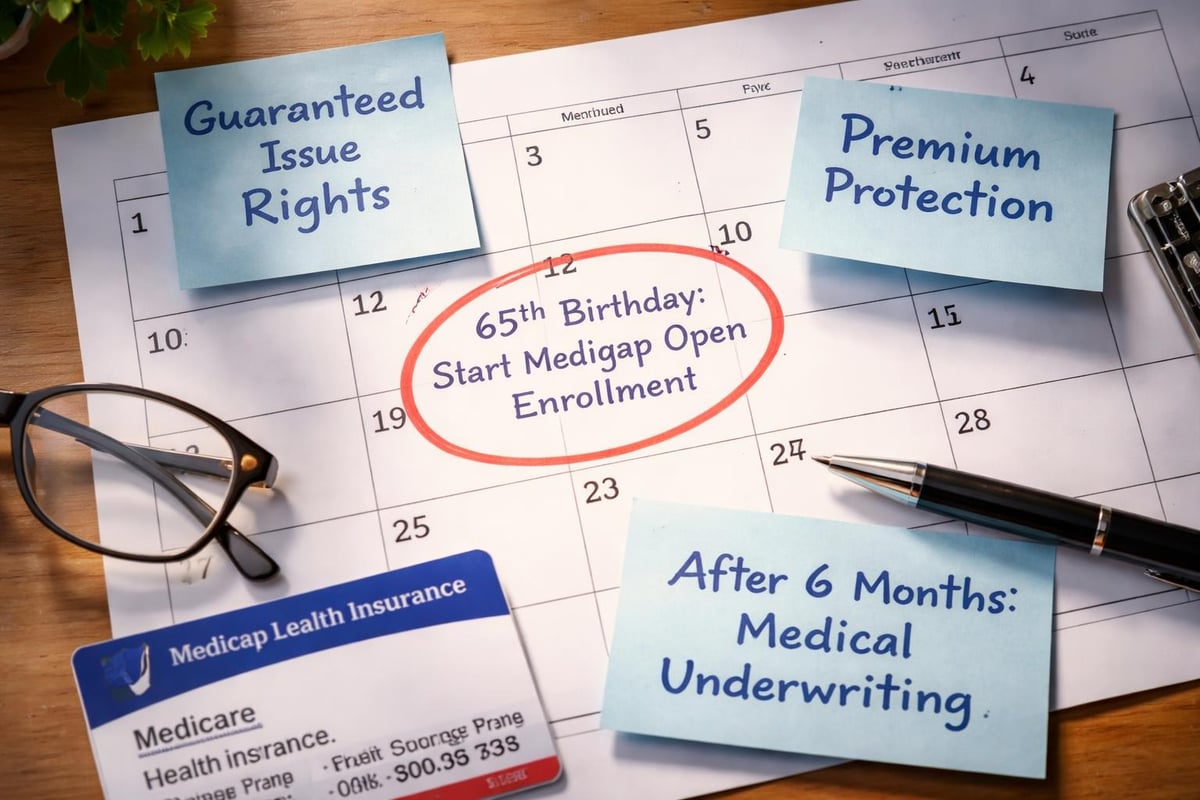
Your Medigap open enrollment period begins the month you turn 65 and are enrolled in Part B. During this six-month window, insurance companies cannot deny you coverage or charge higher premiums based on health conditions. This guaranteed issue right makes timing crucial when considering differences in Medicare plans.
Outside this initial enrollment period, you may face medical underwriting, higher premiums, or coverage denials. Understanding these timing rules helps residents throughout the Triad Area secure the coverage they need without unnecessary complications.
Cost Structures Across Plan Types
Financial considerations create some of the most important differences in Medicare plans. Each plan type structures costs differently, affecting your monthly budget and potential out-of-pocket expenses. Understanding these variations helps you project annual healthcare spending more accurately.
Original Medicare Costs
When you choose Original Medicare, you'll encounter several cost components:
- Part A deductible for each benefit period ($1,632 in 2026)
- Part B premium (standard amount plus income adjustments)
- Part B deductible ($240 annually in 2026)
- 20% coinsurance on most Part B services
- Part D premium if you add drug coverage
- Medigap premium if you purchase supplemental coverage
These costs can add up quickly without supplemental coverage. Many people in Greensboro, Winston Salem, and surrounding communities choose Medigap policies specifically to manage these expenses and create predictable monthly budgets.
Medicare Advantage Cost Framework
Medicare Advantage plans structure expenses differently than Original Medicare. You'll still pay your Part B premium, but additional costs include:
- Monthly plan premium (some plans have $0 premiums)
- Annual deductible (varies by plan)
- Copayments for doctor visits and services
- Coinsurance for hospital stays
- Out-of-pocket maximum (caps your annual spending)
| Cost Element | Typical Range | When You Pay |
|---|---|---|
| Monthly Premium | $0-$100+ | Every month |
| Primary Care Copay | $0-$25 | Each visit |
| Specialist Copay | $30-$70 | Each visit |
| Hospital Daily Copay | $100-$350 | Per day (limited days) |
| Out-of-Pocket Max | $3,000-$8,000 | After accumulated costs |
The out-of-pocket maximum provides important protection that Original Medicare lacks. Once you reach this limit, your plan covers 100% of additional costs for the rest of the year.
Network and Provider Flexibility
Access to healthcare providers represents another crucial factor when evaluating differences in Medicare plans. Where you receive care and which doctors you can see varies dramatically between plan types, particularly for residents of High Point, Kernersville, and the broader Triad Area.
Original Medicare provides maximum flexibility. You can visit any doctor or hospital in the United States that accepts Medicare assignment. No referrals are needed to see specialists, and you don't need to stay within a network. This freedom appeals to people who travel frequently, have complex medical conditions requiring multiple specialists, or prefer established relationships with specific providers.
Medicare Advantage plans typically limit provider access through networks:
- HMO plans require you to use network providers except emergencies
- PPO plans allow out-of-network care at higher costs
- PFFS plans let you see any Medicare provider accepting the plan's terms
- SNP plans serve specific populations with tailored networks
Before choosing a Medicare Advantage plan, verify that your preferred doctors and hospitals in Greensboro or Winston Salem participate in the network. Provider networks can change annually, so checking the find care providers directory helps ensure continued access.
Coverage Extras and Additional Benefits
The differences in Medicare plans become particularly apparent when examining additional benefits beyond basic medical coverage. These extras can significantly impact your overall healthcare experience and costs, especially for services Original Medicare doesn't cover.
Medicare Advantage Additional Benefits
Many Medicare Advantage plans include benefits not available through Original Medicare:
- Routine dental cleanings and basic procedures
- Annual vision exams and eyewear allowances
- Hearing aids and hearing exams
- Fitness memberships and wellness programs
- Over-the-counter medication allowances
- Transportation to medical appointments
- Meal delivery after hospital discharge
- Telehealth services with $0 copays
These additional benefits make Medicare Advantage attractive for people who need dental, vision, or hearing care. However, these benefits often come with limitations, waiting periods, or network restrictions.
Original Medicare with Supplements
Original Medicare combined with Medigap doesn't typically include dental, vision, or hearing coverage. You'll need to purchase separate standalone policies for these services. However, this combination excels at covering traditional medical expenses without network restrictions.
For comprehensive protection in High Point or Kernersville, many beneficiaries combine:
- Original Medicare (Parts A and B)
- Medigap supplement (like Plan G)
- Part D prescription drug plan
- Separate dental and vision policies
This approach costs more in monthly premiums but eliminates most out-of-pocket medical expenses and provides unlimited provider choice.
Prescription Drug Coverage Variations
Understanding how different plans handle prescription medications highlights important differences in Medicare plans. Drug coverage affects both your monthly costs and access to needed medications, making it essential to compare options carefully.
Stand-alone Part D plans work with Original Medicare. You choose from dozens of plans available in your area, each with its own:
- Monthly premium
- Annual deductible
- Formulary (list of covered drugs)
- Pharmacy network
- Coverage tiers and cost-sharing
Each Part D plan organizes medications into tiers, with generic drugs typically costing less than brand-name medications. The specific drugs your plan covers and what you'll pay varies significantly between plans.
Medicare Advantage Drug Coverage
Most Medicare Advantage plans include integrated prescription drug coverage (MA-PD plans). This bundled approach simplifies administration since you work with one company for all coverage. However, the same formulary and tier structure applies, meaning your medications may cost more or less depending on which plan you choose.
Some Medicare Advantage plans don't include drug coverage. If you enroll in one of these plans, you can add a stand-alone Part D plan separately. Failing to maintain creditable drug coverage when you're eligible can result in late enrollment penalties.
Special Enrollment Periods and Plan Changes
The differences in Medicare plans extend to when and how you can change coverage. Understanding enrollment rules prevents gaps in coverage and helps you adjust plans as your healthcare needs evolve.
Initial enrollment periods for Medicare begin three months before your 65th birthday month and extend three months after. During this seven-month window, you can enroll in Original Medicare and add Part D, or choose Medicare Advantage. If you're new to Medicare, understanding these timelines ensures smooth coverage transitions.
Annual Open Enrollment
Medicare’s Annual Enrollment Period runs October 15 through December 7 each year. During this time, you can:
- Switch from Original Medicare to Medicare Advantage
- Move from Medicare Advantage back to Original Medicare
- Change Medicare Advantage plans
- Add, drop, or switch Part D plans
- Enroll in Medigap (subject to underwriting in most states)
Changes made during this period take effect January 1 of the following year. This annual opportunity allows you to reassess your coverage as your health needs, medication requirements, or financial situation changes.
Geographic Considerations for the Triad Area
Where you live significantly impacts available plan options and costs. Residents of Greensboro, Winston Salem, High Point, and Kernersville all have access to Medicare, but specific plan availability varies by ZIP code.
Medicare Advantage plans operate within specific service areas. A plan available in Winston Salem might not be offered in High Point, even though these cities are relatively close. Provider networks also differ by location, affecting which doctors and hospitals you can access.
Local factors affecting plan selection include:
- Number of Medicare Advantage plans in your county
- Availability of preferred provider networks
- Medigap pricing variations by location
- Part D premium differences between carriers
- Quality ratings for plans in your area
Working with a local insurance professional helps navigate these geographic variations. For personalized assistance understanding options in the Triad Area, contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com.
Making Your Medicare Plan Decision
Choosing among the differences in Medicare plans requires evaluating your unique situation. No single plan type works best for everyone, and the right choice depends on multiple factors specific to your circumstances.
Consider these questions when comparing options:
-
How important is provider choice? If you want to see any doctor without referrals, Original Medicare offers more flexibility.
-
What's your health status? People with chronic conditions requiring frequent specialist care may prefer different plans than healthy individuals needing mainly preventive services.
-
Do you take multiple medications? Prescription drug coverage varies significantly, making careful formulary comparison essential.
-
What's your risk tolerance? Are you comfortable with higher out-of-pocket costs but lower premiums, or do you prefer predictable monthly expenses?
-
Do you travel frequently? Coverage outside your local area differs substantially between Original Medicare and Medicare Advantage plans.
| Priority | Best Plan Type | Reason |
|---|---|---|
| Nationwide coverage | Original Medicare + Medigap | No networks, travel anywhere |
| Lower premiums | Medicare Advantage | Often $0 premium plans |
| Predictable costs | Original Medicare + Medigap G | Covers most out-of-pocket |
| Extra benefits | Medicare Advantage | Dental, vision, hearing included |
| Maximum provider choice | Original Medicare | Any Medicare provider |
Your answers to these questions guide you toward the plan category that aligns with your priorities. Remember that you can change plans annually during open enrollment if your needs shift.
Understanding the Role of Insurance Professionals
Navigating differences in Medicare plans becomes easier with expert guidance. Licensed insurance agents who specialize in Medicare can explain options specific to your situation without the pressure of misleading sales tactics.
Professional assistance helps you:
- Compare plans available in your ZIP code
- Understand how your doctors fit into different networks
- Calculate total annual costs under various scenarios
- Verify medication coverage across Part D plans
- Complete enrollment paperwork accurately
- Avoid common Medicare mistakes
At Moser Insurance Group Inc, we focus on education and personalized support for individuals and families throughout Greensboro, Winston Salem, High Point, and Kernersville. Our approach prioritizes helping you understand your options so you can make confident decisions. Visit moserinsurancegroup.com to learn more about our services.
Plan Quality and Performance Ratings
When comparing differences in Medicare plans, quality ratings provide objective measures of plan performance. Medicare assigns star ratings from one to five stars based on factors including customer satisfaction, prevention and treatment quality, and member complaints.
Higher-rated plans typically offer:
- Better customer service responsiveness
- Improved health outcomes for members
- Fewer member complaints
- Better preventive care compliance
- More satisfied beneficiaries
These ratings help you identify quality plans beyond just comparing costs and benefits. Plans with 4.5 or 5 stars often qualify for extended enrollment periods, giving you additional flexibility to join throughout the year.
You can compare plan ratings on Medicare.gov or by requesting comparison materials from insurance professionals. Remember that a highly-rated plan still must meet your specific needs regarding providers, medications, and coverage to be the right choice.
Understanding the differences in Medicare plans empowers you to choose coverage that protects your health and finances effectively. Whether you select Original Medicare with supplements or a Medicare Advantage plan depends on your individual healthcare needs, budget, and preferences. Moser Insurance Group Inc provides clear guidance and personalized support for Medicare beneficiaries throughout the Triad Area, helping you navigate these important decisions without pressure. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to discuss your Medicare options with experienced professionals who put your needs first.
Recent Comments