

Finding the best term life insurance means securing affordable protection for your family during the years they need it most. Whether you're raising young children, paying a mortgage, or supporting aging parents, term life insurance offers straightforward coverage without the complexity of permanent policies. Understanding how to evaluate providers, compare costs, and choose the right coverage amount can help you make a confident decision that protects your loved ones without straining your budget.
What Makes Term Life Insurance Different from Other Coverage Types
Term life insurance provides coverage for a specific period-typically 10, 20, or 30 years-at a fixed premium rate. Unlike permanent policies, it doesn't accumulate cash value or last your entire lifetime.
The simplicity of term life makes it appealing for families across the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem. You pay predictable premiums, and if you pass away during the term, your beneficiaries receive a tax-free death benefit.
Key Characteristics of Term Policies
Term life insurance stands out because of its affordability and straightforward structure. Understanding how term life works helps you appreciate why it's often the first choice for young families and budget-conscious individuals.
- Fixed premiums that don't increase during the term
- Guaranteed death benefit for your beneficiaries
- No cash value component keeping costs lower
- Convertibility options to change to permanent coverage later
- Customizable coverage amounts from $100,000 to several million
Most term policies expire at the end of the coverage period. You can often renew them, but premiums typically increase significantly based on your age at renewal.
Determining How Much Coverage You Actually Need
Calculating the right coverage amount involves analyzing your financial obligations and your family's future needs. The best term life insurance policy provides enough to replace your income, pay off debts, and fund long-term goals like college tuition.
Financial experts often recommend coverage equal to 10-15 times your annual income. However, this formula doesn't account for individual circumstances like existing savings, spouse income, or specific financial goals.
Comprehensive Coverage Calculation Method
| Financial Factor | Calculation Approach | Example Amount |
|---|---|---|
| Income replacement (10 years) | Annual salary × 10 | $600,000 |
| Mortgage balance | Current principal | $275,000 |
| College funding (2 kids) | $50,000 per child × 2 | $100,000 |
| Final expenses | Funeral + estate costs | $25,000 |
| Total Coverage Needed | Sum of all factors | $1,000,000 |
Consider your spouse's earning potential and existing life insurance through employment. If your partner could maintain the household on their income alone, you might need less coverage than someone whose income is the sole family support.
Families with young children in areas like Greensboro and Kernersville often need higher coverage amounts to ensure education funding and childcare costs are covered. Working with professionals who understand local cost-of-living factors helps you determine realistic coverage needs.
Comparing the Best Term Life Insurance Companies in 2026
The best term life insurance providers combine financial stability, competitive pricing, and excellent customer service. Reviews of top term life insurance companies highlight important differences in coverage options and premium costs across insurers.
Top-Rated Providers and Their Strengths
Financial strength ratings matter because your beneficiaries need the insurance company to be solvent when they file a claim. Look for insurers with A+ or higher ratings from agencies like AM Best or Standard & Poor's.
Leading term life insurance companies in 2026 include:
- State Farm – Known for local agent support and competitive rates
- Northwestern Mutual – High financial strength ratings and dividend payments
- Banner Life – Affordable premiums and simplified underwriting
- Protective Life – Flexible term lengths and conversion options
- Pacific Life – Strong customer satisfaction scores
Each provider offers different advantages. Some excel at fast approvals with minimal medical exams, while others provide more personalized service through local agents in the Triad Area, High Point, and Winston Salem.
Premium Comparison by Age and Coverage
| Age | $250,000 20-Year Term | $500,000 20-Year Term | $1,000,000 20-Year Term |
|---|---|---|---|
| 30 | $15-25/month | $25-40/month | $45-75/month |
| 40 | $25-40/month | $45-70/month | $85-130/month |
| 50 | $60-95/month | $115-180/month | $225-350/month |
These ranges reflect healthy non-smokers. Premiums vary based on health status, lifestyle factors, and the specific insurer's underwriting criteria.
Understanding Term Lengths and When to Choose Each Option
Selecting the right term length aligns your coverage with your financial timeline. The best term life insurance policy matches the duration of your most significant financial obligations.
10-year terms work well for short-term needs like covering a small business loan or bridging the gap until your mortgage is paid off. They offer the lowest premiums but provide protection for a limited period.
Strategic Term Selection Guidelines
Choose a 20-year term if you have young children and want coverage until they're financially independent. This is the most popular option because it balances affordability with meaningful protection during critical years.
30-year terms suit younger buyers who want to lock in low rates for decades. If you're in your 30s with a newborn and a new mortgage, 30-year coverage ensures protection through college graduation and mortgage payoff.
- Match term length to your mortgage duration
- Consider children's ages and years until college
- Account for planned retirement age
- Factor in spouse's ability to earn income
- Evaluate existing savings and assets
Some families in Greensboro and surrounding areas combine multiple term policies with different lengths. This "laddering" approach provides higher coverage during peak obligation years while reducing premiums as children become independent.
Medical Underwriting and How It Affects Your Premiums
The underwriting process evaluates your health risks to determine premium rates. Understanding what insurers examine helps you prepare for applications and potentially improve your rates.
According to insurance industry research, factors like age, health history, lifestyle habits, and family medical history all influence your premium classification.
Health Factors That Impact Your Rate Class
| Rating Class | Health Profile | Premium Impact |
|---|---|---|
| Preferred Plus | Excellent health, no tobacco, ideal weight | Lowest rates (-30% from standard) |
| Preferred | Good health, minor issues controlled | Low rates (-15% from standard) |
| Standard Plus | Average health, well-managed conditions | Baseline rates |
| Standard | Some health concerns or medications | +15-25% from baseline |
| Substandard | Significant health issues | +50-200% or more |
Most applicants qualify for standard or better rates. Even if you have controlled conditions like high blood pressure or diabetes, you can often secure coverage at reasonable premiums.
Simplified and Guaranteed Issue Alternatives
Traditional underwriting requires medical exams, blood tests, and detailed health questionnaires. However, simplified issue policies skip the medical exam, relying on health questions only.
Guaranteed issue policies accept applicants regardless of health status but typically offer lower coverage amounts ($25,000-$50,000) and higher premiums. These work better for final expense coverage than family income protection.
For clients in Kernersville and High Point dealing with health challenges, exploring different life insurance options including simplified underwriting can provide access to protection that might otherwise seem unavailable.
Key Policy Features and Riders Worth Considering
The best term life insurance policies offer valuable features beyond basic death benefit protection. Understanding available riders helps you customize coverage to your specific needs.
Conversion privileges allow you to change your term policy to permanent coverage without new medical underwriting. This proves valuable if you develop health issues during your term and want lifelong protection.
Essential Riders and Policy Features
Consider these common policy enhancements:
- Waiver of Premium Rider – Continues your coverage if you become disabled and can't work
- Accelerated Death Benefit – Provides early access to death benefit if diagnosed with terminal illness
- Children's Term Rider – Covers all children in your household under one rider
- Return of Premium – Refunds premiums if you outlive the term (significantly higher premiums)
- Accidental Death Benefit – Pays additional amount if death results from accident
Not every rider makes financial sense. Return of premium riders can double your premiums, and that money might generate better returns invested elsewhere.
Accelerated death benefit riders often come at no additional cost and provide crucial financial flexibility during difficult times. This feature allows terminally ill policyholders to access funds for medical care or final expenses.
While term life insurance focuses on straightforward protection, some individuals exploring comprehensive financial planning might eventually consider permanent options like universal life insurance, which offers both coverage and cash value accumulation with premium flexibility.
Application Process and Timeline for Getting Covered
Applying for the best term life insurance has become increasingly streamlined, with many insurers offering online applications and accelerated underwriting for healthy applicants.
The traditional application process takes 4-8 weeks from initial application to policy issuance. However, accelerated underwriting can reduce this to days or even hours for qualified applicants.
Step-by-Step Application Journey
The process typically follows these stages:
- Initial application – Provide personal, financial, and health information online or through an agent
- Medical exam scheduling – Insurer arranges paramedical visit at your home or office
- Underwriting review – Company evaluates medical records, exam results, and application
- Rate classification – You receive premium quote based on health assessment
- Policy delivery – Review and sign documents, make first premium payment
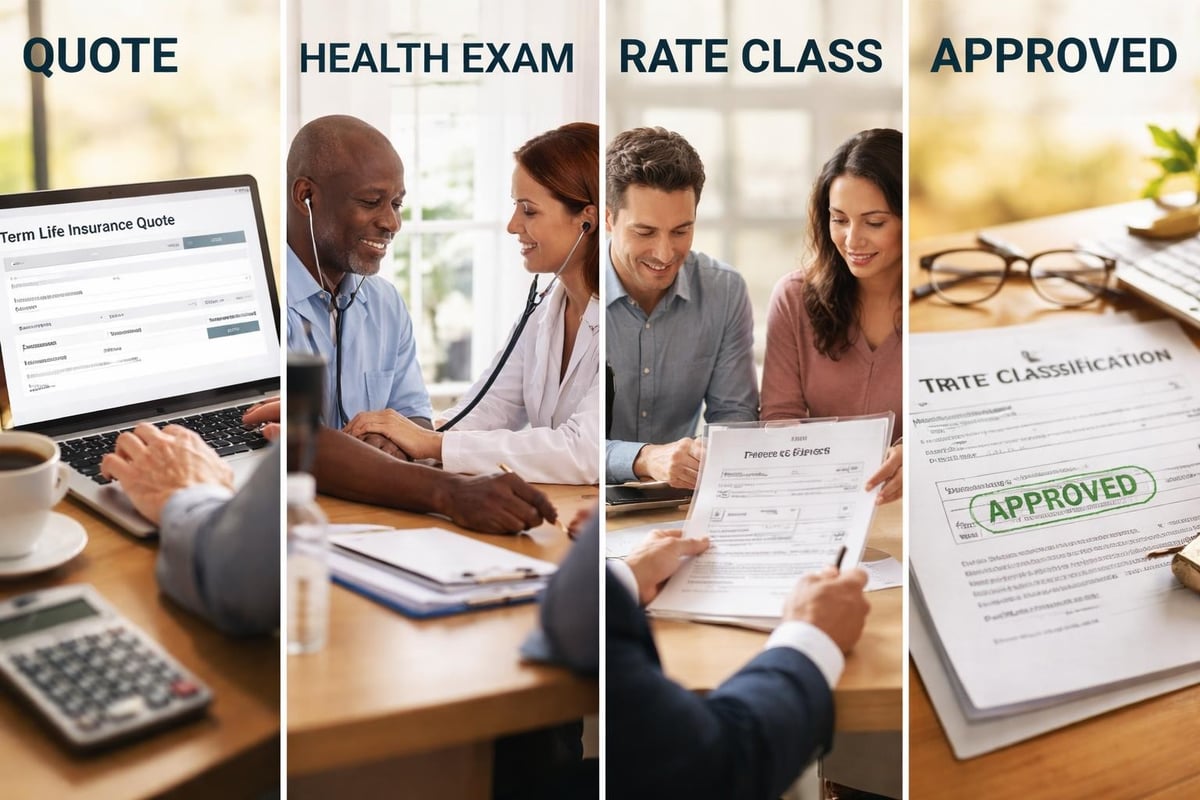
Accelerated underwriting programs use data analytics and electronic health records to skip medical exams for low-risk applicants. If you're under 50, healthy, and applying for moderate coverage amounts, you might qualify for instant approval.
Preparing for Your Medical Exam
Schedule your exam for morning hours when possible, as blood pressure and other metrics often read better earlier in the day. Avoid caffeine, alcohol, and fatty foods for 24 hours beforehand.
Bring a list of current medications, dosages, and your doctor's contact information. The examiner will collect blood and urine samples, measure height and weight, check blood pressure, and ask health questions.
For residents throughout the Triad Area seeking guidance on the application process, contacting experienced professionals at 336-862-1763 or moserinsurancegroup@gmail.com can help you understand what to expect and how to present your health information most effectively.
Cost-Saving Strategies for Term Life Insurance Premiums
Finding the best term life insurance means balancing adequate coverage with affordable premiums. Several strategies can significantly reduce your costs without sacrificing necessary protection.
Buying coverage while you're young and healthy locks in the lowest possible rates. A 30-year-old pays roughly half what a 40-year-old pays for identical coverage, and those fixed premiums continue for the entire term.
Proven Methods to Lower Your Premiums
Apply these approaches to reduce your life insurance costs:
- Compare multiple insurers – Rates vary by 30-50% between companies for identical coverage
- Choose the right term length – Don't overpay for coverage beyond your actual need period
- Improve your health – Losing weight, quitting smoking, or managing blood pressure before applying
- Pay annually – Annual payments avoid monthly billing fees (typically 5-8% savings)
- Bundle policies – Some insurers discount when you have multiple policies with them
Quitting tobacco use makes the most dramatic impact on premiums. After 12 months tobacco-free, you can typically reapply for non-smoker rates, potentially cutting your premium in half.
When to Consider Level vs. Decreasing Term
Standard level term insurance maintains the same death benefit throughout the policy period. Decreasing term insurance reduces the death benefit over time, typically aligned with a mortgage balance.
| Policy Type | Death Benefit | Premium | Best Used For |
|---|---|---|---|
| Level Term | Stays constant | Higher | Income replacement, general family protection |
| Decreasing Term | Reduces over time | Lower | Mortgage protection only |
Most families benefit more from level term's consistent protection. As children grow and living costs increase, that steady death benefit ensures comprehensive protection regardless of when death occurs.
Common Mistakes to Avoid When Buying Term Life Insurance
Understanding what not to do proves just as valuable as knowing best practices. Many buyers make preventable mistakes that leave their families underprotected or overpaying for coverage.
The most common error is buying too little coverage to save money on premiums. Research on term life insurance needs consistently shows families underestimate their actual protection requirements.
Critical Pitfalls and How to Avoid Them
- Waiting too long to buy – Every year you age increases premiums 8-12%
- Focusing only on price – The cheapest policy from a weak insurer puts beneficiaries at risk
- Ignoring conversion options – You might want permanent coverage later when term expires
- Overlooking employer coverage gaps – Job changes or termination eliminate workplace policies
- Not updating beneficiaries – Life changes require beneficiary designation updates
Many people assume their employer-provided life insurance suffices. However, workplace coverage typically equals only 1-2 times your salary and disappears when you leave the job.
Relying solely on employer coverage leaves most families significantly underinsured. Personal policies remain with you regardless of employment changes and generally provide 5-10 times more coverage.
For those in Winston Salem and surrounding communities navigating these decisions, visiting moserinsurancegroup.com or calling 336-862-1763 connects you with professionals who can help avoid these common pitfalls while finding the best term life insurance for your specific situation.
Policy Management and What Happens at Term End
Understanding your options as your term approaches expiration helps you make informed decisions about continued coverage. The best term life insurance companies provide clear communication and flexible choices when your policy term ends.
Your Options When the Term Expires
Most term policies offer three primary paths at expiration:
Renewal at attained age – Continue coverage at new premium rates based on your current age. Premiums typically increase 300-500% because you're older and potentially less healthy.
Conversion to permanent insurance – Exercise conversion privileges to change to whole or universal life without medical underwriting. This locks in coverage for life but at significantly higher premiums than term rates.
Allow policy to lapse – If your financial obligations have ended (mortgage paid, children independent, retirement savings sufficient), you may no longer need coverage.
Many families find their insurance needs decrease as they age. Children become financially independent, mortgages get paid off, and retirement savings accumulate. By your 60s, you might need minimal coverage or none at all.
Term life insurance deliberately provides temporary protection during your high-risk financial years. It's designed to expire when you've built sufficient assets to self-insure.
Monitoring Your Changing Insurance Needs
Review your coverage every 3-5 years or after major life events:
- Birth or adoption of children
- Marriage or divorce
- Home purchase or refinancing
- Significant income changes
- Starting a business
- Approaching retirement
Some families in Greensboro find that as one term policy approaches expiration, they need less total coverage but might still want protection for specific obligations. Purchasing a smaller new term policy while letting the old one lapse can maintain necessary protection at reasonable costs.
How Term Life Insurance Fits Into Comprehensive Financial Planning
The best term life insurance works as part of a broader financial strategy, not as an isolated product. Integrating life insurance with retirement planning, emergency savings, and debt management creates comprehensive family protection.
Term life insurance provides the foundation of protection while you build wealth through other vehicles. Similar to how homeowners in other countries might work with specialists like Roling Advies for mortgage planning guidance, coordinating your insurance with overall financial goals ensures all pieces work together effectively.
Coordinating Insurance with Other Financial Goals
Consider how term life insurance complements these financial priorities:
- Emergency fund building – Life insurance protects family if you die; emergency fund protects if you lose income
- Retirement savings – Low term premiums free up money for 401(k) or IRA contributions
- College funding – Death benefit can include education funding; 529 plans build savings while you're alive
- Debt elimination – Coverage should account for mortgage, student loans, and other obligations
The affordability of term life insurance makes it possible to maintain robust protection while pursuing other financial goals simultaneously. A $500,000 policy might cost $40 monthly-less than many cable bills-allowing continued retirement contributions and savings.
For families balancing multiple financial priorities, working with advisors who understand both insurance options and Medicare planning ensures comprehensive coverage across all life stages without redundant or conflicting policies.
Special Considerations for Different Life Stages and Situations
The best term life insurance strategy varies based on your current life stage and unique circumstances. What works for a 25-year-old single professional differs dramatically from what a 50-year-old parent of teenagers needs.
Young Professionals (20s-30s)
Lock in the lowest possible rates while you're young and healthy. Even if current obligations seem minimal, buying a 30-year term now guarantees affordable protection through your peak earning and family-building years.
Consider starting with moderate coverage ($250,000-$500,000) that you can supplement later. Evaluating current term life insurance options helps young buyers understand how affordable comprehensive protection can be.
Growing Families (30s-40s)
This stage demands the highest coverage amounts. Between mortgage obligations, multiple young children, and potentially decades until retirement, protection needs peak during these years.
Aim for 15-20 times your annual income if you're the primary earner with young children. The death benefit needs to replace your income for 10-15 years while children reach independence.
Pre-Retirees (50s-early 60s)
Coverage needs often decline as children launch and mortgages shrink. You might downsize from $1 million to $250,000-$500,000, focusing on final expense coverage and ensuring your spouse maintains their standard of living.
Evaluate whether you still need term coverage or if transitioning to permanent insurance makes sense. If health issues have emerged, converting existing term coverage before it expires might provide valuable permanent protection.
Special Situations Requiring Adjusted Strategies
| Situation | Coverage Consideration | Recommended Approach |
|---|---|---|
| Single parent | Higher coverage (20x income) | Maximum term length, disability riders |
| Self-employed | Business debt + family needs | Layered policies, key person insurance |
| Stay-at-home parent | Childcare replacement value | $300,000-$500,000 minimum |
| Blended family | Complex beneficiary needs | Multiple policies, clear beneficiary designations |
Business owners need coverage for both family protection and business continuity. Self-employed individuals in Kernersville and High Point should ensure their term life insurance accounts for business debts that might otherwise burden surviving family members.
Making Your Final Decision and Taking Action
After researching options, comparing providers, and calculating coverage needs, taking action protects your family immediately. The best term life insurance provides no benefit until you actually apply and get approved.
Don't let analysis paralysis delay your application. Comprehensive evaluations of term life insurers confirm that most top-rated companies offer similar core benefits at competitive prices-the key is choosing one and moving forward.
Your Action Plan for Securing Coverage
Follow these steps to complete your term life insurance purchase efficiently:
- Confirm your coverage amount using the calculation methods discussed earlier
- Select your term length based on your longest-running financial obligation
- Request quotes from 3-5 highly-rated insurers to compare premiums
- Review policy features and riders to customize coverage for your needs
- Complete the application with accurate, detailed health information
- Schedule and prepare for your medical exam following the preparation tips
- Review your policy documents carefully before signing
- Set up automatic premium payments to prevent accidental lapses
Contact information matters when you need guidance through this process. Reaching out to experienced professionals at moserinsurancegroup@gmail.com or 336-862-1763 provides personalized support tailored to your specific situation.
Start the process today rather than waiting for the "perfect" time. Every month you delay means you're one month older when you apply, and premiums increase with age. Your family deserves protection now, not after you've completed months of research.
Selecting the best term life insurance requires evaluating your family's financial needs, comparing reputable providers, and choosing coverage that balances comprehensive protection with affordable premiums. Whether you're just starting your career or approaching retirement in the Triad Area, term life insurance provides straightforward, cost-effective protection during the years your family depends on your income most. The team at Moser Insurance Group Inc helps individuals and families in Greensboro, Kernersville, High Point, and Winston Salem understand their life insurance options with clear guidance and personalized support, ensuring you can make confident decisions about protecting those you love without pressure or confusion.
Recent Comments