

Choosing the right prescription drug coverage can significantly impact your healthcare budget and access to necessary medications. Medicare Part D plans vary widely in premiums, formularies, pharmacy networks, and out-of-pocket costs, making it essential to understand your options before enrolling. Whether you're new to Medicare or reviewing your current coverage during the Annual Enrollment Period, finding the best Medicare Part D plans requires careful evaluation of your specific medication needs and financial situation.
Understanding Medicare Part D Coverage
Medicare Part D provides prescription drug coverage for Medicare beneficiaries through private insurance companies approved by Medicare. These standalone plans work alongside Original Medicare (Parts A and B) to help reduce medication costs. The official Medicare website provides comprehensive details about how Part D coverage works and what it includes.
Each Part D plan maintains a formulary, which is a list of covered medications organized into tiers. Understanding these tiers is crucial because your copayment or coinsurance amount depends on which tier contains your medication.
Coverage Phases Explained
Part D plans operate in distinct phases throughout the year:
- Deductible Phase: You pay full cost until meeting your deductible (if your plan has one)
- Initial Coverage Phase: You pay copays or coinsurance for covered drugs
- Coverage Gap: Previously known as the "donut hole," now significantly reduced
- Catastrophic Coverage: After reaching the out-of-pocket threshold, you pay minimal costs
In 2026, these phases have specific dollar thresholds that determine when you transition from one phase to another. The structure ensures that beneficiaries have protection against extremely high medication costs.
Comparing Plan Features and Costs
When evaluating the best Medicare Part D plans, several factors demand attention beyond the monthly premium. A low premium plan may actually cost more annually if your medications fall into higher tiers or aren't covered at all.
Premium costs for 2026 vary significantly based on the plan, your location, and your income level. Higher-income beneficiaries pay an Income-Related Monthly Adjustment Amount (IRMAA) in addition to the standard premium. For residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, available plans and pricing can differ from other North Carolina regions.
Key Comparison Factors
| Factor | Why It Matters | What to Check |
|---|---|---|
| Formulary Coverage | Ensures your medications are covered | Review the complete drug list for your specific prescriptions |
| Pharmacy Network | Affects convenience and costs | Verify your preferred pharmacy participates in the network |
| Prior Authorization | May delay medication access | Check if your drugs require approval before dispensing |
| Quantity Limits | Restricts how much you can get | Understand restrictions on prescription amounts |
| Step Therapy | Requires trying cheaper alternatives first | Know if your medications have step therapy requirements |
The analysis from NerdWallet highlights top providers for 2026 based on affordability and quality metrics that beneficiaries should consider when selecting coverage.
Top-Rated Plans for 2026
Several insurance carriers consistently receive high ratings for their Medicare Part D offerings. These plans excel in customer service, formulary comprehensiveness, and cost-effectiveness.
National carriers like Humana, UnitedHealthcare, Aetna (CVS Health), Cigna, and WellCare maintain strong presences across most states, including North Carolina. Regional plans may also offer competitive options specifically tailored to local pharmacy networks in the Triad Area.
Evaluating Plan Star Ratings
Medicare assigns star ratings from 1 to 5 based on:
- Customer service quality
- Member complaints
- Drug pricing transparency
- Member experience surveys
- Health outcomes
Plans with 4 or higher stars generally demonstrate superior performance across these categories. However, the highest-rated plan isn't necessarily the best choice for your individual situation.
Matching Plans to Your Medication Needs
The best Medicare Part D plans for you depend entirely on your current prescriptions and anticipated medication needs. A plan that's perfect for someone taking only generic medications may be inadequate for someone requiring multiple brand-name drugs.
Start by creating a comprehensive list of all your medications, including dosages and frequencies. This information allows you to check each plan's formulary and calculate your estimated annual costs accurately.
Drug Tier Structures
Most Part D plans organize medications into five or six tiers:
- Tier 1: Preferred generic drugs (lowest copay)
- Tier 2: Generic drugs
- Tier 3: Preferred brand-name drugs
- Tier 4: Non-preferred brand-name drugs
- Tier 5: Specialty drugs (highest copay)
- Tier 6: Select care drugs (some plans only)
Generic medications almost always cost less than brand-name alternatives. If your doctor prescribes brand-name drugs, ask whether generic equivalents are available and clinically appropriate.
For those considering supplemental coverage options, medical supplement plans work differently than Part D and address Original Medicare's gaps rather than prescription costs.
Enrollment Periods and Deadlines
Understanding when you can enroll in or change Part D plans prevents coverage gaps and potential penalties. Missing enrollment windows can result in late enrollment penalties that persist for as long as you maintain Part D coverage.
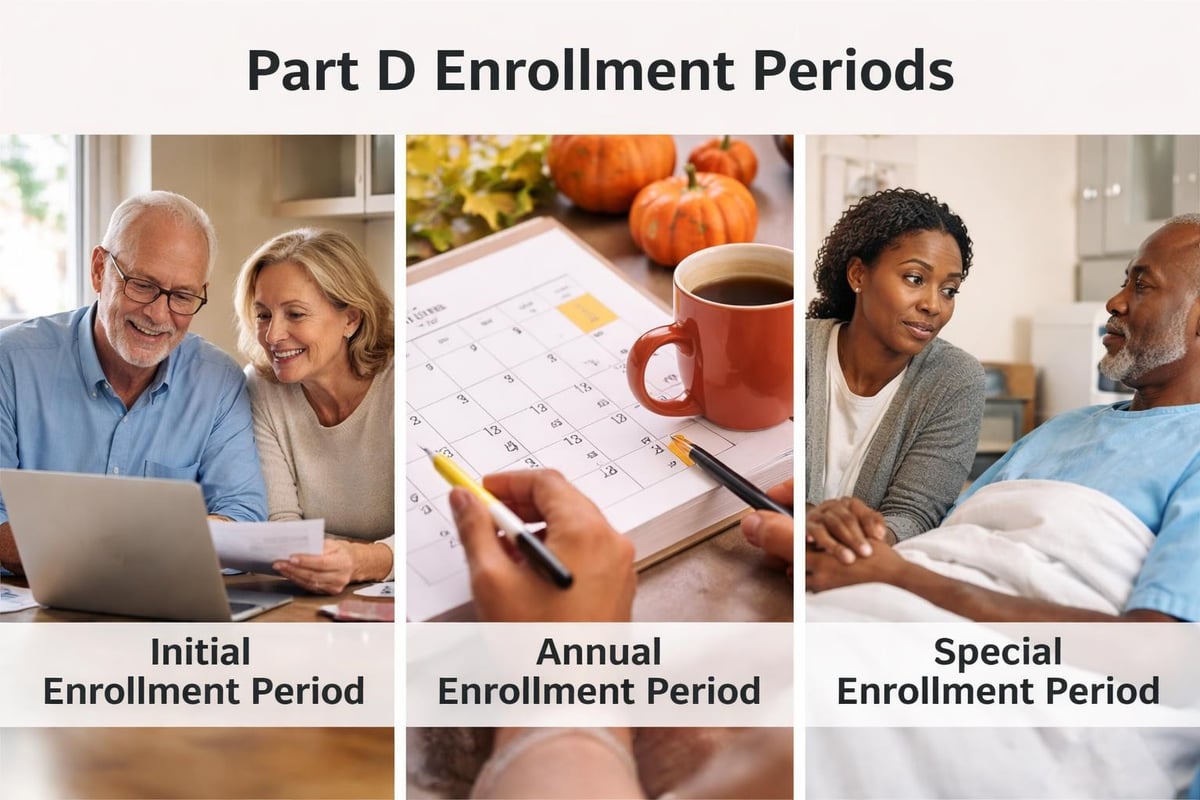
Initial Enrollment Period: This seven-month window begins three months before your 65th birthday month, includes your birthday month, and extends three months after. If you're already receiving Social Security benefits, you'll be automatically enrolled in Medicare Parts A and B.
Annual Enrollment Period: Running from October 15 through December 7 each year, this period allows all Medicare beneficiaries to switch Part D plans, join a new plan, or drop coverage. Changes become effective January 1 of the following year.
Special Enrollment Periods: Certain qualifying events trigger special enrollment opportunities outside the standard periods, including moving to a new service area, losing other creditable coverage, or qualifying for Extra Help.
The Late Enrollment Penalty equals 1% of the national base beneficiary premium multiplied by the number of months you went without creditable coverage. This penalty recalculates annually and can become substantial over time.
Pharmacy Networks and Access
Your choice of pharmacy significantly impacts out-of-pocket costs under Part D plans. Plans contract with specific pharmacies to create preferred and standard network tiers, with preferred pharmacies offering lower copayments.
Pharmacy Network Types
Retail Pharmacies: Traditional brick-and-mortar locations where you pick up prescriptions in person. Chain pharmacies like CVS, Walgreens, and Walmart participate in most Part D networks throughout Greensboro, Winston Salem, High Point, and Kernersville.
Mail-Order Pharmacies: Typically provide 90-day supplies at reduced costs compared to 30-day retail fills. Particularly beneficial for maintenance medications you take regularly.
Specialty Pharmacies: Required for certain high-cost or complex medications that need special handling, monitoring, or administration support.
Before selecting a plan, verify that your preferred pharmacy participates as a preferred network provider. Using out-of-network pharmacies results in higher costs or complete non-coverage except in emergency situations.
Extra Help and Low-Income Subsidies
The Extra Help program, also called the Low-Income Subsidy (LIS), assists Medicare beneficiaries with limited income and resources in paying Part D costs. This valuable program can reduce or eliminate premiums, deductibles, and copayments.
Qualification thresholds for 2026 consider both income and asset limits. If you qualify for full Extra Help, you'll pay no premium for basic plans, no deductible, and minimal copayments ranging from $0 to approximately $4 for generics and $10 for brand-name drugs.
| Income Level | Resource Limit (Individual) | Resource Limit (Couple) | Subsidy Level |
|---|---|---|---|
| Up to 135% FPL | $10,930 | $17,130 | Full Extra Help |
| 135-150% FPL | $16,660 | $33,240 | Partial Extra Help |
Applications are available through Social Security offices, online at ssa.gov, or by calling 1-800-772-1213. Some individuals automatically qualify if they receive Medicaid or Supplemental Security Income.
Plan Changes and Industry Trends for 2026
The Medicare landscape continues evolving, with insurers scaling back some offerings for 2026 in response to regulatory changes and financial pressures. These adjustments affect plan availability and benefits in certain markets.
Major carriers have reduced their plan offerings in some counties, potentially requiring beneficiaries to select new coverage during the Annual Enrollment Period. This consolidation emphasizes the importance of reviewing your options annually rather than automatically renewing existing coverage.
Formulary changes occur frequently as insurers negotiate drug prices with manufacturers and adjust coverage based on new medications entering the market. A drug covered this year might move to a different tier or require prior authorization next year.
Staying Informed About Changes
Plans must notify members about significant changes affecting their coverage, including:
- Formulary modifications
- Premium adjustments
- Pharmacy network changes
- Cost-sharing updates
Review your Annual Notice of Change (ANOC), which arrives in September, to understand how your current plan will differ in the upcoming year.
For comprehensive guidance on what Medicare covers and costs in 2026, including Part D specifics, staying current with annual updates ensures you're prepared for any changes affecting your coverage.
Coordinating Part D with Other Coverage
Many Medicare beneficiaries juggle multiple coverage sources, and understanding how Part D coordinates with other insurance prevents confusion and maximizes benefits.
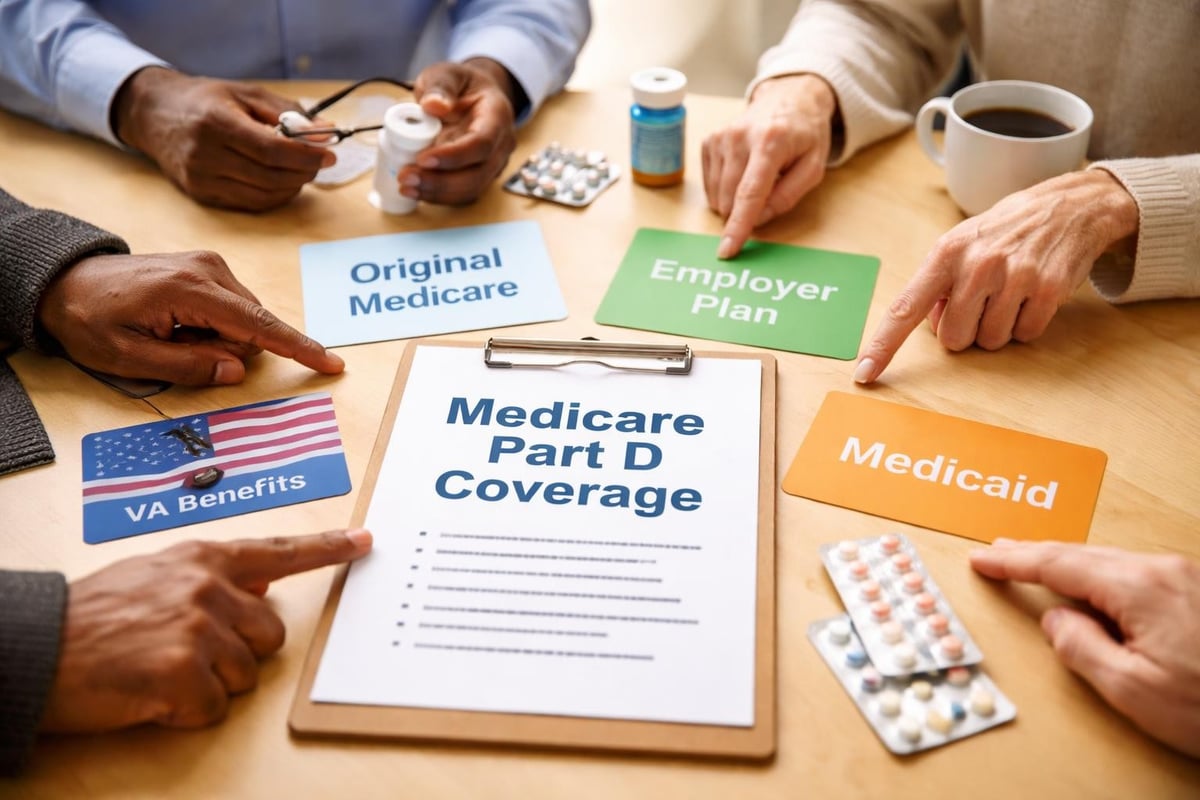
Employer or Union Coverage: If you maintain creditable prescription coverage through a current or former employer, you may delay Part D enrollment without penalty. However, verify that your coverage meets Medicare's credentialing standards.
Veterans Benefits: VA prescription coverage is creditable, allowing veterans to postpone Part D enrollment. However, some veterans choose Part D for medications not covered by VA or for convenience reasons.
Medicaid: Dual-eligible beneficiaries who qualify for both Medicare and Medicaid receive prescription coverage through Medicare Part D plans with Extra Help assistance rather than through Medicaid directly.
For those exploring turning 65 and Medicare decisions, understanding how Part D fits into your overall coverage strategy is essential for comprehensive protection.
Using Medicare's Plan Finder Tool
Medicare provides a free online Plan Finder tool that allows you to compare all available Part D plans in your area based on your specific medications. This resource calculates estimated annual costs including premiums, deductibles, and copayments.
Steps to Compare Plans Effectively
- Gather Your Information: Compile your current medications, dosages, and preferred pharmacies
- Enter Your Medications: Input each prescription into the Plan Finder tool
- Review Cost Estimates: Examine total estimated annual costs, not just monthly premiums
- Check Formularies: Verify all your medications are covered and review any restrictions
- Evaluate Star Ratings: Consider customer satisfaction and quality metrics
- Compare Top Options: Narrow down to three to five plans for detailed comparison
The guidance from Medical News Today offers additional strategies for comparing plans based on formularies, benefits, and total costs rather than focusing solely on premiums.
When comparing the best Medicare Part D plans, remember that the lowest premium rarely equals the lowest total annual cost. A comprehensive evaluation considering all out-of-pocket expenses provides the most accurate picture.
Regional Considerations for North Carolina Residents
Medicare Part D plan availability and pricing vary by county and ZIP code. Residents throughout the Triad Area benefit from robust competition among carriers, typically offering 20 to 30 different plan options.
Local pharmacy networks in Greensboro, Winston Salem, High Point, and Kernersville include both national chains and independent pharmacies. Some plans designate certain pharmacies as preferred providers, offering lower copayments when you fill prescriptions at these locations.
North Carolina residents should verify that plans they're considering include adequate pharmacy access in their specific community. Rural beneficiaries may have fewer in-network options than those in urban centers.
For personalized assistance navigating Part D options in the Triad Area, contacting local Medicare specialists ensures you understand how plans perform in your specific location. You can reach Moser Insurance Group Inc at 336-862-1763 or via email at moserinsurancegroup@gmail.com for guidance tailored to your situation.
Avoiding Common Enrollment Mistakes
Several frequent errors can result in higher costs or coverage gaps when selecting Part D plans. Awareness of these pitfalls helps you make more informed decisions.
Focusing Only on Premium Costs: The monthly premium represents just one component of your total expenses. Plans with higher premiums may offer better formulary coverage or lower copayments that reduce your annual spending.
Ignoring Formulary Details: Assuming your medications are covered without verification can lead to unexpected costs. Always check the current formulary before enrolling.
Overlooking Generic Alternatives: Many beneficiaries pay more than necessary by not exploring generic options when appropriate alternatives exist.
Missing Enrollment Deadlines: Late enrollment penalties accumulate monthly and continue for as long as you maintain Part D coverage, potentially adding hundreds of dollars annually.
Not Reviewing Annually: Plan benefits, formularies, and costs change yearly. What was the best Medicare Part D plan last year may not remain optimal for 2026.
Medication Management Strategies
Beyond selecting the right plan, several strategies help minimize prescription costs regardless of which Part D coverage you choose.
Cost-Reduction Techniques
- Request 90-Day Supplies: Mail-order or retail 90-day fills typically cost less than three separate 30-day fills
- Ask About Generic Options: Generic medications cost significantly less than brand-name equivalents
- Compare Pharmacy Prices: Costs vary between pharmacies even within the same network
- Use Preferred Pharmacies: Plans offer lower copays at preferred network locations
- Check Manufacturer Coupons: Some drug makers offer patient assistance programs
Discuss medication costs openly with your healthcare providers. Doctors can often prescribe equally effective alternatives that fall into lower formulary tiers or have better coverage under your plan.
Getting Professional Assistance
Navigating Medicare's complexities, including Part D selection, often benefits from professional guidance. Licensed insurance agents specializing in Medicare understand plan nuances and can provide personalized recommendations based on your specific medications and budget.
Independent agents work with multiple carriers, allowing them to present options from various companies rather than promoting a single insurer's products. This unbiased approach ensures you see the full range of available plans.
For residents throughout Greensboro, Winston Salem, High Point, and Kernersville, local expertise matters. Agents familiar with regional pharmacy networks, plan performance in North Carolina, and area-specific considerations provide valuable insights.
When seeking assistance, prepare questions about:
- How your current medications affect plan costs
- Whether your preferred pharmacies participate in preferred networks
- Potential coverage gaps or restrictions
- Alternative plans if your current coverage changes
- Coordination with Medicare supplement options
Quality agents invest time understanding your situation before making recommendations, focusing on education rather than sales pressure. They should explain plan differences clearly and help you make confident decisions.
Special Considerations for Specific Medications
Certain medication categories require additional attention when selecting Part D coverage due to cost or access considerations.
Insulin: Recent changes have capped insulin costs at $35 per month for Medicare Part D enrollees, regardless of plan or insulin type. This protection applies throughout all coverage phases.
Specialty Medications: High-cost drugs for conditions like cancer, multiple sclerosis, or rheumatoid arthritis typically fall into Tier 5, requiring coinsurance of 25-33% during the initial coverage phase. These costs can reach thousands of dollars monthly.
Brand-Name Drugs Without Generics: When no generic alternative exists, you'll pay higher copayments or coinsurance. Manufacturer assistance programs may help offset costs.
Medications Requiring Prior Authorization: Some plans require your doctor to justify medical necessity before covering certain drugs. This process can delay access to needed medications.
Understanding how your specific medications are treated under different plans helps identify which coverage provides optimal access and affordability for your health needs.
Selecting from the best Medicare Part D plans requires evaluating your medications, comparing costs comprehensively, and understanding how plan features align with your needs. The Annual Enrollment Period provides your yearly opportunity to adjust coverage as your medications or health status changes. At Moser Insurance Group Inc, we help individuals throughout the Triad Area understand their Medicare options with clear, personalized guidance. Call us at 336-862-1763 or email moserinsurancegroup@gmail.com to discuss which Part D plan best serves your prescription coverage needs. Visit moserinsurancegroup.com to learn more about how we can help you make confident Medicare decisions without pressure.
Recent Comments