
Choosing the right annuity can transform your retirement planning from uncertain to secure. With so many options available in 2026, understanding which products offer the strongest guarantees, most competitive rates, and best features for your specific situation makes all the difference. For individuals and families in the Triad Area, Greensboro, Kernersville, High Point, and Winston Salem, selecting from the best annuities requires balancing income needs, risk tolerance, and long-term financial goals. This comprehensive guide explores the top annuity types, leading providers, and essential factors to consider when securing your retirement income.
Understanding Annuity Types and Their Benefits
Annuities come in several distinct forms, each designed to meet different retirement objectives. Fixed annuities offer guaranteed interest rates and principal protection, making them attractive for conservative investors seeking predictable growth. Variable annuities allow investment in sub-accounts similar to mutual funds, offering growth potential but with market risk. Indexed annuities tie returns to market indices like the S&P 500 while providing downside protection through guaranteed minimum returns.
The primary appeal of the best annuities lies in their ability to convert retirement savings into guaranteed lifetime income. Unlike traditional investment accounts where you might outlive your money, annuities with lifetime income riders ensure you receive regular payments for as long as you live. This addresses one of retirement's biggest concerns: longevity risk.
Fixed Annuities for Stability
Fixed annuities represent the most straightforward annuity structure. You deposit a lump sum or make regular payments, and the insurance company guarantees a specific interest rate for a set period. These products function similarly to certificates of deposit but often offer higher rates and tax-deferred growth.
Key advantages include:
- Guaranteed principal protection regardless of market conditions
- Predictable interest crediting for planning purposes
- Tax-deferred accumulation until withdrawal
- No annual contribution limits like IRAs or 401(k) plans
Current fixed annuity rates in 2026 range from 4.5% to 6.2% depending on the term length and insurance company. Top fixed annuity companies have consistently demonstrated financial strength ratings of A+ or higher from major rating agencies.
Variable Annuities for Growth Potential
Variable annuities appeal to investors comfortable with market exposure in exchange for higher return potential. Your contributions are allocated among various sub-accounts invested in stocks, bonds, or balanced portfolios. Account values fluctuate based on investment performance, creating opportunities for substantial growth during bull markets.
Many variable annuities include optional riders that guarantee minimum income levels or death benefits, even if your account value declines. These living benefit riders have become increasingly sophisticated, offering guaranteed lifetime withdrawal benefits (GLWBs) that protect against sequence-of-returns risk during early retirement years.
| Feature | With GLWB Rider | Without Rider |
|---|---|---|
| Income Guarantee | Yes, regardless of market | Based on account value |
| Annual Fees | 1.0% – 1.5% higher | 0.5% – 1.0% typical |
| Upside Potential | Limited by rider terms | Unlimited |
| Downside Protection | Guaranteed minimum | Full market exposure |
The additional cost of these riders typically ranges from 0.75% to 1.25% annually, but many retirees find the guaranteed income floor worth the expense.
Indexed Annuities Combining Safety and Growth
Fixed indexed annuities have surged in popularity as they bridge the gap between conservative fixed annuities and aggressive variable products. Your returns are linked to the performance of market indices, but your principal remains protected even when markets decline. This asymmetric return profile appeals to moderate-risk investors who want market participation without downside exposure.
Indexed annuities use participation rates, caps, and spreads to determine how much index gain credits to your account. A typical product might offer 100% participation up to a 6% annual cap, meaning you'd receive the full index return up to 6% in positive years and 0% in negative years. Understanding these crediting methods is essential when comparing the best annuities in this category.
How much income indexed annuities generate depends heavily on when you activate the income rider and current crediting rates. A 65-year-old with $200,000 might receive $10,000 to $12,000 annually in guaranteed lifetime income, with potential increases if the index performs well.
Income Annuities for Immediate Payments
Immediate annuities, also called single premium immediate annuities (SPIAs), convert a lump sum into guaranteed monthly income starting within one year. You surrender control of the principal in exchange for contractual payment guarantees lasting for life or a specified period.
These products excel at maximizing immediate cash flow. Best income annuities in 2026 offer payout rates of approximately 5.5% to 7.2% for a 65-year-old, depending on gender, state, and whether you select a single or joint-life option.
Common payout options include:
- Life only: Highest payments but no survivor benefits
- Life with period certain: Guaranteed payments for minimum period (10, 15, or 20 years)
- Joint and survivor: Continues payments to spouse at full or reduced amount
- Cash refund: Beneficiaries receive remaining principal if you die early
The irreversible nature of immediate annuities requires careful consideration. Once established, you cannot access the principal for emergencies or change your mind about the income structure.
Evaluating Financial Strength and Company Reputation
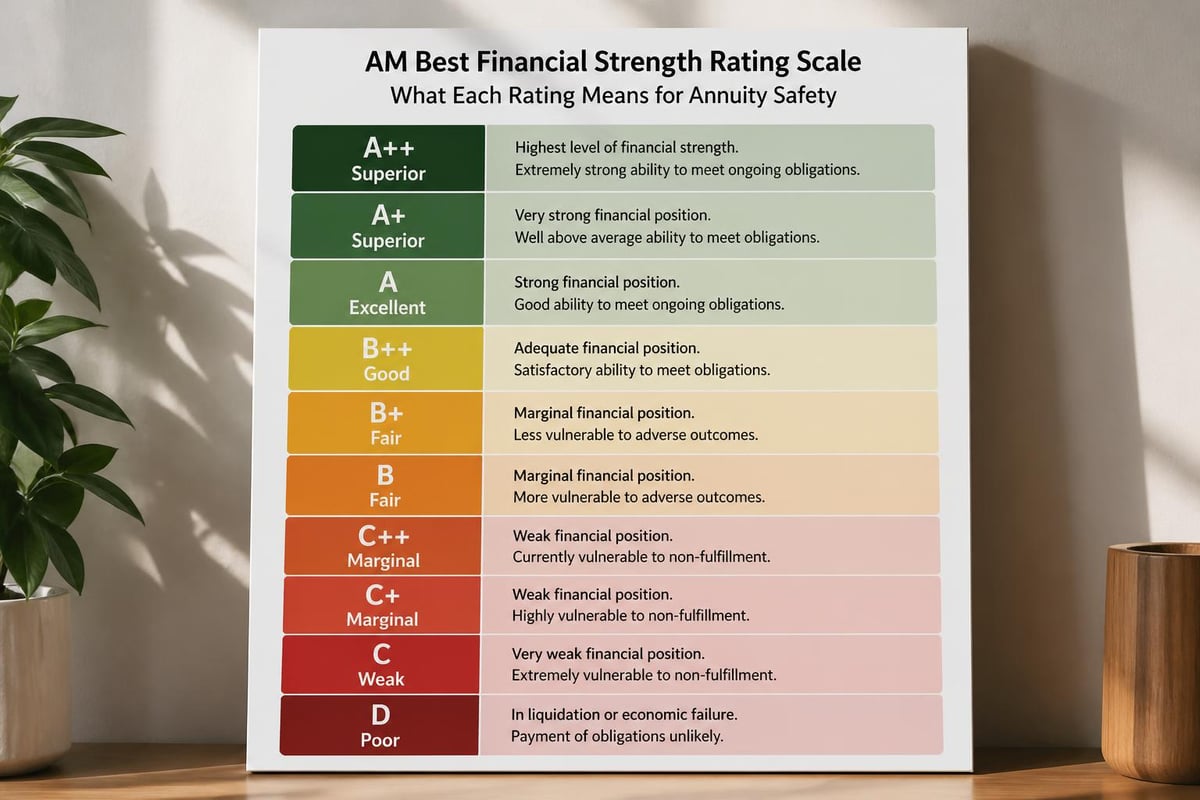
Selecting among the best annuities requires examining not just product features but also the issuing insurance company's financial stability. Annuities are only as secure as the companies backing them. Are annuities safe depends largely on the insurer's claims-paying ability and state guarantee fund protections.
Major rating agencies (AM Best, Moody's, Standard & Poor's, and Fitch) evaluate insurance companies' financial strength. Look for carriers with ratings of A or higher from multiple agencies. This indicates strong capitalization, prudent investment management, and reliable claim payment history.
State guarantee associations provide a safety net if an insurance company becomes insolvent, typically covering $250,000 per contract owner per company in most states. However, relying on this protection should be a last resort rather than a primary consideration when choosing annuity providers.
Leading Annuity Providers in 2026
Several insurance companies consistently rank among top annuity providers based on financial strength, product innovation, and customer service. New York Life, Mass Mutual, and Northwestern Mutual lead in fixed annuities with their mutual company structure providing policyowner dividends. For indexed annuities, companies like Athene, Allianz, and American Equity offer competitive caps and participation rates.
Variable annuity leaders include TIAA, Fidelity, and Jackson National, each offering diverse sub-account options and comprehensive rider selections. These companies provide robust online platforms, transparent fee structures, and responsive customer support essential for long-term annuity management.
When evaluating providers, consider factors beyond just credited rates:
- Surrender period length (typically 5-10 years)
- Annual penalty-free withdrawal amounts
- Rider availability and costs
- Customer service accessibility
- Online account management features
Fees, Charges, and Cost Structures
Understanding annuity fees is critical when identifying the best annuities for your situation. Unlike mutual funds with standardized expense ratios, annuity costs vary significantly by type and include multiple fee layers that impact net returns.
Fixed annuities typically have no explicit annual fees, with the insurance company profiting from the spread between what they credit to your account and what they earn on their investment portfolio. Surrender charges apply if you withdraw funds during the surrender period, usually starting at 7-10% in year one and declining annually.
| Annuity Type | Typical Annual Fees | Additional Charges |
|---|---|---|
| Fixed | 0% (spread-based) | Surrender charges only |
| Indexed | 0% – 0.5% | Rider fees, surrender charges |
| Variable | 0.5% – 1.5% | Sub-account fees, rider fees, surrender charges |
| Immediate | 0% | Built into payout rate |
Variable annuities carry the highest fee structures, often totaling 2-3% annually when combining mortality and expense charges, administrative fees, sub-account expenses, and optional rider costs. While these fees reduce returns, the guarantees and death benefits may justify the expense for risk-averse investors.
Working with a fiduciary advisor, such as Brookwood Investment Group LLC, can help you analyze total cost structures and determine whether annuity fees align with the value provided for your specific retirement goals.
Matching Annuities to Retirement Goals
The best annuities for you depend entirely on your unique financial situation, timeline, and objectives. A 50-year-old accumulating retirement assets has different needs than a 70-year-old seeking maximum current income. Could an annuity be your retirement safety net explores age, savings level, asset allocation, and income requirements as key decision factors.
For pre-retirees in their 50s and early 60s, deferred annuities (fixed, indexed, or variable) allow continued tax-deferred accumulation while preserving principal. These products work well for conservative portfolio portions, complementing equity holdings and providing stability during market volatility.
Retirees Seeking Guaranteed Income
Recent retirees prioritize income generation over long-term growth. Immediate annuities or deferred income annuities with short waiting periods maximize lifetime income guarantees. Combining annuities with other retirement income sources like Social Security, pensions, and Medicare benefits creates a comprehensive retirement income plan.
A common strategy involves "annuitizing" enough assets to cover essential expenses (housing, food, healthcare, insurance premiums) while maintaining liquid investments for discretionary spending and emergencies. This "floor and upside" approach provides both security and flexibility.
Consider these allocation approaches:
- Conservative: 40-50% of retirement assets in annuities
- Moderate: 25-35% annuitized for essential income
- Aggressive: 10-20% for guaranteed income floor only
Your ideal allocation depends on other guaranteed income sources, total asset level, health status, and legacy objectives. Those with substantial pensions or Social Security benefits may need less annuity income, while self-employed individuals without traditional pensions might allocate more heavily.
Common Annuity Myths and Misconceptions
Despite their benefits, annuities face significant criticism, much of it based on outdated information or misunderstandings. Don’t believe these myths about annuities addresses common misconceptions that prevent people from considering these products objectively.
Myth 1: Annuities are too expensive. While variable annuities can carry high fees, fixed and indexed annuities often have minimal costs. Comparing total expenses against the value of guarantees provides a more accurate assessment than rejecting all annuities based on fee concerns.
Myth 2: You lose all your money when you die. Many annuities include death benefits ensuring beneficiaries receive at least the premium paid, even if account values have declined. Period-certain options guarantee payments continue to heirs for specified timeframes.
Myth 3: Annuity returns are too low. In low-interest environments, annuity rates may seem modest, but they provide guarantees that market investments cannot match. The appropriate comparison is against bond portfolios or CDs, not stocks.
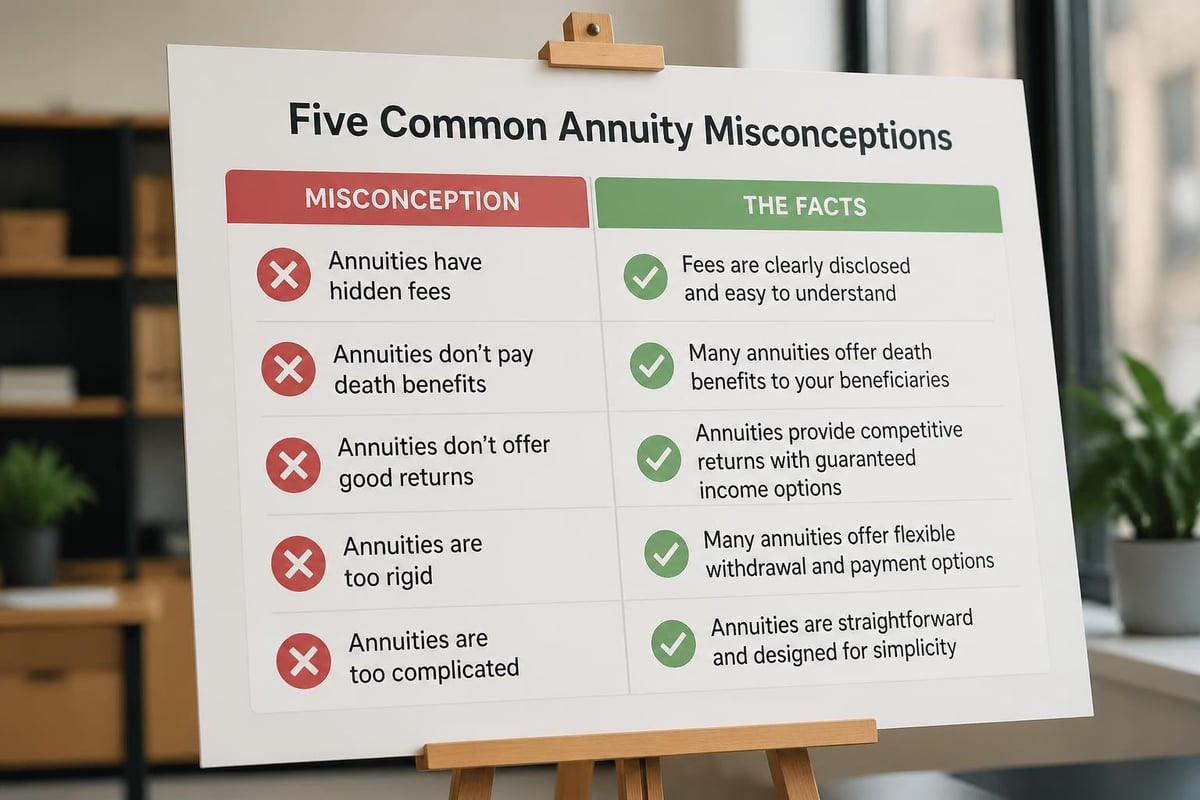
Myth 4: Annuities are too complex. While some variable annuities have intricate features, basic fixed annuities operate simply. Working with experienced advisors in the Triad Area can clarify product mechanics and ensure you understand exactly what you're purchasing.
Myth 5: Annuities provide no liquidity. Most annuities allow 10% penalty-free withdrawals annually after the first year. While they shouldn't serve as emergency funds, they're not completely inaccessible. Some products offer enhanced liquidity for nursing home confinement or terminal illness.
Tax Considerations and Qualified vs. Non-Qualified
Annuity taxation differs significantly depending on whether the contract is "qualified" (funded with pre-tax retirement dollars) or "non-qualified" (purchased with after-tax money). Understanding these distinctions helps optimize tax efficiency when integrating annuities into broader retirement planning.
Qualified annuities held within IRAs or 401(k) plans defer all growth from taxation until withdrawal, at which point ordinary income tax applies to the full distribution amount. These function similarly to other qualified retirement accounts, subject to required minimum distributions (RMDs) beginning at age 73 in 2026.
Non-qualified annuities offer partial tax advantages. The principal you contributed (basis) returns tax-free, while earnings are taxed as ordinary income. Withdrawals use "last in, first out" (LIFO) accounting, meaning gains are taxed first before basis returns. This differs from traditional investments where you can strategically harvest gains and losses.
Key tax planning considerations:
- Non-qualified annuities have no contribution limits, useful for high earners maxing out other retirement accounts
- Tax-deferred growth can accumulate for decades without annual tax drag
- Annuity income doesn't qualify for preferential capital gains rates
- Withdrawals before age 59½ may incur 10% early withdrawal penalties plus ordinary income tax
Coordinating annuity withdrawals with Social Security benefits, RMDs, and other income sources minimizes lifetime tax liability. Much like choosing between different health insurance options or evaluating Medicare supplement plans, personalized guidance ensures you select the most tax-efficient structure for your circumstances.
Integration with Comprehensive Retirement Planning
The best annuities serve as one component within a diversified retirement strategy rather than standalone solutions. Effective retirement planning addresses income generation, healthcare costs, legacy objectives, and risk management through coordinated insurance and investment products.
For instance, combining term or whole life insurance with annuities creates both income protection and legacy benefits. Life insurance ensures financial support for surviving spouses while annuities maximize lifetime income. This pairing addresses both longevity risk and premature death risk simultaneously.
Healthcare planning represents another critical integration point. Medicare enrollment decisions, supplemental coverage choices, and out-of-pocket expense projections all influence how much guaranteed annuity income you need. Working with specialists in Medicare, life insurance, and health insurance options provides the comprehensive education necessary for confident decisions.
Getting Professional Guidance
Annuity selection involves complex tradeoffs between income guarantees, liquidity, fees, and growth potential. While general research provides valuable context, personalized analysis accounting for your specific situation yields optimal results. Independent advisors who represent multiple insurance carriers can compare products objectively without pushing proprietary solutions.
For those in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, local expertise combined with broader market access ensures you find the best annuities available nationally while receiving face-to-face service and ongoing support.
Whether you're approaching retirement and evaluating income options or already retired and seeking to optimize your existing portfolio, professional guidance helps navigate the hundreds of annuity products available in 2026. Contact Moser Insurance Group Inc at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your specific retirement income needs.
Comparing Specific Annuity Products
Beyond general annuity categories, specific products within each type vary considerably in features, costs, and suitability. When evaluating fixed annuities, compare guaranteed rates, surrender schedules, and financial strength ratings across multiple carriers. Rate differences of even 0.25% compound significantly over ten years.
For indexed annuities, examine participation rates, caps, and crediting methods carefully. Some products offer uncapped participation but only 50% of index gains, while others provide 100% participation up to a cap. Neither approach is inherently superior, the better choice depends on your market outlook and risk tolerance.
Critical comparison factors include:
- Interest crediting frequency: Annual, monthly, or daily
- Index options: Single-index or multiple-index allocations
- Floor guarantees: Minimum returns during negative market years
- Bonus features: Upfront premium bonuses and their conditions
- Income rider strength: Payout percentages and roll-up rates
Variable annuity comparisons should focus on sub-account selection, expense ratios, rider costs, and guarantee quality. A product with lower base fees but expensive riders may cost more than a higher-fee annuity with built-in benefits.
Request detailed illustrations from multiple carriers showing projected values under various scenarios. While these illustrations aren't guarantees, they reveal how different products perform under identical assumptions, facilitating apples-to-apples comparisons.
Addressing Inflation and Purchasing Power
One frequent criticism of fixed annuity income involves inflation risk. A payment of $1,000 monthly today will purchase significantly less in twenty years if inflation averages 3% annually. The best annuities address this concern through inflation-adjusted payout options or growth potential exceeding inflation.
Some immediate annuities offer cost-of-living adjustments (COLAs) that increase payments annually by a fixed percentage or inflation index. Initial payments are lower than level-payment annuities, but over time, purchasing power preservation may justify the reduced starting income.
Indexed annuities with income riders often include "step-up" features that increase your income base when account values reach new highs. If markets perform well, your guaranteed income can increase, partially offsetting inflation. These features don't guarantee inflation protection but provide potential upside that fixed payments lack.
Variable annuities with aggressive sub-account allocations may generate returns exceeding inflation long-term, though with corresponding volatility. Balancing these growth-oriented annuities with conservative fixed products creates a middle-ground approach addressing both stability and inflation concerns.
Securing reliable retirement income requires careful evaluation of the best annuities available in 2026, balancing guaranteed payments, growth potential, fees, and flexibility. Whether you prefer the simplicity of fixed annuities, the upside participation of indexed products, or the growth potential of variable contracts, understanding how each type fits your broader financial picture ensures confident decisions. At Moser Insurance Group Inc, we help individuals and families in the Triad Area understand their retirement income options with clear guidance and personalized support. Contact us at 336-862-1763, email moserinsurancegroup@gmail.com, or visit Moser Insurance Group Inc to explore how annuities can strengthen your retirement plan.
Recent Comments