
Understanding how to apply for Medicare can feel overwhelming when you first approach age 65 or become eligible through disability. Medicare provides critical health coverage for millions of Americans, but the enrollment process involves specific timelines, eligibility requirements, and decisions that affect your coverage for years to come. Whether you're transitioning from employer coverage or enrolling for the first time, knowing the right steps ensures you avoid penalties and secure the protection you need.
Understanding Medicare Eligibility Requirements
Before you apply for Medicare, you need to confirm your eligibility status. Most people qualify at age 65, but certain circumstances allow earlier enrollment.
Age-Based Eligibility
The standard Medicare enrollment age is 65 years old. If you're receiving Social Security benefits before turning 65, you'll be automatically enrolled in Medicare Part A and Part B when you reach that milestone. Your Medicare card arrives in the mail approximately three months before your 65th birthday.
Automatic enrollment occurs when:
- You receive Social Security retirement benefits
- You receive Railroad Retirement Board benefits
- You have been getting disability benefits for 24 months
If you're not receiving these benefits, you must take action to apply for Medicare during your Initial Enrollment Period.
Disability and Special Conditions
You can qualify for Medicare before age 65 under specific medical circumstances. After receiving Social Security Disability Insurance (SSDI) for 24 consecutive months, you become eligible for Medicare coverage regardless of your age.
| Condition | Waiting Period | Automatic Enrollment |
|---|---|---|
| SSDI Recipients | 24 months | Yes |
| ALS (Lou Gehrig's Disease) | None | Yes |
| End-Stage Renal Disease | Varies | No |
People diagnosed with Amyotrophic Lateral Sclerosis (ALS) receive Medicare coverage immediately upon SSDI approval. Those with End-Stage Renal Disease (ESRD) requiring dialysis or a kidney transplant can also qualify, though the enrollment process differs slightly.
Determining Your Enrollment Period
Medicare enrollment isn't open year-round for most people. Understanding which enrollment period applies to your situation helps you avoid coverage gaps and late enrollment penalties.
Initial Enrollment Period
Your Initial Enrollment Period (IEP) spans seven months total. It includes the three months before your 65th birthday month, your birthday month itself, and the three months following. This window gives you flexibility to apply for Medicare at the time that best suits your needs.
Coverage start dates depend on when you enroll:
- Three months before birthday month: Coverage begins the first day of your birthday month
- During birthday month: Coverage begins the first day of the following month
- Month after birthday: Coverage begins two months later
- Two months after birthday: Coverage begins three months later
The official Medicare enrollment guidelines provide detailed information about how timing affects your coverage start date.
Special Enrollment Period
If you have qualifying employer coverage when you turn 65, you can delay Medicare enrollment without penalty. This Special Enrollment Period (SEP) extends for eight months after your employment ends or your group health coverage terminates, whichever comes first.
Working past 65 with employer coverage that qualifies as creditable coverage protects you from late enrollment penalties. However, you need to understand whether your employer coverage meets Medicare's standards for creditable coverage.
General Enrollment Period
Missing your Initial Enrollment Period or Special Enrollment Period means waiting until the General Enrollment Period. This runs from January 1 through March 31 each year, with coverage beginning July 1. Late enrollment penalties may apply to both Part A (if you must pay premiums) and Part B.
Application Methods for Medicare Coverage
You can apply for Medicare through several channels, each offering different advantages depending on your circumstances and preferences.
Online Application Process
The Social Security Administration website provides the most convenient application method for most people. Creating an account allows you to complete the process from home at your own pace.
Steps to apply online:
- Visit the Social Security website and create or access your my Social Security account
- Navigate to the Medicare application section
- Complete all required information about your work history and current coverage
- Review and submit your application
- Receive confirmation and estimated processing timeline
Online applications typically process faster than paper submissions and allow you to track your application status. The Medicare account login system now offers multiple secure verification methods including ID.me and Login.gov.
Telephone Application
Calling Social Security directly connects you with representatives who can guide you through the application process. This method works well if you have questions or need assistance understanding specific requirements.
Contact Social Security at 1-800-772-1213 (TTY 1-800-325-0778) between 8:00 a.m. and 7:00 p.m. local time, Monday through Friday. Wait times vary, so calling early in the week or early in the day often reduces hold time.
In-Person Application
Visiting your local Social Security office allows face-to-face assistance with your Medicare application. Schedule an appointment in advance to minimize wait time and ensure a representative is available to help you.
Bring required documentation including:
- Proof of age (birth certificate or passport)
- Proof of citizenship or legal residency
- W-2 forms or tax returns from the previous year
- Information about current health insurance coverage
Choosing Your Medicare Coverage Options
When you apply for Medicare, you make important decisions about which parts of Medicare you need and whether to add supplemental coverage.
Original Medicare Components
Medicare Part A covers hospital stays, skilled nursing facility care, hospice care, and some home health services. Most people don't pay a premium for Part A because they or their spouse paid Medicare taxes while working.
Medicare Part B covers doctor visits, outpatient care, preventive services, and medical equipment. Part B requires a monthly premium that adjusts based on your income. The standard premium for 2026 reflects annual cost adjustments.
Medicare Advantage Alternative
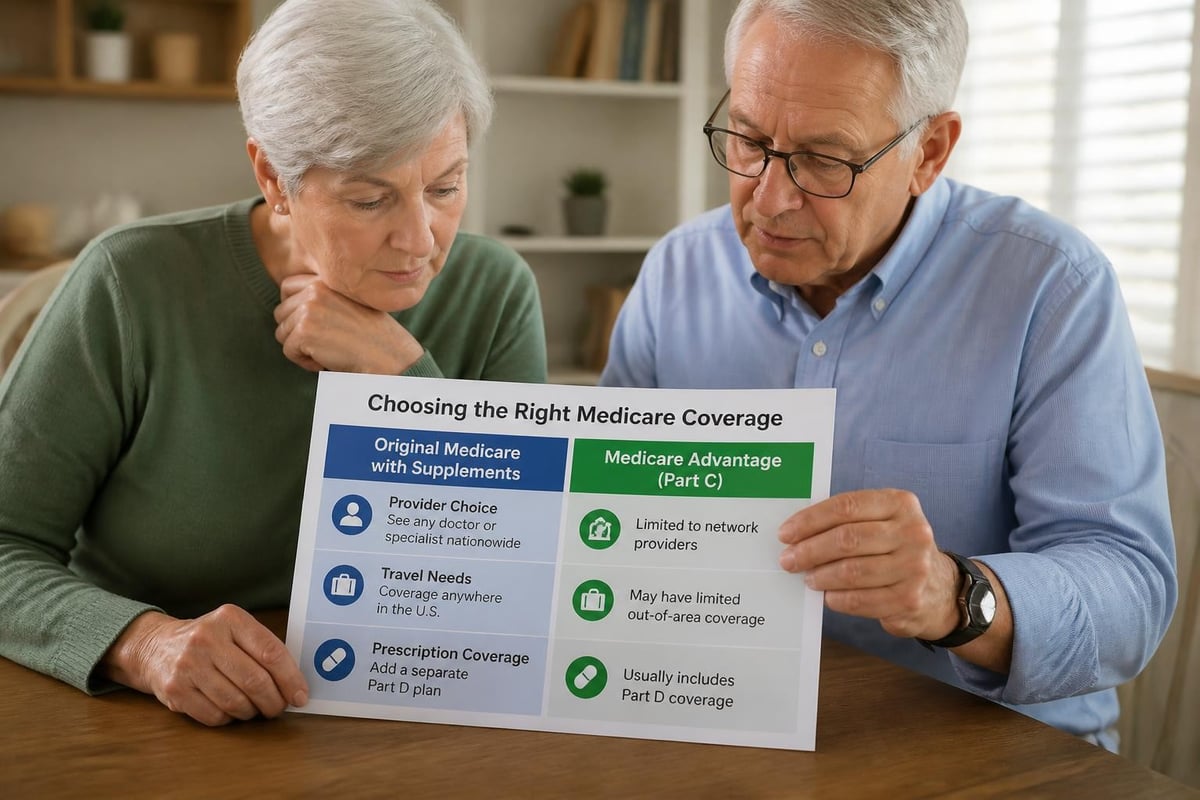
Medicare Advantage plans (Part C) combine Part A and Part B coverage through private insurance companies approved by Medicare. Many plans include prescription drug coverage and additional benefits like dental, vision, and hearing services not covered by Original Medicare.
Comparing Medicare Advantage plans with Original Medicare helps you determine which approach better fits your healthcare needs and budget. The Annual Enrollment Period from October 15 through December 7 allows you to switch between Original Medicare and Medicare Advantage or change plans.
Prescription Drug Coverage
Medicare Part D provides prescription drug coverage through private insurance companies. If you choose Original Medicare, adding a standalone Part D plan protects you from high medication costs and prevents future penalties.
Medicare Advantage plans often include Part D coverage, eliminating the need for a separate prescription drug plan. Review formularies carefully to confirm your medications are covered at acceptable cost-sharing levels.
Supplementing Your Medicare Coverage
Original Medicare leaves gaps in coverage that can result in significant out-of-pocket expenses. Understanding supplemental options helps you create comprehensive protection.
Medicare Supplement Plans Explained
Medicare Supplement Plans fill the gaps in Original Medicare by covering copayments, coinsurance, and deductibles. These standardized plans offer predictable costs and nationwide acceptance by providers who accept Medicare.
| Plan Type | Part A Deductible | Part B Deductible | Part B Excess Charges |
|---|---|---|---|
| Plan F* | Yes | Yes | Yes |
| Plan G | Yes | No | Yes |
| Plan N | Yes | No | No |
*Only available to those eligible for Medicare before January 1, 2020
Enrollment in Medigap plans works best during your Medigap Open Enrollment Period, which begins when you're 65 or older and enrolled in Part B. During this six-month window, insurance companies cannot deny coverage or charge higher premiums based on health conditions.
Coordinating Employer Coverage
If you're still working when you become eligible for Medicare, coordination between your employer coverage and Medicare requires careful planning. Employers with 20 or more employees typically designate employer coverage as primary, with Medicare serving as secondary insurance.
Understanding how applying for Medicare at 65 interacts with your current coverage prevents confusion about which insurance pays first and ensures you maintain continuous protection.
Avoiding Common Enrollment Mistakes
Several pitfalls can create problems during the Medicare enrollment process, but awareness helps you navigate successfully.
Missing Enrollment Deadlines
The most costly mistake involves missing your Initial Enrollment Period without qualifying for a Special Enrollment Period. Late enrollment in Part B results in a 10% premium penalty for each 12-month period you were eligible but not enrolled. This penalty continues for as long as you have Part B.
Part D late enrollment penalties also apply if you go 63 consecutive days without creditable prescription drug coverage after your Initial Enrollment Period ends. This penalty calculation uses the national base beneficiary premium multiplied by 1% for each month of delayed enrollment.
Not Verifying Creditable Coverage
Assuming your current coverage qualifies as creditable without verification can lead to unexpected penalties. Employers must notify you annually whether your coverage meets Medicare's creditable coverage standards.
Request written confirmation from your employer or insurance provider before deciding to delay Medicare enrollment. The Medicare program resources explain creditable coverage requirements in detail.
Overlooking Part A Enrollment
Some people mistakenly believe they should delay all Medicare coverage when they have employer insurance. However, Part A comes premium-free for most people and doesn't typically interfere with Health Savings Account (HSA) contributions unless you're receiving Social Security benefits.
Consult with a tax professional before making decisions about Part A enrollment if you contribute to an HSA, as retroactive Medicare enrollment can create HSA contribution complications.
Special Situations and Considerations
Certain circumstances require additional attention when you apply for Medicare to ensure proper coverage and avoid complications.
Transitioning from COBRA
COBRA coverage doesn't qualify as creditable coverage for delaying Medicare Part B. If you're on COBRA when you turn 65, you should apply for Medicare during your Initial Enrollment Period to avoid penalties.
You can keep COBRA alongside Medicare temporarily, but Medicare becomes your primary insurance. Many people find that Medicare prescription plans offer better value than continuing COBRA coverage after enrolling in Medicare.
Veterans and TRICARE Beneficiaries
Veterans with VA benefits or TRICARE coverage face unique considerations. VA benefits aren't creditable coverage for Medicare purposes, though you can use both simultaneously. TRICARE for Life requires enrollment in both Part A and Part B to maintain TRICARE coverage.
Understanding how Medicare coordinates with military benefits ensures you maximize available resources while maintaining comprehensive protection.
Working Past Age 65
Delaying Medicare while working past 65 requires careful evaluation of your employer coverage size and benefits. Small employer plans (fewer than 20 employees) make Medicare primary, meaning you should enroll in both Part A and Part B at 65.
Larger employer plans that provide creditable coverage allow you to delay Part B without penalty, though you might still want Part A since it's typically premium-free. Track your enrollment periods carefully and apply for Medicare within your Special Enrollment Period when employment ends.
Getting Help with Your Medicare Application
Navigating Medicare enrollment becomes easier with proper guidance and resources. Multiple sources provide assistance tailored to different needs.
State Health Insurance Assistance Programs
Every state operates a State Health Insurance Assistance Program (SHIP) offering free, unbiased Medicare counseling. SHIP counselors help you understand your options, compare plans, and complete enrollment applications without selling any specific products.
These programs provide particularly valuable assistance for people with limited incomes who may qualify for programs that help pay Medicare premiums and cost-sharing.
Licensed Insurance Professionals
Working with experienced insurance professionals who specialize in Medicare provides personalized guidance based on your specific health needs and budget. These experts help you compare different coverage options and explain how various plans work together.
Understanding the comprehensive health insurance and Medicare landscape requires expertise that goes beyond basic eligibility rules to address your individual circumstances.
Official Medicare Resources
The Centers for Medicare & Medicaid Services maintains comprehensive information through Medicare.gov. The USA.gov Medicare guide also provides helpful resources about applying for coverage and understanding your options.
Calling 1-800-MEDICARE (1-800-633-4227) connects you with representatives who can answer questions about eligibility, enrollment, and coverage options 24 hours a day, seven days a week.
Documentation and Information You'll Need
Gathering necessary documents before you apply for Medicare streamlines the process and prevents delays.
Personal Information Requirements
Your Social Security number serves as the primary identifier for your Medicare application. If you're not a U.S. citizen, you'll need documentation proving legal residency status.
Essential documents include:
- Birth certificate or proof of age
- Social Security card or number
- Proof of current health insurance coverage
- Employment information if you're delaying enrollment
Financial and Tax Information
Premium calculations for Part B and Part D depend on your modified adjusted gross income from two years prior. Higher earners pay Income Related Monthly Adjustment Amounts (IRMAA) in addition to standard premiums.
Having tax returns available helps you understand what your premiums will be, though you don't typically need to submit them with your application.
Current Coverage Details
If you have employer coverage, retiree benefits, or other health insurance, document the coverage details including plan names, policy numbers, and coverage effective dates. This information helps Social Security determine whether you're subject to late enrollment penalties.
Understanding Medicare registration requirements ensures you provide all necessary information the first time, avoiding follow-up requests that delay your coverage start date.
Understanding Premium Costs and Financial Assistance
Medicare involves various costs depending on which parts you choose and your income level. Planning for these expenses helps you budget appropriately.
Standard Premium Amounts
Most people pay no premium for Part A if they or their spouse worked and paid Medicare taxes for at least 10 years. Those who don't meet this requirement can purchase Part A, with 2026 premiums reflecting current rates.
Part B requires a monthly premium for everyone, with the standard amount adjusted annually. Higher-income beneficiaries pay additional amounts through IRMAA surcharges.
Programs for Limited Income
Several programs help people with limited income and resources pay Medicare costs. The Medicare Savings Programs (MSPs) pay Part B premiums and sometimes other cost-sharing for those who qualify based on income and assets.
Extra Help, also called the Low-Income Subsidy (LIS), assists with Part D prescription drug costs including premiums, deductibles, and copayments. Annual income and resource limits determine eligibility for these programs.
Income-Related Adjustments
IRMAA affects both Part B and Part D premiums for beneficiaries whose modified adjusted gross income exceeds certain thresholds. These amounts adjust annually, and Social Security bases the calculation on tax returns from two years prior.
Recent life-changing events like marriage, divorce, death of a spouse, or retirement can justify appeals for IRMAA reductions if your current income differs significantly from what tax returns show.
Applying for Medicare involves understanding eligibility, choosing the right enrollment period, and selecting coverage that matches your healthcare needs and budget. With proper preparation and awareness of deadlines, you can navigate the enrollment process confidently and secure the protection you deserve. At Moser Insurance Group Inc, we help individuals and families understand their Medicare options with clear guidance and personalized support, ensuring you make informed decisions without pressure or confusion about your coverage choices.
Recent Comments