
Finding affordable life insurance for seniors can feel overwhelming, especially with so many options and varying price points. Whether you're in Greensboro, Winston Salem, High Point, Kernersville, or elsewhere in the Triad Area, understanding your choices helps you secure the financial protection your family deserves without straining your budget. The good news is that coverage designed specifically for older adults has become more accessible and affordable in 2026, with multiple policy types tailored to different health situations and financial goals.
Understanding Life Insurance Options for Older Adults
Seniors today have more choices than ever when shopping for coverage. The key to finding affordable protection starts with understanding which policy types align with your health status, budget, and coverage goals.
Term Life Insurance for Seniors
Term life insurance provides coverage for a specific period, typically 10, 15, or 20 years. This option often represents the most budget-friendly choice for seniors who want substantial coverage at lower premiums. According to comprehensive rate analyses, healthy seniors in their 60s can secure significant coverage amounts for reasonable monthly costs.
Key benefits of term policies include:
- Lower premiums compared to permanent coverage
- Straightforward coverage with no complex features
- Flexibility to choose coverage amounts matching specific needs
- No cash value component, keeping costs focused purely on protection
The main consideration is that coverage expires at the end of the term. If you outlive the policy period, no benefit is paid. This makes term coverage ideal for specific timeframes, such as covering a mortgage or supporting a spouse until retirement income stabilizes.
Whole Life Insurance Benefits
Whole life insurance offers lifelong protection with premiums that never increase. While monthly costs run higher than term policies, whole life coverage builds cash value over time that you can borrow against or withdraw if needed.
For seniors seeking guaranteed coverage regardless of how long they live, whole life provides certainty. Many policies designed for older adults feature simplified underwriting, making approval easier even with moderate health concerns.
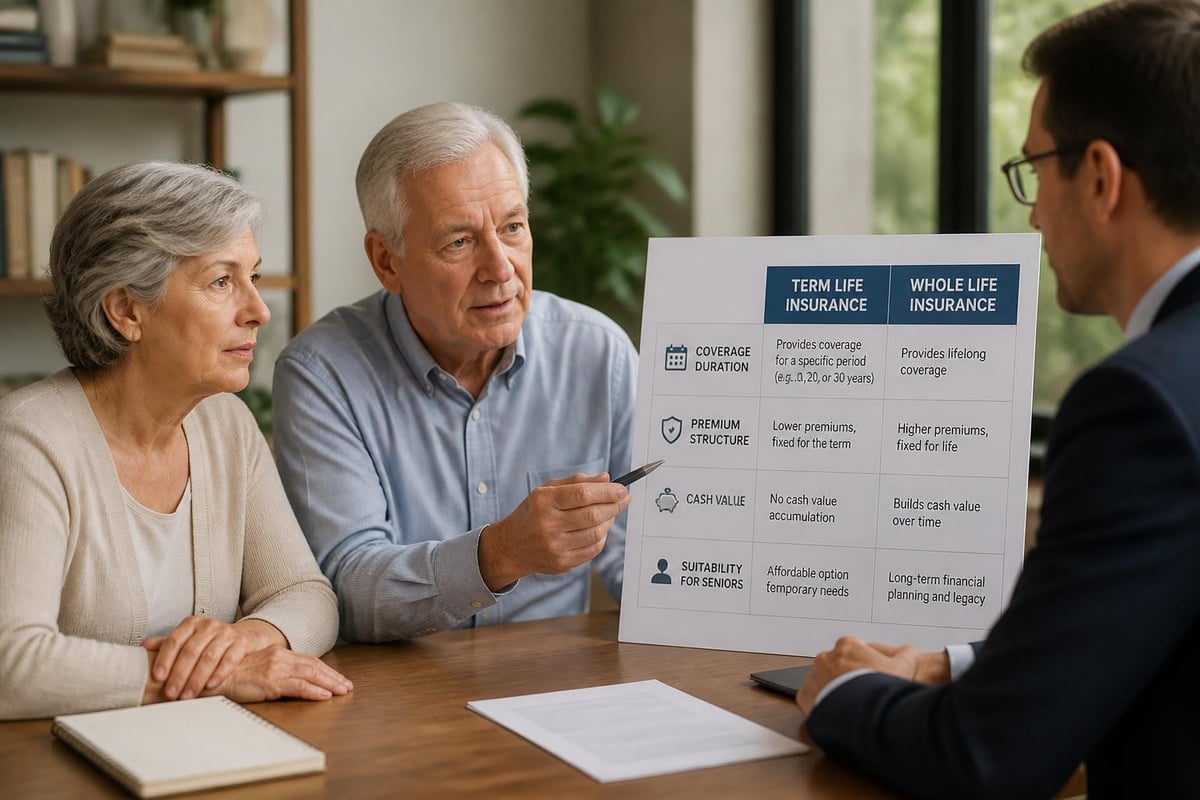
| Policy Type | Coverage Duration | Premium Structure | Cash Value | Best For |
|---|---|---|---|---|
| Term Life | 10-30 years | Lower, fixed | None | Temporary needs, budget-conscious |
| Whole Life | Lifetime | Higher, fixed | Yes, grows over time | Permanent protection, estate planning |
| Guaranteed Issue | Lifetime | Moderate to high | Limited or none | Those with serious health issues |
Factors That Affect Senior Life Insurance Costs
Understanding what drives your premiums helps you find the most affordable life insurance for seniors. Insurance companies evaluate several key factors when determining rates.
Age and Health Status
Your age at application significantly impacts premium costs. A 65-year-old typically pays substantially less than a 75-year-old for the same coverage amount. Health conditions, prescription medications, and lifestyle factors also play major roles.
Medical underwriting typically examines:
- Current health conditions and diagnoses
- Prescription medication history
- Height and weight ratios
- Tobacco use status
- Family medical history
- Recent hospitalizations or surgeries
Many carriers now offer no-exam policies that approve coverage based on health questionnaires alone, particularly beneficial for seniors who want to avoid medical testing.
Coverage Amount and Policy Length
The death benefit amount you select directly correlates with premium costs. A $100,000 policy costs significantly less than $500,000 in coverage. Consider your actual financial obligations when selecting coverage amounts rather than choosing arbitrary numbers.
For term policies, longer coverage periods mean higher premiums. A 10-year term costs less monthly than a 20-year term, even when purchased on the same day by the same person.
Geographic Location Considerations
Your location affects rates due to varying state regulations and regional cost factors. Seniors in the Triad Area benefit from competitive markets in North Carolina, where multiple carriers compete for business in Greensboro, Winston Salem, High Point, and Kernersville.
Working with local professionals who understand regional pricing and carrier availability can help identify the best rates. Contact Moser Insurance Group Inc at 336-862-1763 or moserinsurancegroup@gmail.com for personalized guidance on options available in your area.
How to Find the Most Affordable Coverage
Shopping strategically makes a significant difference in securing affordable life insurance for seniors. Follow these proven approaches to maximize your coverage while minimizing costs.
Compare Multiple Carriers
Different insurance companies specialize in different risk profiles. One carrier might offer excellent rates for seniors with diabetes, while another provides better pricing for those with heart conditions. Expert comparisons reveal substantial price variations between companies for identical coverage.
Steps for effective comparison:
- Request quotes from at least three to five different carriers
- Ensure quotes reflect identical coverage amounts and terms
- Review each company's financial strength ratings
- Check customer service reviews and complaint ratios
- Verify what medical requirements each carrier demands
Consider Simplified Issue Policies
Simplified issue policies skip medical exams, requiring only health questionnaires for approval. These policies cost more than fully underwritten coverage but less than guaranteed issue options. They work well for seniors with minor health concerns who want moderate coverage amounts.
According to senior-focused insurers, simplified issue policies typically cap coverage at $25,000 to $100,000, making them suitable for final expense needs or supplemental protection.
Evaluate Guaranteed Issue Options
Guaranteed issue life insurance accepts all applicants regardless of health status. No medical questions, no exams, no possibility of denial. The tradeoff comes in higher premiums and lower coverage limits, typically maxing out between $10,000 and $25,000.
These policies usually include graded death benefits, meaning if you pass away within the first two or three years from natural causes, beneficiaries receive a return of premiums paid plus interest rather than the full death benefit. Accidental death typically pays full benefits immediately.
Specific Policy Types Worth Considering
Different policy structures serve different senior needs. Understanding specialized options helps match coverage to your specific situation.
Final Expense Insurance
Final expense insurance, also called burial insurance, specifically covers end-of-life costs including funeral services, burial or cremation, outstanding medical bills, and estate settlement expenses. Coverage amounts typically range from $5,000 to $25,000, aligning with average funeral costs.
These policies feature simplified underwriting and remain affordable for seniors in their 70s and 80s. Final expense coverage provides peace of mind that loved ones won't face financial burdens during difficult times.
Senior Term Life Policies
Specialized term products designed for older applicants extend coverage into later years. Senior term life options accommodate applicants aged 50 to 70 with terms ranging from 10 to 20 years.
While premiums run higher than term policies purchased in your 30s or 40s, they still cost considerably less than permanent coverage. This makes senior term life practical for covering specific obligations like helping grandchildren with college costs or supporting a spouse for a defined period.
Group Coverage Through Organizations
Many professional associations, alumni groups, and membership organizations offer group life insurance to members. These policies typically feature simplified underwriting and competitive group rates. Coverage amounts may be limited, but they can supplement individual policies cost-effectively.
AARP, for instance, provides term life insurance to members with straightforward application processes. Fraternal organizations and unions often extend similar benefits to senior members.
Maximizing Value While Minimizing Cost
Getting the best value from affordable life insurance for seniors involves more than just finding low premiums. Consider these strategies to optimize your coverage.
Bundle Policies When Possible
Some carriers offer multi-policy discounts when you purchase life insurance alongside other coverage types. If you're shopping for supplemental health coverage or Medicare Advantage plans, ask about bundling opportunities with life insurance.
Pay Annually Instead of Monthly
Most insurance companies charge convenience fees for monthly premium payments, typically adding 5% to 8% to annual costs. Paying premiums annually eliminates these fees, reducing overall expenses. If monthly payments fit your budget better, verify the fee structure before committing.
Lock in Rates Early
For term policies particularly, premiums increase with age. If you're approaching a birthday that moves you into a higher age bracket, applying before that birthday can save considerable money over the policy lifetime. Age brackets typically change every five years (60-64, 65-69, 70-74, etc.).
Additional cost-saving considerations:
- Improve health metrics before applying (weight loss, blood pressure control, tobacco cessation)
- Choose level term lengths matching actual needs rather than maximum available
- Review beneficiary designations to avoid estate taxes reducing benefits
- Ask about wellness program discounts offered by some carriers
- Consider rider options carefully, adding only those providing genuine value
Understanding Policy Features and Riders
Policy riders add optional benefits to base coverage, sometimes increasing value without dramatically raising costs. Evaluate which riders genuinely benefit your situation.
Accelerated Death Benefit Rider
This rider allows accessing a portion of your death benefit early if diagnosed with a terminal illness. Most carriers include this feature at no additional cost. It provides financial flexibility during challenging times without reducing coverage for beneficiaries significantly.
Waiver of Premium Rider
If you become disabled and unable to work, this rider pays your premiums to keep coverage active. Costs vary but typically add 5% to 10% to base premiums. Consider this option if you're still working and depend on employment income to afford premiums.
Long-Term Care Rider
Some permanent life insurance policies offer long-term care riders that allow using death benefits for qualifying care expenses. This hybrid approach addresses two concerns with one policy but requires careful evaluation of costs versus standalone long-term care coverage.
Application Process and Timeline
Understanding what to expect during the application process helps you prepare and potentially speed up approval.
Required Information and Documentation
Applications request detailed personal and health information. Gather relevant documents before starting to streamline the process.
Typical documentation includes:
- Government-issued identification
- Social Security number
- Complete medication list with dosages
- Contact information for current physicians
- Details about existing life insurance coverage
- Beneficiary information including full names and birthdates
Medical Underwriting Procedures
For policies requiring medical underwriting, expect a paramedical exam scheduled at your convenience. The examiner collects blood and urine samples, measures height and weight, takes blood pressure, and completes a health questionnaire.
Exams typically occur at your home and take 30 to 45 minutes. Results process within one to two weeks. No-exam policies bypass this step entirely, often providing approval within 24 to 48 hours.
Approval and Policy Delivery
Once approved, you'll receive a policy contract outlining all terms, conditions, and exclusions. Review this document carefully before the free look period expires, typically 10 to 30 days depending on your state. During this period, you can cancel for a full premium refund if the policy doesn't meet your needs.
Common Mistakes to Avoid
Seniors shopping for life insurance frequently encounter these pitfalls. Awareness helps you navigate the process more effectively.
Focusing Solely on Price
The cheapest premium doesn't always represent the best value. A financially weak carrier might offer low rates but pose risks if they can't pay claims. Review A.M. Best ratings, focusing on companies rated A- or higher for financial stability.
Underestimating Coverage Needs
Calculate actual financial obligations rather than guessing at coverage amounts. Consider outstanding debts, final expenses, estate taxes, and income replacement for dependents. Term life insurance costs vary significantly based on coverage amounts, so accurate needs assessment prevents overpaying or leaving gaps.
Delaying Application
Every birthday increases premium costs. Health changes also impact eligibility and pricing. If you're considering coverage, apply while you're healthy and premiums remain affordable. Waiting rarely improves your situation.
Providing Inaccurate Health Information
Honest disclosure protects your beneficiaries. Material misrepresentations can void coverage, leaving loved ones without promised benefits. Insurance companies verify information during claims processes, and inconsistencies may result in denied claims or reduced benefits.
Special Considerations for Different Senior Scenarios
Your specific life situation influences which affordable life insurance for seniors options work best.
Seniors with Pre-Existing Conditions
Health challenges don't eliminate coverage options. Guaranteed issue policies accept all applicants. Simplified issue policies accommodate many conditions. Some carriers specialize in high-risk applicants, offering competitive rates for specific health profiles.
Diabetes, high blood pressure, and high cholesterol, when well-controlled, often qualify for standard or preferred rates with certain carriers. Discuss your specific conditions with experienced agents who know which companies handle particular health situations favorably.
Retirees on Fixed Incomes
Budget constraints make premium affordability critical. Consider smaller coverage amounts that fit comfortably within monthly expenses. A $15,000 policy covering final expenses provides valuable protection without straining finances. Review benefit programs through former employers, unions, or professional associations for cost-effective supplemental coverage.
Seniors Concerned About Estate Planning
Permanent life insurance creates tax-advantaged wealth transfer. Death benefits pass to beneficiaries income-tax-free, providing liquidity for estate settlement without forcing asset sales. Work with financial advisors and estate attorneys to structure coverage maximizing benefits for heirs while minimizing tax burdens.
Resources and Professional Guidance
Professional assistance helps navigate the complex life insurance marketplace effectively.
Working with Independent Insurance Agents
Independent agents represent multiple carriers, providing objective comparisons across companies. Unlike captive agents who sell for single carriers, independent professionals match your needs with the best available options regardless of company.
Agents familiar with the Triad Area understand regional considerations affecting Greensboro, Winston Salem, High Point, and Kernersville residents. Local expertise combined with broad carrier access creates optimal shopping experiences.
Online Quote Comparison Tools
Multiple websites offer instant quote comparisons across carriers. While convenient for preliminary research, remember that online quotes reflect best-case scenarios for applicants in excellent health. Your actual premiums may differ based on underwriting results.
Use online tools for general price ranges, then work with professionals for accurate quotes reflecting your specific health and financial situation. Combining online research with expert guidance produces the best outcomes.
Educational Resources
Reputable sources provide valuable information helping you make informed decisions. Comprehensive guides break down policy types, pricing factors, and carrier comparisons. Specialized senior life insurance information addresses age-specific considerations and common questions.
Stay informed but verify information with licensed professionals before making final decisions. Insurance regulations change regularly, and current information ensures compliance and optimal coverage.
Securing affordable life insurance for seniors requires understanding your options, comparing carriers carefully, and matching coverage to your specific needs and budget. Whether you need term coverage for temporary protection or permanent policies for lifelong security, solutions exist across all health situations and financial circumstances. Moser Insurance Group Inc helps seniors in the Triad Area navigate these decisions with clear, pressure-free guidance. Reach out at 336-862-1763, email moserinsurancegroup@gmail.com, or visit moserinsurancegroup.com to discuss your life insurance needs and discover the coverage options that protect your family's financial future most effectively.
Recent Comments