

Understanding aetna senior supplemental eligibility represents a critical step for seniors seeking to reduce out-of-pocket healthcare costs. As Medicare beneficiaries approach retirement age or become eligible through disability, knowing when and how to qualify for supplemental coverage can save thousands of dollars annually. This comprehensive guide breaks down the specific requirements, enrollment windows, and strategic considerations that affect whether you can secure Aetna supplemental insurance.
What Defines Aetna Senior Supplemental Eligibility
Aetna senior supplemental eligibility hinges on several foundational requirements that every applicant must meet. The primary criterion requires enrollment in both Medicare Part A and Part B, which form the backbone of Original Medicare coverage. Without active enrollment in both parts, you cannot purchase a Medicare Supplement plan from Aetna or any other carrier.
Age plays a significant role in determining eligibility. Most individuals become eligible for Medicare at age 65, which automatically triggers their window to apply for supplemental coverage. However, younger individuals who receive Social Security Disability Insurance (SSDI) for 24 consecutive months also gain Medicare eligibility, though supplemental insurance rules vary by state for those under 65.
The Medicare Parts A and B Requirement
Your aetna senior supplemental eligibility directly depends on maintaining active coverage under Original Medicare. Part A typically covers hospital stays, skilled nursing facility care, hospice, and some home health services. Part B addresses outpatient care, doctor visits, preventive services, and medical equipment.
Key enrollment facts:
- You must have both Part A and Part B active
- Part A premium-free coverage requires sufficient work credits
- Part B requires monthly premium payments (standard $174.70 in 2026)
- Dropping either part terminates your Medigap eligibility
Most Americans qualify for premium-free Part A through their own or their spouse's work history. Part B, however, requires an ongoing monthly premium that gets deducted from Social Security benefits or paid directly through quarterly billing. The Centers for Medicare & Medicaid Services provides detailed information about how these foundational requirements work together.
Critical Enrollment Periods for Supplemental Coverage
Understanding when you can apply dramatically affects your aetna senior supplemental eligibility and your ability to secure coverage without medical underwriting. The Medicare Supplement Open Enrollment Period represents the golden window when federal law guarantees your acceptance regardless of health status.
This six-month window begins the first day of the month you turn 65 AND have Part B coverage. For example, if you turn 65 on June 15, 2026, and enrolled in Part B effective June 1, your open enrollment period runs from June 1 through November 30, 2026.
Guaranteed Issue Rights Beyond Open Enrollment
Certain circumstances restore your aetna senior supplemental eligibility with guaranteed issue protections even after your initial enrollment period expires. These special situations prevent insurance carriers from denying coverage or charging higher premiums based on health conditions.
| Qualifying Event | Time Frame | Coverage Options |
|---|---|---|
| Losing employer coverage | 63 days after loss | Any Medigap plan sold in your state |
| Medicare Advantage plan leaving service area | 63 days from notification | Any Medigap plan sold in your state |
| Moving out of plan service area | 63 days after move | Any Medigap plan sold in your state |
| Company goes bankrupt | 63 days from notice | Plan A, B, C, F, K, or L |
Working with experienced advisors in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, helps ensure you don't miss these critical windows. For personalized guidance on Medicare supplement options, local expertise makes a significant difference.
Geographic and State-Specific Considerations
Your location influences aetna senior supplemental eligibility in ways many seniors overlook. While federal law establishes baseline protections, individual states can extend additional consumer safeguards that broaden when and how you can enroll in supplemental coverage.
Some states mandate guaranteed issue rights for beneficiaries under age 65 who qualify for Medicare through disability. Others require annual open enrollment periods during which carriers must accept all applicants regardless of health status. North Carolina, which includes the Triad Area communities, follows federal minimum standards but offers certain protections worth understanding.
Medical Underwriting After Initial Enrollment
Once your Medicare Supplement Open Enrollment Period closes, aetna senior supplemental eligibility becomes subject to medical underwriting in most situations. Insurance carriers review your health history, current conditions, and prescription medications to determine whether they'll accept your application.
Common underwriting considerations:
- Pre-existing conditions requiring ongoing treatment
- Recent hospitalizations or surgeries
- Chronic conditions like diabetes, heart disease, or COPD
- Prescription medication lists and dosages
- Lifestyle factors including tobacco use
This underwriting process explains why timing matters so significantly. During your guaranteed issue period, none of these health factors can impact your acceptance or premiums. Outside that window, they become primary determinants of eligibility. The Medicare.gov Medigap resource page offers additional context about how underwriting affects coverage access.
Special Eligibility Scenarios and Exceptions
Aetna senior supplemental eligibility extends beyond the standard age 65 pathway through several less common but equally important scenarios. Understanding these alternative routes ensures you don't miss opportunities for guaranteed coverage when traditional timing doesn't apply to your situation.
Disability-Based Eligibility Under 65
Individuals receiving SSDI payments gain Medicare eligibility after 24 months of benefits, regardless of age. This creates a unique pathway to supplemental coverage for younger beneficiaries who may face significant medical expenses. However, not all states require carriers to offer Medigap policies to individuals under 65.
North Carolina does mandate that insurance companies make at least one Medigap plan available during a six-month window starting when a disabled individual first enrolls in Medicare Part B. This state-specific protection enhances aetna senior supplemental eligibility for disabled Medicare beneficiaries in the Triad Area and throughout North Carolina.
End-Stage Renal Disease Considerations
Medicare eligibility through End-Stage Renal Disease (ESRD) follows different rules that historically complicated supplemental insurance access. Before recent changes, carriers could deny Medigap applications from individuals with ESRD. Current regulations now prevent this discrimination, though specific timing requirements apply.

If you develop ESRD while already enrolled in a Medicare Supplement plan, the carrier cannot drop your coverage. New applicants with ESRD now receive guaranteed issue rights during their Medicare Supplement Open Enrollment Period, identical to other beneficiaries. Medicare’s official eligibility information clarifies these protections.
Plan Types and Benefit Standardization
Understanding which supplemental plans Aetna offers in your area forms another component of comprehensive aetna senior supplemental eligibility knowledge. Medicare standardizes Medigap plans into lettered categories (A, B, C, D, F, G, K, L, M, and N), with each letter representing identical benefits regardless of which insurance company sells it.
However, not every carrier offers every plan type in every state. Aetna typically focuses on the most popular options, particularly Plan G, which has become the standard recommendation for new Medicare beneficiaries since Plan F became unavailable to those newly eligible after January 1, 2020.
Comparing Available Aetna Plan Options
| Plan Type | Part A Deductible | Part B Deductible | Part B Excess Charges | Foreign Travel Emergency |
|---|---|---|---|---|
| Plan G | Covers | You pay ($240 in 2026) | Covers 100% | 80% after deductible |
| Plan N | Covers | You pay | You pay | 80% after deductible |
| Plan K | 50% coverage | You pay | You pay | Not covered |
| Plan L | 75% coverage | You pay | You pay | Not covered |
The most popular choice for new enrollees continues to be Plan G, which provides comprehensive coverage with only the annual Part B deductible remaining as an out-of-pocket expense. Your aetna senior supplemental eligibility applies equally across all plan types during guaranteed issue periods, allowing you to select based on coverage preferences rather than acceptance concerns.
Application Process and Documentation Requirements
Securing your aetna senior supplemental eligibility requires proper documentation and timely application submission. Unlike Medicare Advantage plans that follow specific annual enrollment periods, Medigap applications can be submitted year-round, though your acceptance terms depend heavily on when you apply relative to your guaranteed issue periods.
Essential documents for application:
- Medicare card showing Part A and Part B coverage
- Government-issued photo identification
- Social Security number verification
- Current prescription medication list
- Contact information including phone (336-862-1763) and email (moserinsurancegroup@gmail.com)
Most carriers, including Aetna, now offer streamlined online applications that can be completed in under 30 minutes during guaranteed issue periods. Outside these windows, expect more detailed health questionnaires that may require additional medical records or physician statements.
Working with Licensed Insurance Advisors
The complexity surrounding aetna senior supplemental eligibility makes professional guidance valuable, particularly for those with unique circumstances or health concerns. Licensed Medicare insurance agents understand state-specific regulations, carrier underwriting standards, and timing strategies that maximize your chances of approval at the best available rates.
For residents throughout the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, local advisors provide face-to-face consultations that clarify confusing eligibility questions. You can explore your options and schedule an appointment to review your specific situation with experienced professionals who understand North Carolina's Medicare landscape.
Premium Factors and Cost Considerations
While eligibility determines whether you can obtain coverage, understanding premium structures helps you budget appropriately once you've secured your aetna senior supplemental eligibility. Medigap premiums vary based on several factors, with pricing methods differing by carrier and state regulations.
Three Primary Rating Methods
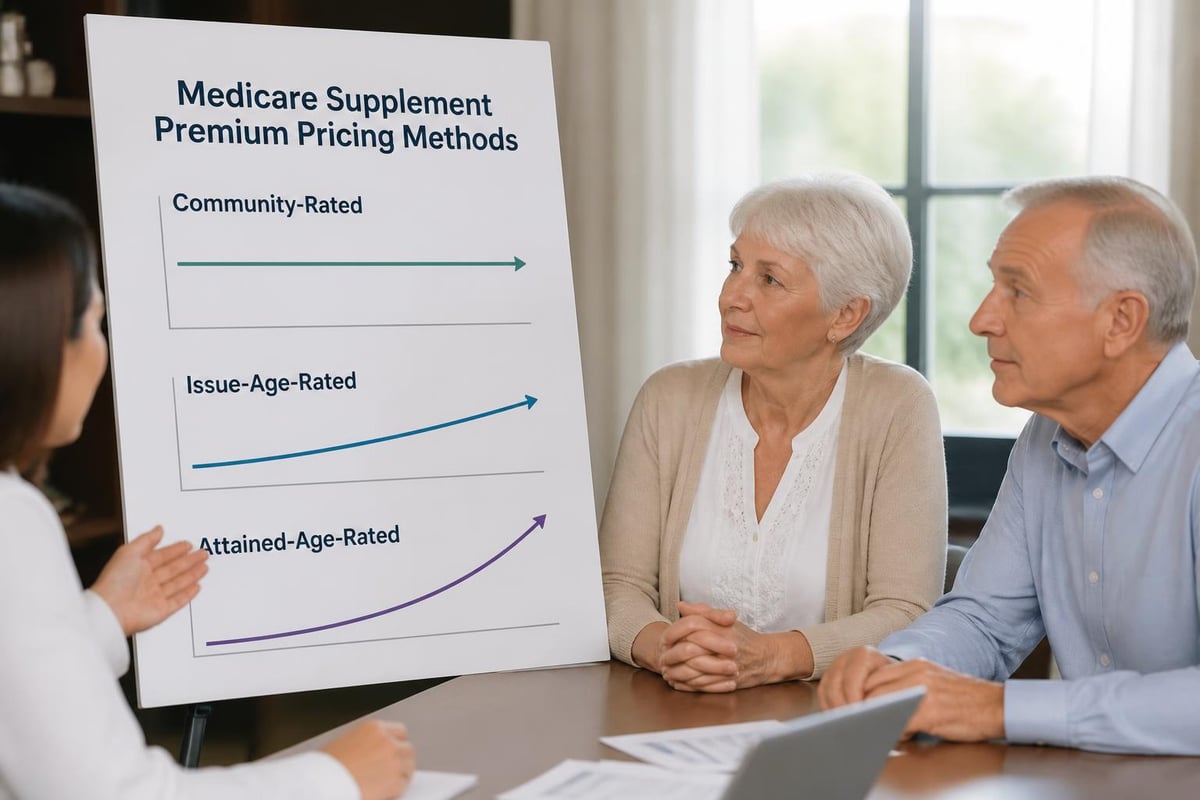
Insurance carriers use one of three approaches to calculate Medicare Supplement premiums, each affecting how your costs evolve over time:
Community-rated (no-age-rated): Everyone pays the same premium regardless of age, with increases only from inflation and claims experience.
Issue-age-rated: Premium based on your age when you first buy the policy, with future increases only from inflation and claims.
Attained-age-rated: Premium increases as you get older, in addition to inflation and claims adjustments.
Aetna's specific rating method varies by state and plan type. During your guaranteed issue period, these premium calculation methods don't affect your aetna senior supplemental eligibility, but they significantly impact long-term affordability. North Carolina allows all three rating methods, so comparing carriers beyond just Aetna often reveals substantial price differences for identical coverage.
Understanding how household income affects Medicare costs extends beyond Medigap premiums. Higher earners pay Income-Related Monthly Adjustment Amounts (IRMAA) on Part B and Part D premiums. While IRMAA doesn't directly impact aetna senior supplemental eligibility, budgeting for total Medicare costs requires factoring these surcharges when modified adjusted gross income exceeds threshold amounts.
Coordination with Medicare Advantage and Other Coverage
Your aetna senior supplemental eligibility becomes relevant only when you maintain Original Medicare as your primary coverage. This creates an important distinction between Medicare Supplement insurance and Medicare Advantage plans, which function as alternatives to Original Medicare rather than supplements to it.
You cannot simultaneously have both a Medicare Advantage plan and a Medigap policy. Federal law prohibits insurance carriers from selling you supplemental insurance if you're enrolled in Medicare Advantage. This protection prevents confusion and duplicate coverage scenarios.
Transitioning Between Coverage Types
Many seniors wonder about switching from Medicare Advantage to Original Medicare with a supplement, or vice versa. Your ability to make these changes depends partly on timing and partly on your health status.
Switching from Medicare Advantage to Original Medicare with a Medigap policy outside guaranteed issue periods requires medical underwriting in most situations. However, specific trial rights and special enrollment periods can restore guaranteed issue protections. For example, if you enrolled in Medicare Advantage during your initial enrollment period, you have a 12-month trial right to switch to Original Medicare and apply for Medigap Plan A or B with guaranteed acceptance.
For comprehensive comparisons between supplemental coverage and other Medicare options, reviewing information about top Medicare Advantage plans helps clarify which approach best suits your healthcare needs and financial situation.
Employer Coverage Considerations
Working past age 65 or receiving retiree health benefits creates unique scenarios affecting aetna senior supplemental eligibility timing and strategy. The interaction between employer coverage and Medicare determines whether delaying enrollment makes sense and how it impacts your supplement options.
If you have creditable employer coverage through active employment, you can delay Medicare Part B enrollment without penalty until that coverage ends. However, this delay also postpones your Medicare Supplement Open Enrollment Period, which doesn't begin until you actually enroll in Part B.
Coordinating Benefits Effectively
When employer coverage ends, you receive a guaranteed issue period for Medigap regardless of how long you delayed Medicare enrollment. This special enrollment period lasts 63 days from when your employer coverage terminates, giving you protected access to any Medigap plan sold in your state.
Employer coverage decision factors:
- Compare employer plan costs versus Medicare plus Medigap premiums
- Evaluate prescription drug coverage under each option
- Consider whether employer plan provides creditable Part D coverage
- Assess provider network restrictions under employer plan
- Review coverage for spouse or dependents
For many individuals with retiree health benefits, the employer plan may coordinate with Medicare rather than replace it. In these situations, your aetna senior supplemental eligibility still applies, though you should verify whether the employer coverage duplicates what a Medigap policy would provide. The NerdWallet Medicare eligibility guide explores these coordination scenarios in greater detail.
State-Specific Protections and Extended Rights
While federal law establishes baseline aetna senior supplemental eligibility standards, state regulations sometimes provide enhanced consumer protections that expand when and how you can access coverage. Understanding your state's specific rules prevents missed opportunities for guaranteed issue rights.
North Carolina follows federal minimum standards for Medigap eligibility but includes specific provisions for disabled Medicare beneficiaries under 65. The state requires carriers to offer at least one Medigap plan to individuals qualifying for Medicare through disability, though companies can choose which plan type to make available.
Annual Open Enrollment Periods in Select States
Some states mandate annual Medigap open enrollment periods during which carriers must accept all applicants within specified age ranges or circumstances. These state-specific windows dramatically expand aetna senior supplemental eligibility beyond federal requirements.
California, Oregon, and New York number among states with birthday rules or anniversary provisions allowing existing Medigap policyholders to switch plans within certain timeframes without medical underwriting. While North Carolina doesn't currently maintain such provisions, staying informed about potential legislative changes helps maximize your coverage options.
Health Status Impact on Approval and Rates
Outside guaranteed issue periods, your health becomes the primary factor affecting aetna senior supplemental eligibility through medical underwriting processes. Insurance carriers evaluate risk by reviewing medical history, current conditions, and treatment patterns to determine acceptance and premium rates.
Common health conditions that typically trigger underwriting scrutiny include cardiovascular disease, diabetes with complications, chronic obstructive pulmonary disease, cancer within recent years, and autoimmune disorders requiring ongoing treatment. Tobacco use also significantly impacts both acceptance likelihood and premium amounts when underwriting applies.
Strategies for Applicants with Health Concerns
If you missed your guaranteed issue period and face potential underwriting challenges, several strategies can improve your chances of securing coverage:
- Apply during special enrollment periods when guaranteed issue rights restore coverage access
- Compare multiple carriers as underwriting standards vary between companies
- Consider less comprehensive plans like Plan K or L that insurers more readily approve
- Improve manageable health factors like tobacco cessation before applying
- Work with experienced advisors who understand which carriers have more flexible underwriting
The importance of securing coverage during your initial guaranteed issue window cannot be overstated. Once that six-month period closes, recovering comparable access requires either qualifying for another guaranteed issue situation or passing medical underwriting. Resources from local Medicare advisors in Greensboro provide region-specific guidance for navigating these timing challenges.
Prescription Drug Coverage Integration
Understanding how prescription drug coverage interacts with aetna senior supplemental eligibility represents another essential consideration. Medicare Supplement plans don't include prescription drug benefits, requiring separate enrollment in Medicare Part D or alternative creditable coverage.
Your Part D enrollment follows distinct rules from Medigap, with specific annual enrollment periods and late enrollment penalties for gaps in coverage. Most beneficiaries enroll in standalone Part D plans alongside their Medigap policies, creating comprehensive coverage that addresses medical services, hospital care, and prescription medications.
When evaluating your complete Medicare strategy, comparing the best Medicare Part D plans available in your area ensures you select prescription coverage that coordinates effectively with your supplemental insurance while minimizing total out-of-pocket costs.
Financial Assistance and Premium Support Options
While aetna senior supplemental eligibility itself isn't means-tested, understanding available financial assistance programs helps seniors on limited incomes afford comprehensive Medicare coverage. Several programs reduce premium burdens for qualifying beneficiaries.
Medicare Savings Programs (MSP) help pay Medicare premiums, deductibles, and coinsurance for individuals meeting income and asset requirements. These state-administered programs come in several variations: Qualified Medicare Beneficiary (QMB), Specified Low-Income Medicare Beneficiary (SLMB), and Qualifying Individual (QI) programs.
2026 Income limits for Medicare Savings Programs (approximate):
- QMB: Up to $1,275/month individual, $1,724/month couple
- SLMB: $1,275-$1,529/month individual, $1,724-$2,065/month couple
- QI: $1,529-$1,719/month individual, $2,065-$2,320/month couple
These programs don't directly affect your aetna senior supplemental eligibility, but they can free up financial resources by covering Part B premiums, potentially making Medigap coverage more affordable within your budget. While MSPs don't pay Medigap premiums directly, the savings on Part B costs help offset supplemental insurance expenses.
Comparing Carriers Beyond Aetna
While this guide focuses on aetna senior supplemental eligibility, prudent Medicare planning includes comparing multiple insurance carriers offering Medigap coverage. Since plans are standardized by letter, a Plan G from Aetna provides identical benefits to a Plan G from any other carrier, making premium comparison the primary differentiator.
Regional and national carriers compete for Medicare Supplement business, often with significant price variations for identical coverage. In the Triad Area markets of Greensboro, Kernersville, High Point, and Winston Salem, pricing can differ by hundreds of dollars annually between carriers for the same plan type.
Evaluating Carrier Financial Strength
Beyond premiums, assessing insurance company financial stability protects your long-term coverage security. Rating agencies like A.M. Best, Moody's, and Standard & Poor's evaluate carrier financial strength, with higher ratings indicating greater ability to pay future claims.
Aetna maintains strong financial ratings, but comparing this metric across multiple carriers you're considering ensures you select a company likely to remain solvent throughout your retirement years. Medicare Supplement plans represent long-term commitments, making carrier stability equally important as initial premium rates.
The Healthline Medicare supplement companies guide provides additional perspective on evaluating carriers beyond price alone.
Questions to Ask Before Enrolling
Clarifying your aetna senior supplemental eligibility status requires asking the right questions before submitting applications or making enrollment decisions. These inquiries help ensure you time your enrollment optimally and select coverage matching your healthcare needs.
Critical pre-enrollment questions:
- Am I currently within a guaranteed issue enrollment period?
- Which plan types does Aetna offer in my specific county?
- What premium rating method does Aetna use for this plan in my state?
- Are there household discounts for spouses both enrolling?
- Does this plan include any additional benefits beyond standardized coverage?
- What are the specific underwriting requirements if I'm outside guaranteed issue periods?
- How do premiums compare to other carriers for identical plan types?
Documenting answers to these questions before enrolling prevents surprises and ensures you maximize your coverage value. For personalized answers specific to your situation, contacting licensed advisors at 336-862-1763 or moserinsurancegroup@gmail.com provides direct access to expertise focused on North Carolina Medicare beneficiaries.
Long-Term Coverage Planning
Securing your aetna senior supplemental eligibility represents just the first step in comprehensive Medicare planning. Once enrolled, understanding how your coverage evolves and what future changes might affect your policy helps maintain continuous protection throughout retirement.
Medicare Supplement plans offer guaranteed renewal, meaning carriers cannot cancel your coverage as long as you pay premiums on time. This protection remains in effect regardless of health changes, claims filed, or age-related factors. Even if you develop serious health conditions after enrollment, your Medigap policy continues with identical benefits.
When to Consider Changing Plans
Most beneficiaries maintain their initial Medigap plan throughout retirement, as switching often requires new medical underwriting. However, certain situations warrant reconsidering your coverage:
Moving to a different state may require new enrollment since Medicare Supplement plans are state-specific. Your guaranteed issue rights may apply depending on circumstances, but carrier availability and plan options differ by location.
Significant premium increases from your current carrier might justify shopping alternatives, though switching likely requires underwriting unless you qualify for guaranteed issue through another triggering event.
Changes in health status improving your underwriting profile could enable switching to lower-cost carriers if you initially enrolled during guaranteed issue with health concerns.
For those looking to complement their Medicare coverage beyond just traditional supplements, exploring options like Medicare Supplement Plans provides additional context on comprehensive coverage strategies. Some seniors also investigate supplemental policies beyond Medigap, such as hospital indemnity plans that provide cash benefits during hospitalizations regardless of other coverage.
Understanding aetna senior supplemental eligibility empowers Medicare beneficiaries to secure comprehensive coverage at the optimal time, avoiding unnecessary out-of-pocket expenses and protecting against potential denial due to health conditions. Whether you're approaching your initial enrollment period or facing a qualifying event that restores guaranteed issue rights, knowing exactly when and how to apply ensures you don't miss critical windows for coverage access. Moser Insurance Group Inc specializes in helping individuals throughout the Triad Area navigate Medicare supplement eligibility, enrollment timing, and plan selection with clear, pressure-free guidance. For personalized support understanding your specific eligibility situation and exploring available coverage options, visit Moser Insurance Group Inc or call 336-862-1763 to connect with experienced advisors dedicated to your Medicare success.
Recent Comments