

When planning for the future, many individuals over 50 explore permanent life insurance options that provide both protection and financial stability. Understanding aarp whole life insurance rates becomes essential for those seeking guaranteed coverage that lasts a lifetime. These policies offer unique benefits designed specifically for mature adults, combining death benefit protection with a savings component that grows over time. Whether you're in the Triad Area, Greensboro, Kernersville, High Point, or Winston Salem, knowing how these rates are calculated and what factors influence your premiums can help you make informed decisions about your family's financial security.
What Makes AARP Whole Life Insurance Different
AARP partners with New York Life to provide whole life insurance coverage specifically tailored for AARP members. This relationship allows members to access permanent life insurance without medical exams in many cases, making coverage more accessible for seniors who might have health concerns.
The program offers several distinctive features that set it apart from traditional whole life policies. Guaranteed acceptance is available for certain coverage amounts, meaning applicants cannot be turned down for health reasons. The premiums remain fixed for life, never increasing as you age or if your health changes. Additionally, the policy builds cash value that grows on a tax-deferred basis, which can be borrowed against or withdrawn if needed.
Coverage Options and Policy Structure
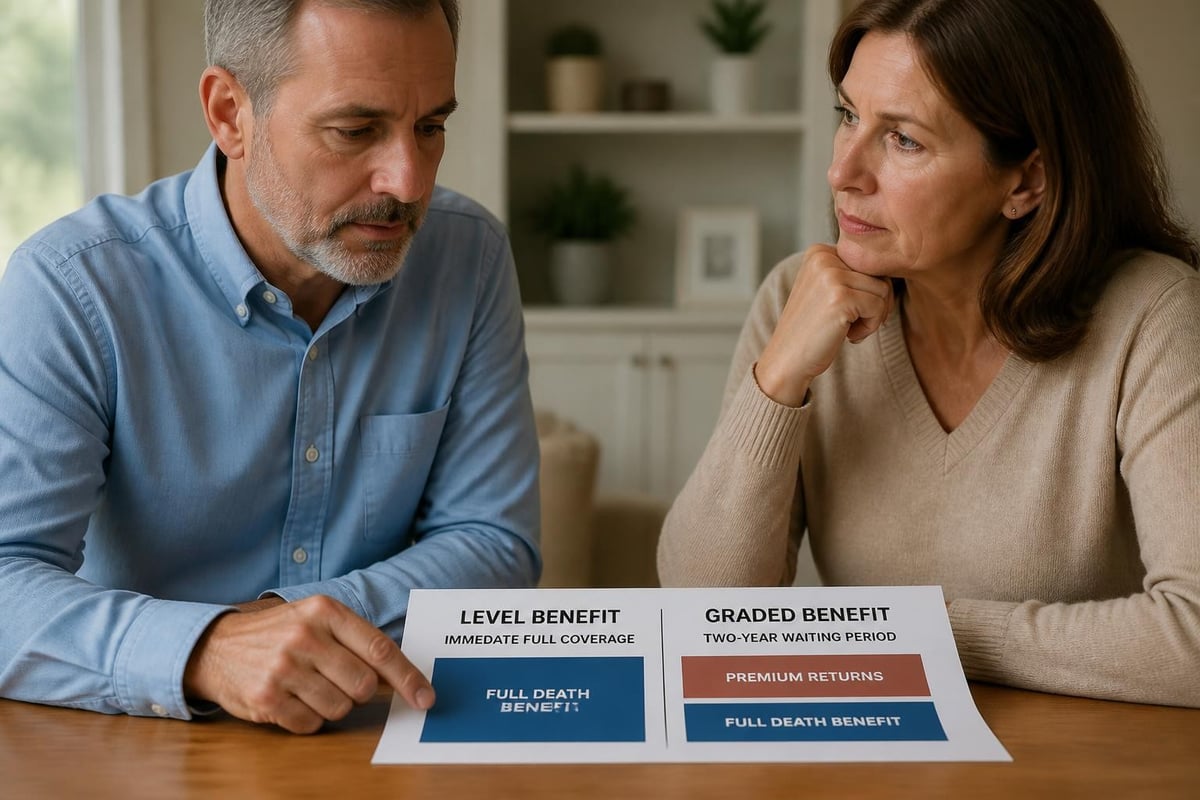
AARP whole life insurance comes in two primary formats: the Level Benefit option and the Graded Benefit option. The Level Benefit plan provides full death benefit coverage from day one, assuming you qualify based on health questions. This option typically requires answering medical questions but offers immediate full protection.
The Graded Benefit plan, conversely, guarantees acceptance regardless of health status. During the first two years, if death occurs from natural causes, beneficiaries receive a return of premiums paid plus interest. After this period, the full death benefit becomes payable. This structure makes coverage accessible to those with serious health conditions who might otherwise be uninsurable.
Understanding AARP Whole Life Insurance Rates by Age
Age serves as the primary factor determining aarp whole life insurance rates. Premiums increase substantially as applicants get older, reflecting the increased risk insurers assume. The impact of age on whole life insurance costs demonstrates this relationship clearly across all providers.
| Age Range | Approximate Monthly Premium (Male) | Approximate Monthly Premium (Female) | Coverage Amount |
|---|---|---|---|
| 50-54 | $85-$110 | $70-$95 | $10,000 |
| 55-59 | $110-$145 | $90-$120 | $10,000 |
| 60-64 | $150-$190 | $120-$155 | $10,000 |
| 65-69 | $195-$250 | $160-$205 | $10,000 |
| 70-74 | $260-$330 | $210-$270 | $10,000 |
These rates represent general ranges and can vary based on specific health factors, coverage amount, and the benefit option selected. Women typically pay lower premiums than men at the same age due to longer life expectancy statistics.
How Coverage Amounts Affect Your Premium
AARP offers coverage amounts ranging from $5,000 to $50,000 in increments of $5,000. The relationship between coverage amount and premium is directly proportional but not always linear. Larger coverage amounts provide better value per thousand dollars of coverage.
For example, a 60-year-old male purchasing $10,000 in coverage might pay approximately $170 monthly, while $20,000 in coverage could cost around $320 monthly rather than exactly double. This pricing structure rewards those who can afford higher coverage amounts with slightly better per-unit rates.
Factors That Influence AARP Whole Life Insurance Rates
Beyond age and coverage amount, several other elements affect what you'll pay for aarp whole life insurance rates. Understanding these factors helps you anticipate your costs and potentially find ways to secure better rates.
Health status plays a significant role for Level Benefit policies. While AARP's guaranteed acceptance Graded Benefit option doesn't require medical exams, the Level Benefit plans do ask health questions. Conditions like diabetes, heart disease, or cancer history can influence whether you qualify for Level Benefit coverage or need to opt for the Graded Benefit plan instead.
Gender differences create notable premium variations. Women statistically live longer than men, which translates to lower insurance costs. A 65-year-old woman might pay 20-25% less than a man of the same age for identical coverage.
Tobacco use significantly impacts rates across all life insurance products. Smokers can expect to pay substantially more than non-smokers, sometimes 50-100% higher premiums for the same coverage.
Geographic Considerations
While aarp whole life insurance rates remain relatively consistent nationwide, state regulations can create minor variations. Residents in the Triad Area, including Greensboro, Kernersville, High Point, and Winston Salem, will find pricing similar to other North Carolina locations. State insurance departments regulate premium charges to ensure fairness and prevent discrimination.
Some states also have specific requirements about policy features or consumer protections that can marginally influence costs. North Carolina maintains robust insurance oversight, which helps ensure competitive and fair pricing for consumers.
Comparing AARP Rates to Traditional Whole Life Insurance
When evaluating aarp whole life insurance rates against traditional whole life policies, several distinctions emerge. Traditional whole life insurance costs vary widely based on carrier, health underwriting, and policy features.
AARP's guaranteed acceptance option provides access to coverage that might otherwise be unavailable. However, this accessibility comes with trade-offs. The Graded Benefit plan's two-year waiting period before full death benefits apply represents a significant limitation compared to traditional policies with immediate full coverage.
Premium levels often run higher on guaranteed acceptance plans compared to fully underwritten traditional policies. A healthy 60-year-old might secure better rates through a traditional carrier with medical underwriting than through AARP's guaranteed option. However, someone with health issues would find AARP's guaranteed acceptance invaluable.
Cash Value Accumulation Differences
Both AARP and traditional whole life policies build cash value, but accumulation rates differ. AARP’s whole life insurance features include modest cash value growth that starts slowly in early years and accelerates over time.
Traditional whole life policies from major carriers sometimes offer higher dividend rates and faster cash value accumulation, particularly for larger policy amounts. The cash value component functions similarly across providers, allowing policyholders to borrow against it or make withdrawals, though both actions reduce the death benefit if not repaid.
The Application Process and Rate Determination
Obtaining aarp whole life insurance rates begins with determining your eligibility. AARP membership is required, which costs $16 annually and provides access to various benefits beyond insurance. Membership is available to anyone 50 or older, with no additional qualifications.
The application process varies by coverage type:
- Visit the official website or call to request information
- Select your coverage amount from available options ($5,000-$50,000)
- Choose between Level Benefit and Graded Benefit plans
- Answer health questions (for Level Benefit) or proceed directly (for Graded Benefit)
- Review your premium quote based on age, gender, and selections
- Complete the application and set up payment arrangements
For Level Benefit policies, the health questions and underwriting process determine your acceptance. Questions cover recent hospitalizations, diagnoses of serious conditions, and current medications. No medical exam is required, but your answers must be truthful to avoid coverage disputes later.
Payment Options and Premium Flexibility
AARP offers several payment frequency options that can affect your overall costs. Monthly payments provide the lowest upfront commitment but typically cost slightly more over time than annual payments. Some members opt for quarterly or semi-annual payments to balance cash flow with cost efficiency.
Premiums can be paid via automatic bank draft, credit card, or check. Automatic payment arrangements often include small discounts and ensure coverage never lapses due to missed payments. The policy includes a 31-day grace period if a payment is missed, providing time to catch up without losing coverage.
When AARP Whole Life Insurance Makes Sense
Understanding whether aarp whole life insurance rates represent good value requires evaluating your specific circumstances and goals. This coverage type excels in particular situations while other options might serve different needs better.
Guaranteed acceptance is crucial for those with serious health conditions. If you've been declined for traditional life insurance or have conditions like advanced diabetes, COPD, or cancer history, AARP's Graded Benefit plan might be your only accessible option for coverage.
Final expense planning represents a primary use case. The coverage amounts ($5,000-$50,000) align perfectly with typical funeral costs, outstanding medical bills, and small debts that families shouldn't bear after your passing. Many seniors specifically seek this coverage to prevent burdening their children with end-of-life expenses.
Simplified application appeals to many. The no-exam process saves time and eliminates the anxiety some feel about medical testing. For busy individuals or those in the Triad Area who want straightforward coverage, this convenience holds value.
Situations Where Alternatives Might Be Better
Whole life insurance serves different purposes than term coverage. If you're younger than 65 and in good health, traditional whole life or even term life insurance might provide more coverage for your premium dollar. Term policies offer substantially higher death benefits at lower costs, though they don't build cash value or last your entire life.
Those seeking significant cash value accumulation as an investment component might find universal life insurance or indexed universal life policies more suitable. These products offer potentially higher returns on cash value, though with different risk profiles and complexity.
If your primary goal is maximizing death benefit coverage rather than guaranteed lifetime protection, term life insurance provides far more coverage per dollar spent. A healthy 55-year-old could secure $250,000 or more in term coverage for similar premiums to a $10,000 whole life policy.
Maximizing Value from Your AARP Whole Life Policy
Once you understand aarp whole life insurance rates and decide this coverage suits your needs, several strategies help you extract maximum value from your policy.
Start earlier rather than later whenever possible. Every year you wait, premiums increase significantly. A 50-year-old pays dramatically less than a 60-year-old for identical coverage. If you know you want permanent coverage, applying sooner saves substantial money over your lifetime.
Choose the right benefit option for your health situation. If you're in decent health and can answer health questions favorably, the Level Benefit option provides immediate full coverage. Only opt for Graded Benefit if health issues would prevent Level Benefit approval.
Consider maximum coverage you can afford. The per-unit cost improves at higher coverage amounts. If your budget allows, purchasing $20,000 or $25,000 instead of $10,000 provides better long-term value, assuming you can maintain the higher premiums.
Understanding Your Cash Value Options
The cash value component of your AARP whole life policy grows slowly at first but accelerates over time. This account earns interest and receives dividends when declared by New York Life. While not guaranteed, New York Life has paid dividends consecutively for over 160 years.
You can access this cash value through:
- Policy loans that charge interest but don't require credit checks or approvals
- Withdrawals that permanently reduce your death benefit
- Premium payments in later years when cash value becomes substantial
These options provide financial flexibility during emergencies or retirement. However, accessing cash value reduces the death benefit, so consider the trade-offs carefully. For instance, if you've built $5,000 in cash value and borrow it, your death benefit decreases by that amount plus interest until repaid.
Comparing Costs Across Different Scenarios
To illustrate how aarp whole life insurance rates vary in practice, consider these representative scenarios based on typical applicant profiles:
Scenario 1: Healthy 55-Year-Old Woman, Non-Smoker
- Coverage: $15,000 Level Benefit
- Approximate monthly premium: $135-$160
- Full death benefit from day one
- Cash value begins accumulating immediately
Scenario 2: 68-Year-Old Man with Diabetes History
- Coverage: $10,000 Graded Benefit
- Approximate monthly premium: $220-$250
- Two-year waiting period for full benefit
- Guaranteed acceptance regardless of health
Scenario 3: 62-Year-Old Woman, Former Smoker (Quit 5+ Years)
- Coverage: $25,000 Level Benefit
- Approximate monthly premium: $280-$320
- May qualify for non-smoker rates if quit over 2 years ago
- Higher coverage provides better per-unit value
These scenarios demonstrate how personal factors combine to determine your specific rates. Additional whole life rate examples from other carriers show similar patterns, though AARP's guaranteed acceptance option provides unique value for those with health challenges.
Policy Features and Benefits Beyond Basic Coverage
AARP whole life insurance rates include more than just death benefit protection. Several built-in features add value without additional cost.
Accidental Death Benefit coverage is available as a rider, doubling the death benefit if death results from a covered accident. This optional feature costs extra but provides enhanced protection during the policy's early years.
Waiver of Premium options exist for some plans, suspending premium payments if you become totally disabled. This protection ensures your coverage continues even if health issues prevent you from working and earning income.
Accelerated Death Benefit provisions allow accessing a portion of your death benefit if diagnosed with a terminal illness. This feature provides financial resources when you need them most, though it reduces what beneficiaries ultimately receive.
Customization and Flexibility
While AARP policies have less customization than some traditional whole life products, you can still tailor coverage to your situation. Coverage amounts adjust in $5,000 increments, letting you match the death benefit to specific needs like funeral costs, outstanding debts, or legacy goals.
You can also add coverage for your spouse through a separate policy, with each person's rates calculated independently based on their age and health. Some couples purchase policies for both partners to ensure survivor protection regardless of who passes first.
Current Economic Factors Affecting Rates in 2026
Interest rate environments significantly influence whole life insurance costs and performance. In 2026, understanding these economic dynamics helps contextualize aarp whole life insurance rates and their value proposition.
Federal Reserve policies affect the returns insurance companies earn on their invested assets. These returns partially fund policyholder dividends and influence premium pricing. When interest rates rise, carriers can generate higher returns, potentially leading to better dividend performance for policyholders.
Inflation considerations also matter for permanent life insurance. While the death benefit remains fixed, the purchasing power of that benefit erodes over time in inflationary periods. Some carriers offer inflation-adjusted riders, though AARP's program focuses on fixed benefit amounts.
Life expectancy trends continue shifting as medical advances extend lifespans. These improvements affect actuarial calculations underlying premium rates. As people live longer, insurance companies adjust pricing to account for paying death benefits later than historical averages predicted.
Making the Decision: Is AARP Whole Life Right for You?
Determining whether aarp whole life insurance rates justify the coverage requires honest assessment of your needs, budget, and alternatives. Consider these key questions:
- Do you have health conditions that make traditional underwritten policies difficult to obtain?
- Is your primary goal to cover final expenses rather than leave a large inheritance?
- Can you comfortably afford the fixed premium payments for the rest of your life?
- Do you value guaranteed acceptance and simplified applications?
- Are you over 50 and eligible for AARP membership?
If you answered yes to most questions, AARP whole life insurance deserves serious consideration. The guaranteed acceptance Graded Benefit option particularly suits those with health issues who need coverage despite medical conditions.
However, if you're in good health, younger than 60, and seeking maximum death benefit coverage, exploring traditional term or whole life policies with full medical underwriting might provide better value. These policies often deliver more coverage per premium dollar for healthy applicants.
Getting Personalized Rate Quotes and Expert Guidance
While this guide provides comprehensive information about aarp whole life insurance rates, your specific quote will depend on your unique circumstances. The most accurate way to determine your costs involves requesting a personalized quote based on your age, gender, desired coverage amount, and health status.
Working with an experienced insurance professional helps you navigate the decision process. Licensed agents can compare AARP's offerings against other options, explain trade-offs between different policy types, and ensure you understand exactly what you're purchasing.
For residents in Greensboro, Kernersville, High Point, Winston Salem, and throughout the Triad Area, local expertise makes a difference. An agent familiar with North Carolina regulations and regional considerations can provide targeted guidance that generic online resources cannot match.
Contact information for personalized assistance:
- Phone: 336-862-1763
- Email: moserinsurancegroup@gmail.com
- Website: moserinsurancegroup.com
Professional guidance proves particularly valuable when comparing permanent life insurance options like AARP's whole life coverage against alternatives such as term life insurance or universal life policies. Each product serves different purposes, and understanding which aligns with your goals prevents costly mistakes.
Understanding the Long-Term Financial Impact
When evaluating aarp whole life insurance rates, consider the cumulative cost over time alongside the benefits received. A $200 monthly premium represents $2,400 annually and $24,000 over ten years. This substantial investment should align with your overall financial plan.
Total cost analysis helps contextualize premiums:
| Years of Coverage | Monthly Premium | Total Premiums Paid | Cash Value (Estimated) | Net Cost |
|---|---|---|---|---|
| 5 years | $200 | $12,000 | $1,500 | $10,500 |
| 10 years | $200 | $24,000 | $5,000 | $19,000 |
| 15 years | $200 | $36,000 | $10,000 | $26,000 |
| 20 years | $200 | $48,000 | $17,000 | $31,000 |
These figures demonstrate that while you pay significant premiums, the growing cash value offsets some costs. The death benefit remains constant at your chosen coverage amount throughout this period, providing guaranteed protection regardless of what happens to your health.
Understanding aarp whole life insurance rates empowers you to make informed decisions about permanent life insurance protection tailored for individuals over 50. Whether the guaranteed acceptance, fixed premiums, and lifetime coverage align with your needs depends on your health status, financial goals, and budget. If you're exploring life insurance options in the Triad Area and want personalized guidance on AARP whole life insurance or other coverage types, Moser Insurance Group Inc helps individuals and families understand their options with clear, pressure-free advice. Contact us at 336-862-1763 or moserinsurancegroup@gmail.com to discuss your specific situation and find coverage that protects your family's financial future.
Recent Comments